
Sayari Appoints Jenal Embry Its First Chief Revenue Officer
Source: PR Newswire
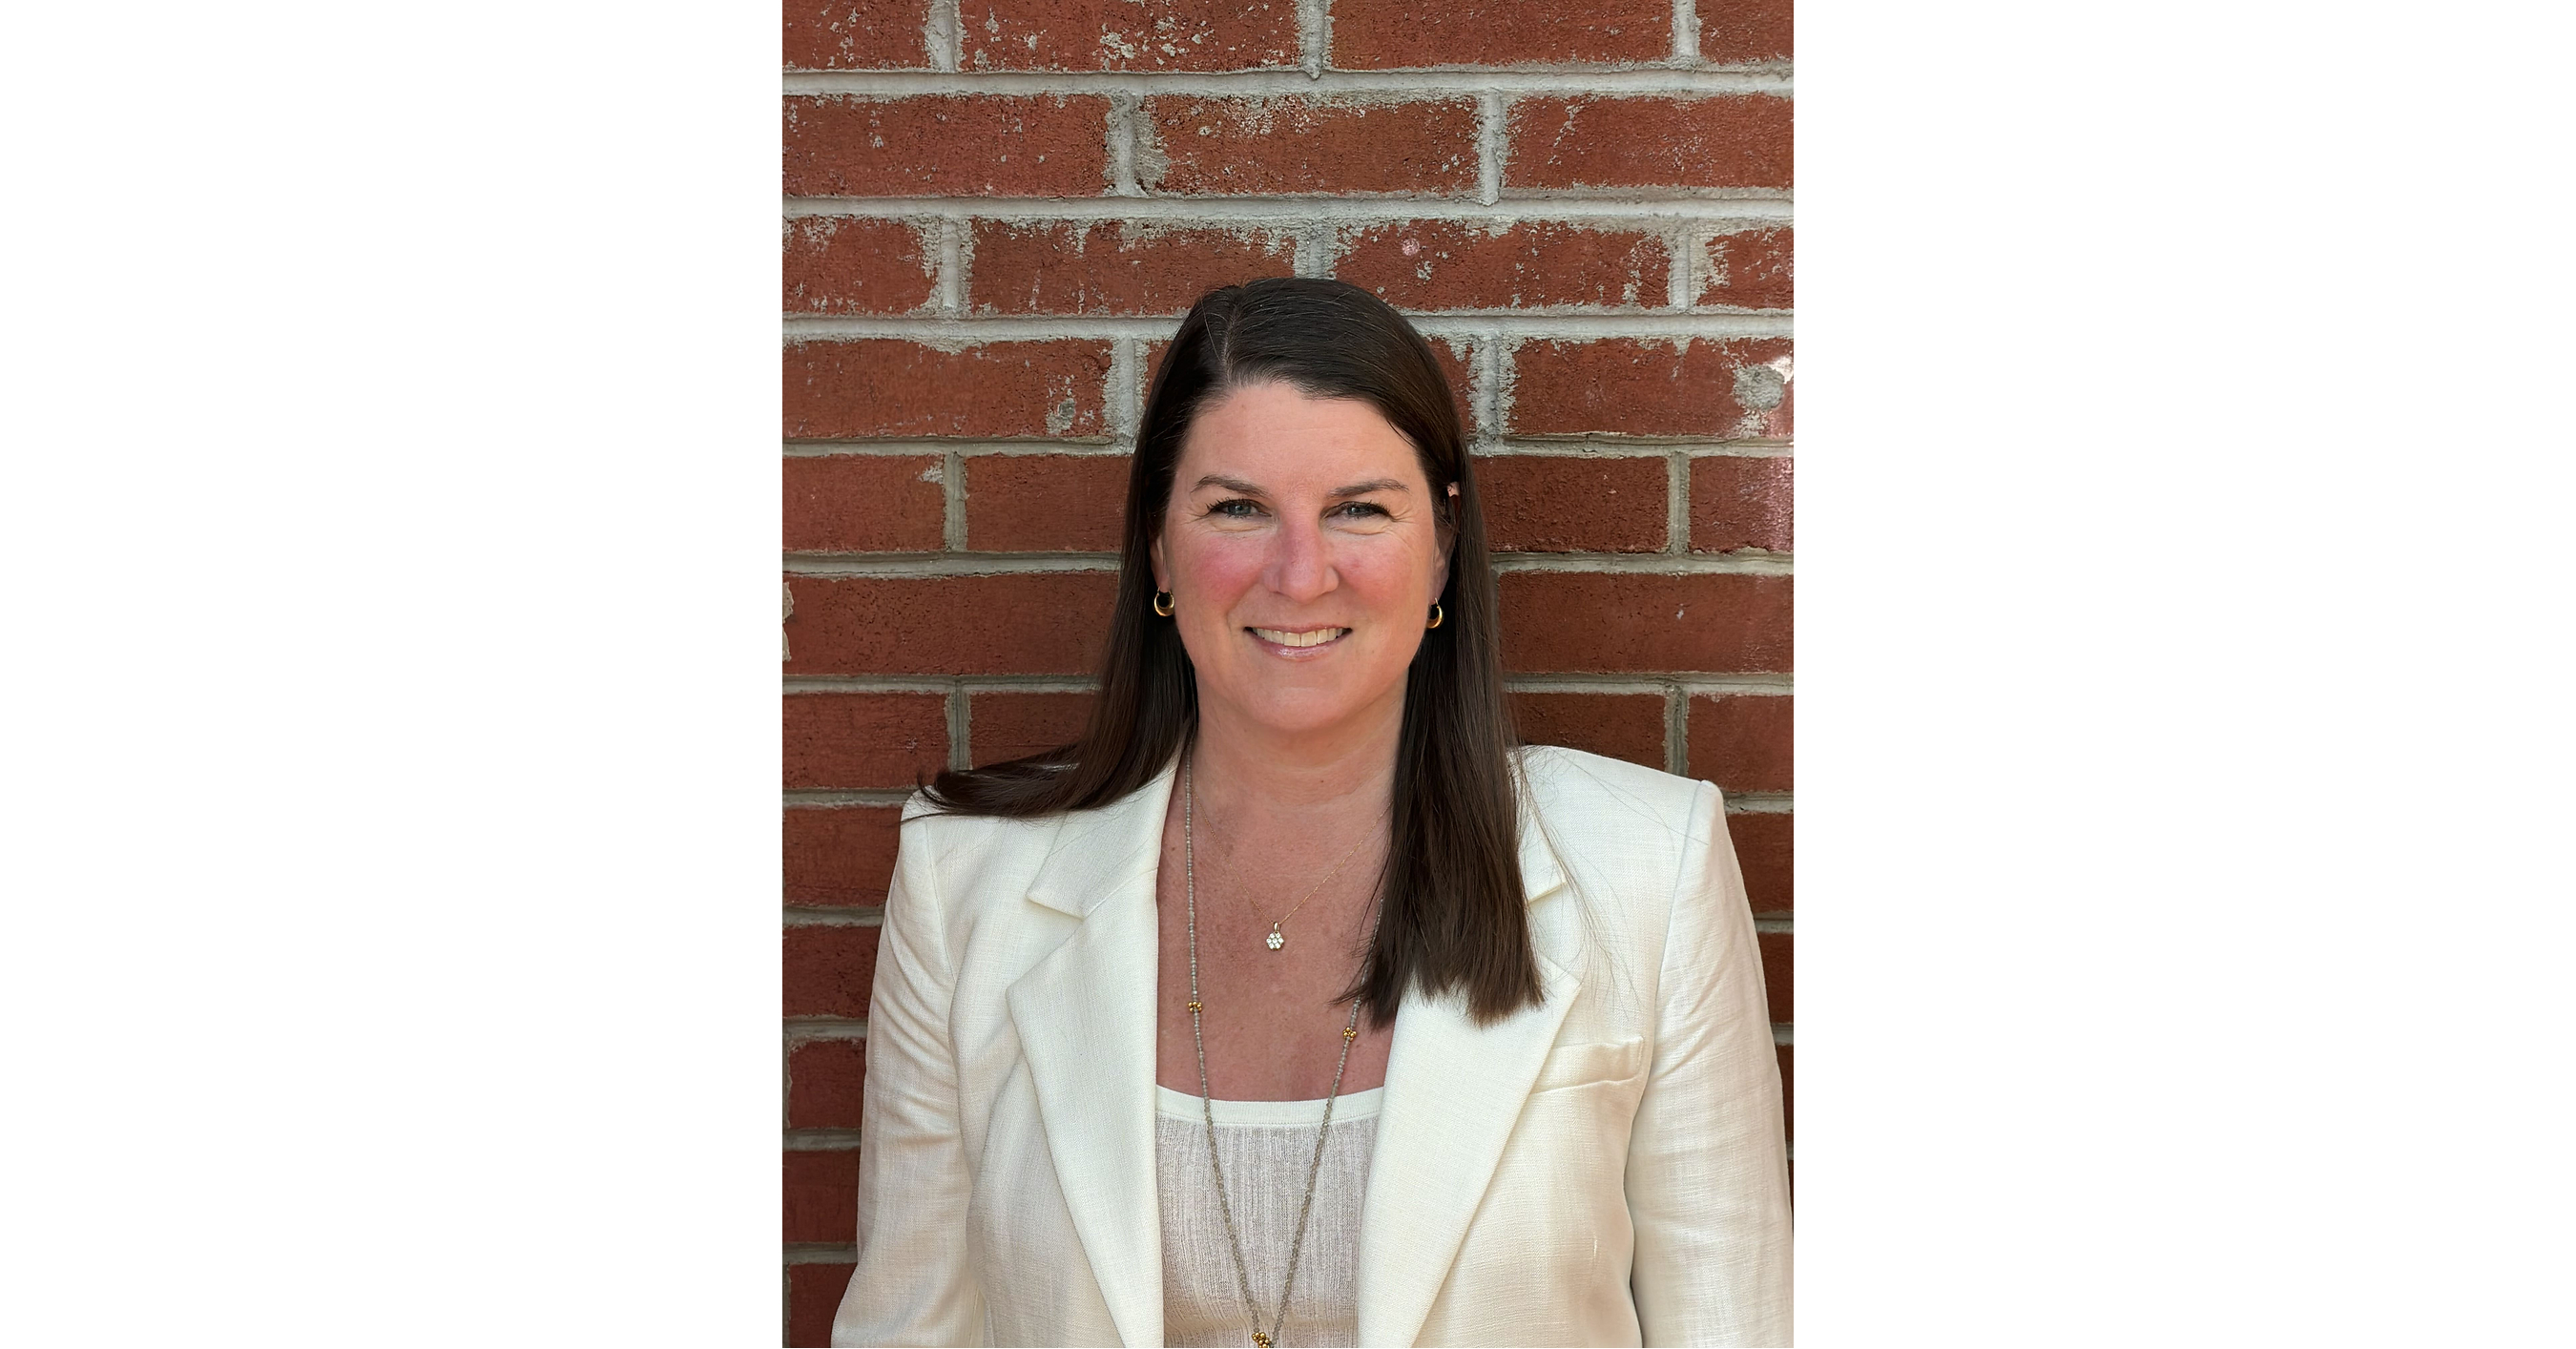
Sayari appointed Jenal Embry as its first chief revenue officer, giving her oversight of go-to-market operations across its Commercial and Government businesses, including sales, customer success, retention and revenue marketing. The company said its Commercial business grew to more than half of annual recurring revenue under Embry's leadership; the announcement supports its strategy to unify revenue teams as data and AI reshape its markets.
Analysis
This is a small, private-company execution signal—not a direct earnings catalyst for UiPath (PATH). Embry’s prior UiPath tenure does not establish any commercial relationship or material impact on PATH, so we see no investable read-through there.
For Sayari, putting commercial and government revenue under one leader could improve account expansion and retention if the same underlying data assets solve overlapping customer problems. The harder question is whether a unified go-to-market motion can preserve distinct procurement, security, and sales processes: government contracting timelines differ materially from enterprise buying cycles. Failure to segment those motions could add organizational friction rather than accelerate bookings.
The second-order competitive implication is modest pressure on established compliance and business-data providers, including Dun & Bradstreet, if Sayari converts its source-traceable data proposition into repeatable enterprise deployments. But the announcement supplies no bookings, retention, contract-value, or margin evidence; claims about platform scale and customer adoption remain company-reported, not proof of monetization. Near term, no public-equity valuation catalyst is evident. Over 1–3 months, watch for customer wins, renewal evidence, and hiring or sales execution signals; over 6–18 months, the key test is whether cross-market selling produces durable recurring revenue without slowing public-sector conversion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade in PATH on this appointment alone; do not infer that an executive’s former employer benefits commercially.
- For investors tracking private-market software or compliance-data providers, treat this as a watch item: seek evidence of improved pipeline conversion, net retention, and cross-market customer expansion before assigning strategic value.
- Monitor Dun & Bradstreet and other compliance-data peers for competitive evidence, but avoid a short thesis absent customer displacement or pricing pressure.
- Falsification / risk trigger: if Sayari’s consolidated sales structure is followed by weaker renewal or booking indicators, or if government sales cycles lengthen without compensating commercial growth, the cross-selling thesis is impaired.
More News
- SK Hynix Posts Record Profit Amid AI Rush
- SK Hynix third-quarter profit sharply beats estimates on AI memory boost
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Anthropic IPO Seeks Investors, With Risks of Catastrophe, Rogue AI
- Tech's relief rally extends as attention turns to tough decisions for the Fed
- Anthropic Gives Traders a Pure-Play Bet on Frontier AI