
Anyang Indorama Gases secures RMB 2.4 billion (c. US$358 million) long term financing for Fertilizer capacity expansion in Henan Province
Source: PR Newswire
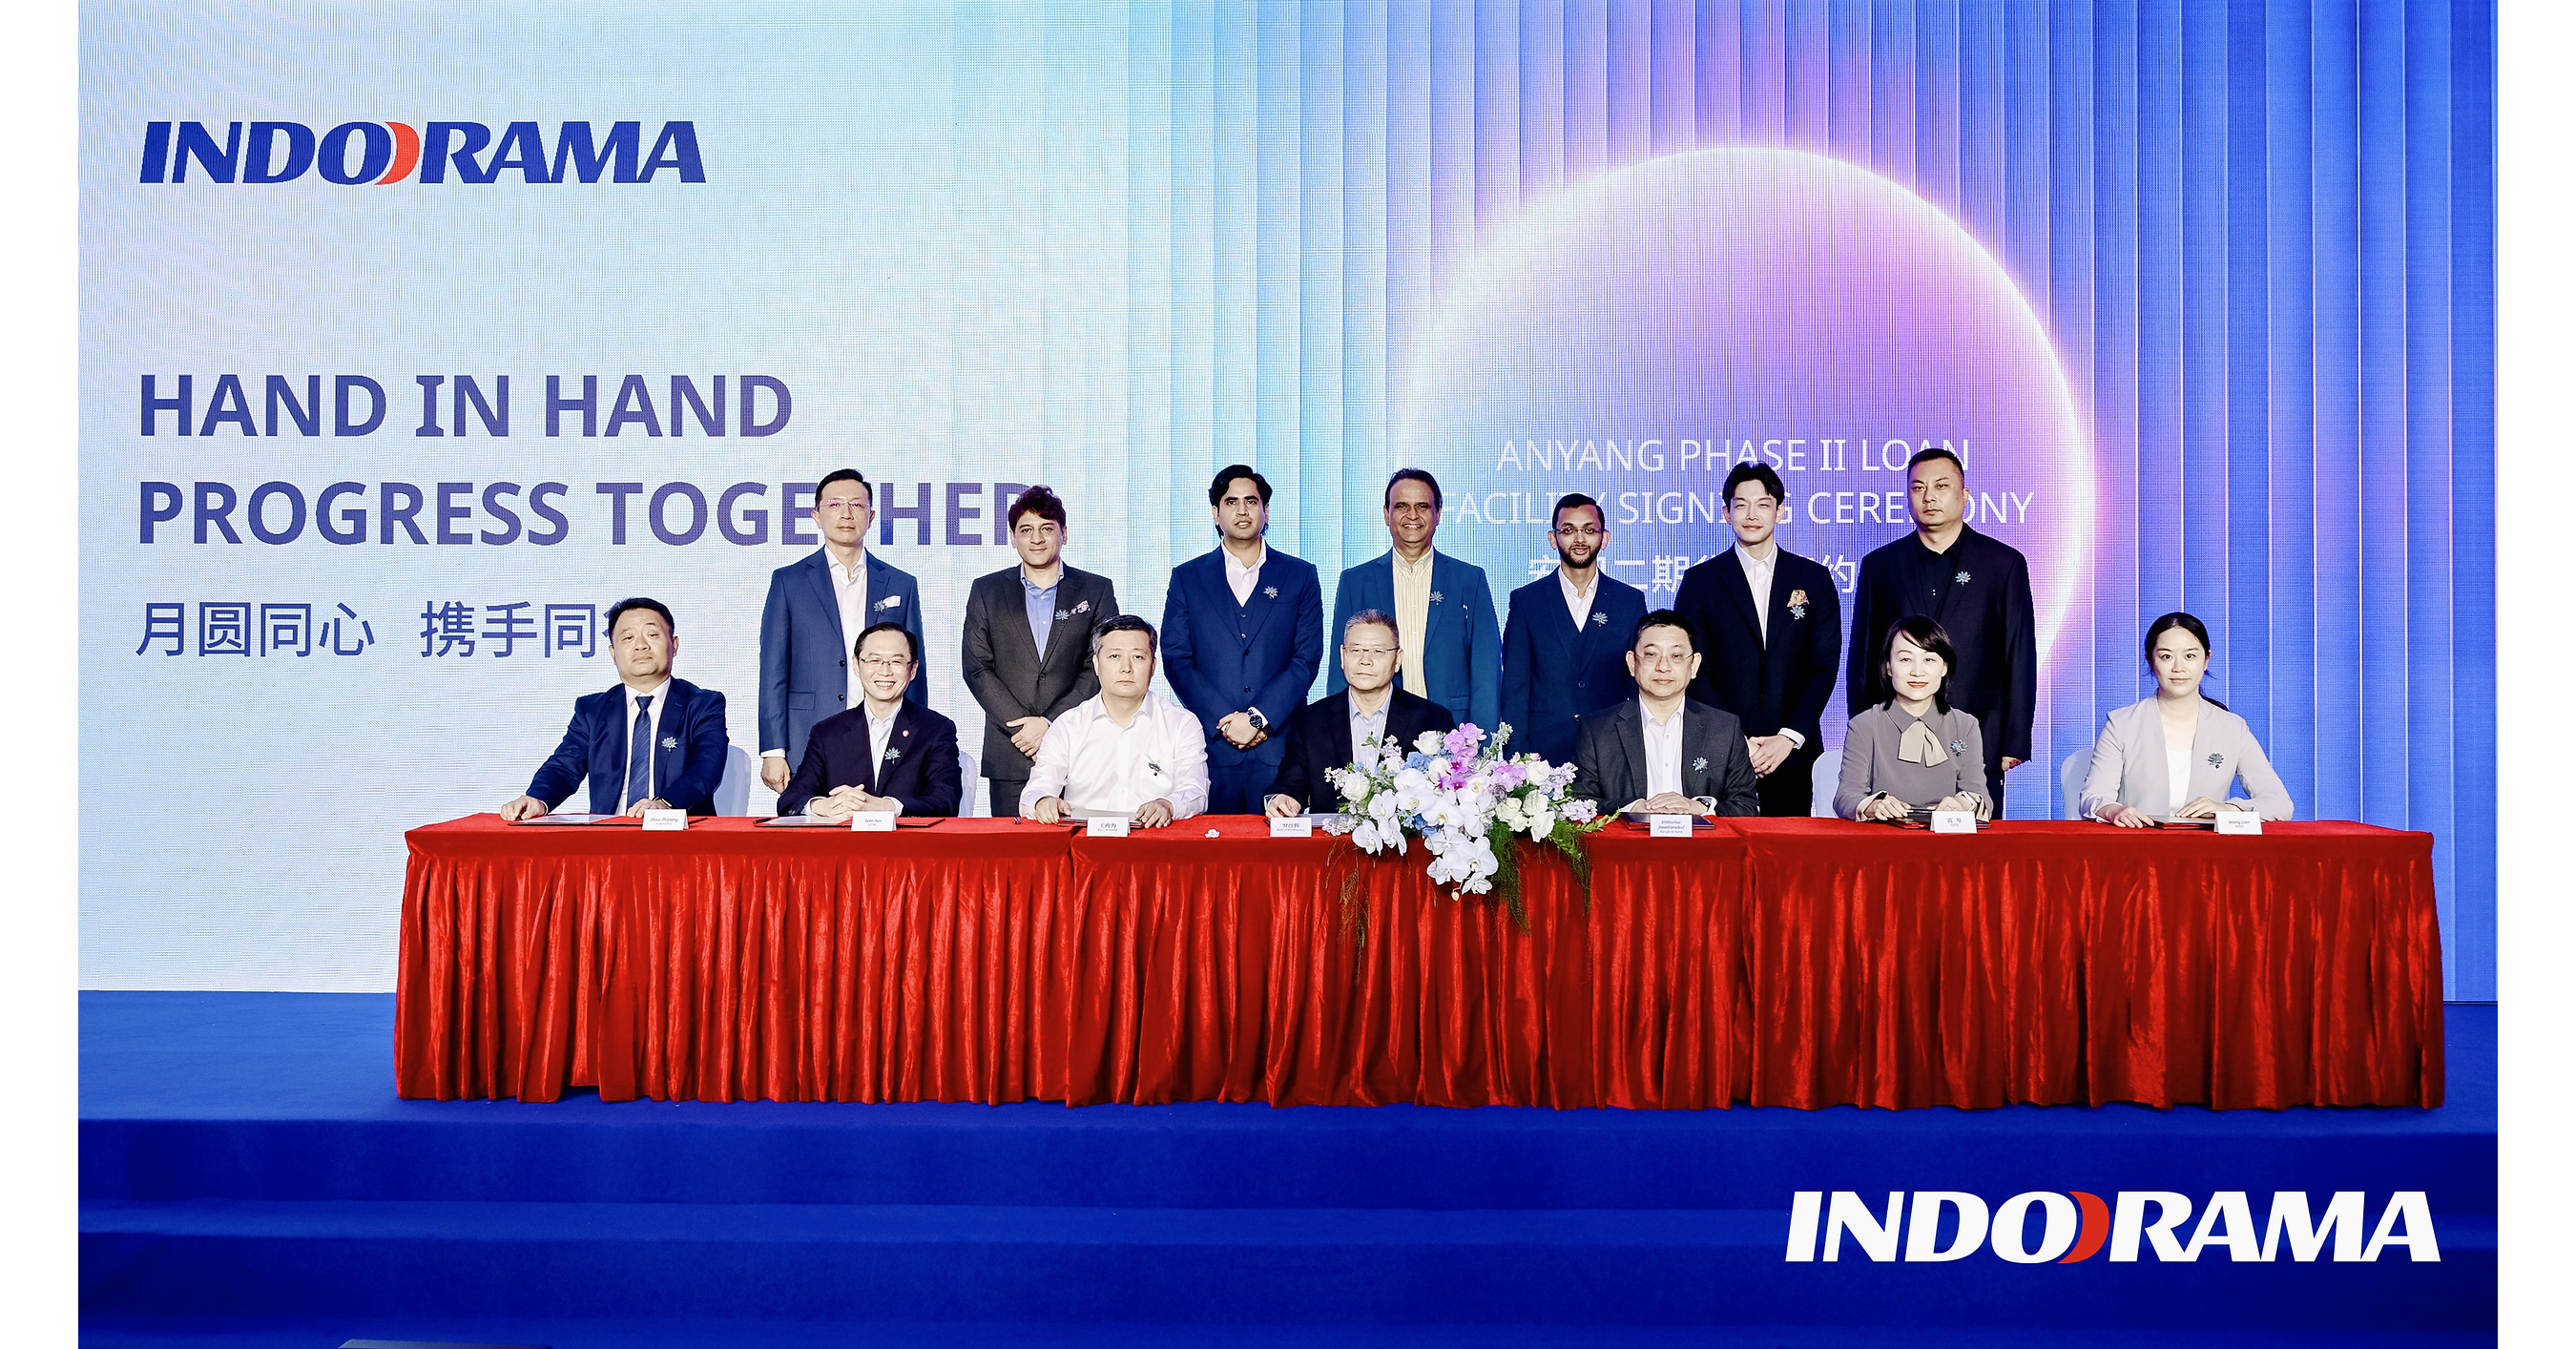
Indorama's Anyang Indorama Gases secured a RMB2.4 billion (US$358 million) long-term syndicated loan to partially fund Phase II expansion of its Henan fertilizer operations. The brownfield project is expected to double urea capacity to about 2 million tonnes annually by 2029, supporting domestic fertilizer availability and food security through more energy-efficient production. The facility, coordinated by OCBC and funded by five Chinese and international banks, follows Indorama's acquisition of the Anyang nitrogen-fertilizer business earlier in 2026.
Analysis
The financing itself is immaterial for the lending syndicate and does not create a public-equity read-through: OCBC (O39.SI), Bank of China (3988.HK), Bank of Communications (3328.HK), China CITIC Bank (0998.HK) and Bangkok Bank (BBL.BK) have balance sheets large enough that a shared RMB2.4bn exposure will not affect earnings or capital ratios. The relevant signal is credit availability for strategic domestic fertilizer assets, which lowers execution funding risk for additional Chinese nitrogen projects and could encourage regional peers to pursue capacity additions before the new environmental/efficiency standards become more restrictive.
A roughly 1mtpa net urea addition by 2029 is modest versus China-wide output but meaningful to the North China regional balance, particularly if grain-price support or export demand disappoints. The marginal impact is likely bearish for Henan-adjacent urea realization and potentially for higher-cost coal-to-urea producers; however, commissioning risk, coal/feedstock costs, and Chinese export policy will matter far more than the announced nameplate capacity over the next 12-24 months. The contrarian point is that modern integrated syngas/ammonia capacity can improve the operator's cost position even if it weakens regional urea pricing, making this primarily a future share-shift rather than a straightforward sector-demand positive.
Near term, this is a watch item rather than a trade catalyst because the project has a multi-year construction window, no listed project sponsor is identified, and neither EPC contractors nor feedstock arrangements are disclosed. A sustained decline in Zhengzhou urea futures relative to thermal coal over the next 6-12 months, combined with evidence of further capacity approvals, would validate a bearish Chinese nitrogen-margin thesis; firm export controls, crop-support stimulus, or materially higher coal prices would falsify it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional position in O39.SI, 3988.HK, 3328.HK, 0998.HK or BBL.BK on this event; treat it as balance-sheet immaterial unless loan pricing, guarantees, or additional project-finance commitments reveal broader asset-quality exposure.
- Create a 6-18 month alert on Zhengzhou urea futures versus Chinese thermal-coal prices: consider a short urea/long coal-spread expression only if new nitrogen capacity approvals accelerate and the urea-to-coal margin remains above historical mid-cycle levels. Exit if export restrictions tighten or grain-support measures lift domestic fertilizer demand.
- Monitor disclosures for EPC, gasification, ammonia-loop, and coal-supply counterparties before seeking an equity expression. A named listed contractor or equipment supplier with material order value would be a cleaner near-term beneficiary than the lenders; absent that data, no construction-supply-chain trade is warranted.
More News
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
- Latest Oil Market News and Analysis for Sept. 23
- Bank of America says Brent crude oil could top $150 a barrel if Iran war disruptions persist