
What Metallus (MTUS) Said on Its Q3 Earnings Call
Source: marketbeat.com
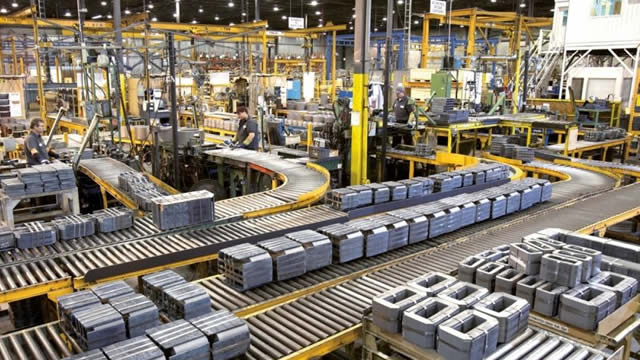
Metallus reported higher third-quarter 2026 sales, profit and adjusted EBITDA, supported by aerospace and defense growth, product mix and pricing actions. The specialty steel producer reached its $250 million annualized aerospace and defense sales run-rate target and secured a Defense Logistics Agency contract with an initial delivery order valued at about $125 million.
Analysis
The read-through is mix quality, not simply faster steel demand: aerospace/defense qualification and procurement relationships may support more durable pricing than commodity steel, while reducing sensitivity to weaker industrial end markets. That could narrow the discount investors apply to Metallus versus specialty-materials peers such as Carpenter Technology and ATI—but only if the announced activity converts into repeat shipments and cash generation. The $125 million initial delivery order is not evidence of recurring revenue or margin; delivery timing, product scope, and follow-on orders remain key diligence items.
Days: a positive earnings reaction is plausible, but the run-rate milestone and contract headline may already be reflected in the share price. Over 1–3 months, watch for order cadence, backlog conversion, and management commentary on realized pricing and margins. Over 6–18 months, successful qualification-led growth could improve earnings durability; the counter-risk is that aerospace/defense demand is too small or lumpy to offset weakness elsewhere. A procurement delay, lower realized margins, or a reversal in pricing would weaken the thesis. The article provides no valuation, cash-flow, or segment-margin detail, so conviction on absolute upside is limited.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Treat MTUS as a conditional quality-of-earnings upgrade, not an automatic growth re-rating. Before adding, verify segment revenue and margin contribution, order delivery schedule, and whether the $250 million annualized run-rate represents shipped sales or a forward target.
- For existing exposure, hold through near-term follow-up data rather than chase the headline; reassess if management does not demonstrate aerospace/defense shipment conversion or if realized pricing and margins deteriorate.
- Watch for evidence of repeat DLA orders and broader customer wins over the next 1–3 months. Their absence would suggest the initial award is a lumpy program rather than a durable earnings catalyst.
- Falsification signals: delayed deliveries, weaker guidance or cash conversion despite higher reported earnings, and renewed pricing pressure. Without valuation and segment economics, there is not enough basis here for a price target or a high-conviction pair trade.
More News
- What Wall Street billionaires are saying about Democrats' midterm sweep
- NextDC shares surge 43% after Goodman, Digital Realty stake purchases
- A blue wave sends futures into the green
- Asian chip stocks slide as disappointing Qualcomm, Arm earnings weigh
- Snap shares fall over 10% on third-quarter earnings miss
- ‘Seismic’ blue wave triggers the sinking of oil prices, energy stocks, and the chances of power permitting reform