
XCMG lance la construction de sa première base à l'étranger dédiée à la révision et au reconditionnement de composants d'équipements miniers en Indonésie
Source: PR Newswire
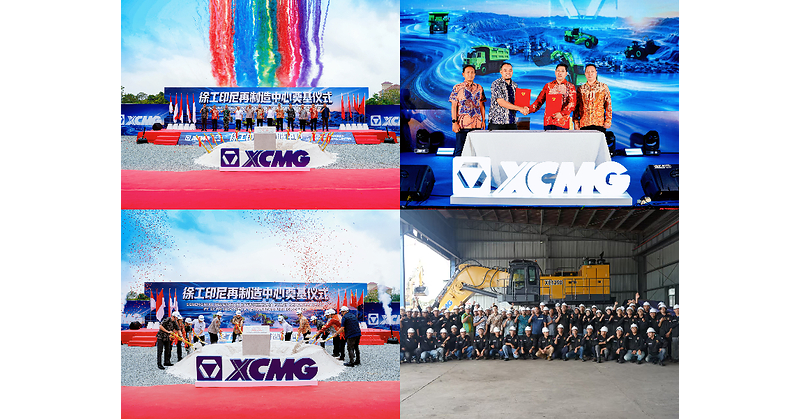
XCMG began construction on its first overseas mining-equipment component overhaul and remanufacturing base in Balikpapan, Indonesia, on September 16. The facility will localize major overhauls, spare-parts storage, technical training and used-equipment refurbishment, aiming to reduce customer downtime and operating costs. The project expands XCMG's Indonesian footprint alongside its recently launched local finance company, new-energy production base and R&D center, supporting its shift toward full-lifecycle equipment solutions.
Analysis
The strategic significance is not equipment volume but capture of the highest-margin, stickiest portion of the mining-equipment value chain. Local remanufacturing plus captive financing can lower customers’ upfront and lifecycle cash costs simultaneously, increasing XCMG’s installed-base conversion and creating switching costs around parts availability, credit terms and technician relationships. This is most disruptive in Indonesian thermal-coal, nickel and bauxite operations where equipment utilization is high and procurement remains price-sensitive.
For CAT, Komatsu (6301), Epiroc (EPI-A.ST), Sandvik (SAND.ST) and Hitachi Construction Machinery (6305), the near-term earnings impact should be immaterial, but the competitive signal matters: Chinese OEMs are moving from one-off price competition toward recurring aftermarket and financing economics. Over 6-18 months, incumbents may need to defend share through localized parts inventories, service pricing or financing support, placing modest pressure on aftermarket gross margins—the segment investors typically value at a premium to new-equipment sales.
The press-release claims should not be capitalized until there is evidence of utilization, local parts fill rates, financing receivables growth and bad-debt performance. The principal tail risk for XCMG’s model is that bundled credit drives sales but transfers Indonesian commodity-cycle volatility onto its balance sheet; a coal or nickel downturn could expose weaker collateral values and rising delinquencies. The contrarian view is that major miners may continue to pay for CAT/Komatsu uptime guarantees and fleet standardization, limiting XCMG initially to cost-sensitive contractors rather than displacing premium OEM fleets.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate directional trade: the disclosed project is too small and too early to alter global earnings estimates for CAT, KMTUY, EPI-A.ST or SAND.ST. Reassess over the next 1-3 quarters if Indonesian dealer commentary identifies share loss, higher discounting, or lower aftermarket attachment rates.
- Create a competitive-risk watch on CAT and KMTUY: flag any Indonesia/Asia-Pacific aftermarket revenue deceleration, parts-margin compression, or increased financing incentives versus company guidance. Those metrics—not equipment deliveries—would validate a structural threat.
- For a 6-18 month relative-value screen, favor EPI-A.ST or SAND.ST over broad OEM exposure if Indonesian miners prioritize automation, drilling productivity and premium service contracts; these offerings are harder to replicate through low-cost equipment plus local remanufacturing. Falsification: sustained order-share losses in Southeast Asia or service-margin erosion.
- Monitor XCMG-associated Indonesian financing disclosures for receivables growth versus provisions and delinquency indicators. A rapid expansion in credit without corresponding reserve build would be a negative read-through for Chinese construction-equipment credit quality, especially if Indonesian coal or nickel prices weaken materially.
More News
- Saudi Oil Cuts Tied to War Hit Europe: Evening Briefing Americas
- Trump says U.S. to build a 'large Military presence' in Greenland as part of a security deal with it and Denmark
- Houthis accuse Saudi Arabia of launching 26 strikes in 24 hours
- European Economies Eye Another Energy Crisis Heading Into Winter
- AI almost led the US military to start a war with China, report says
- Warren Buffett stepping down as chairman of Berkshire Hathaway: 'Father Time always wins'
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)
- AI Portfolio Monitoring: Build an Alert Policy Analysts Can Audit