
YiKEDA™ debuta en SIAL Paris 2026, llevando bebidas de tomate de primera calidad al escenario mundial
Source: PR Newswire
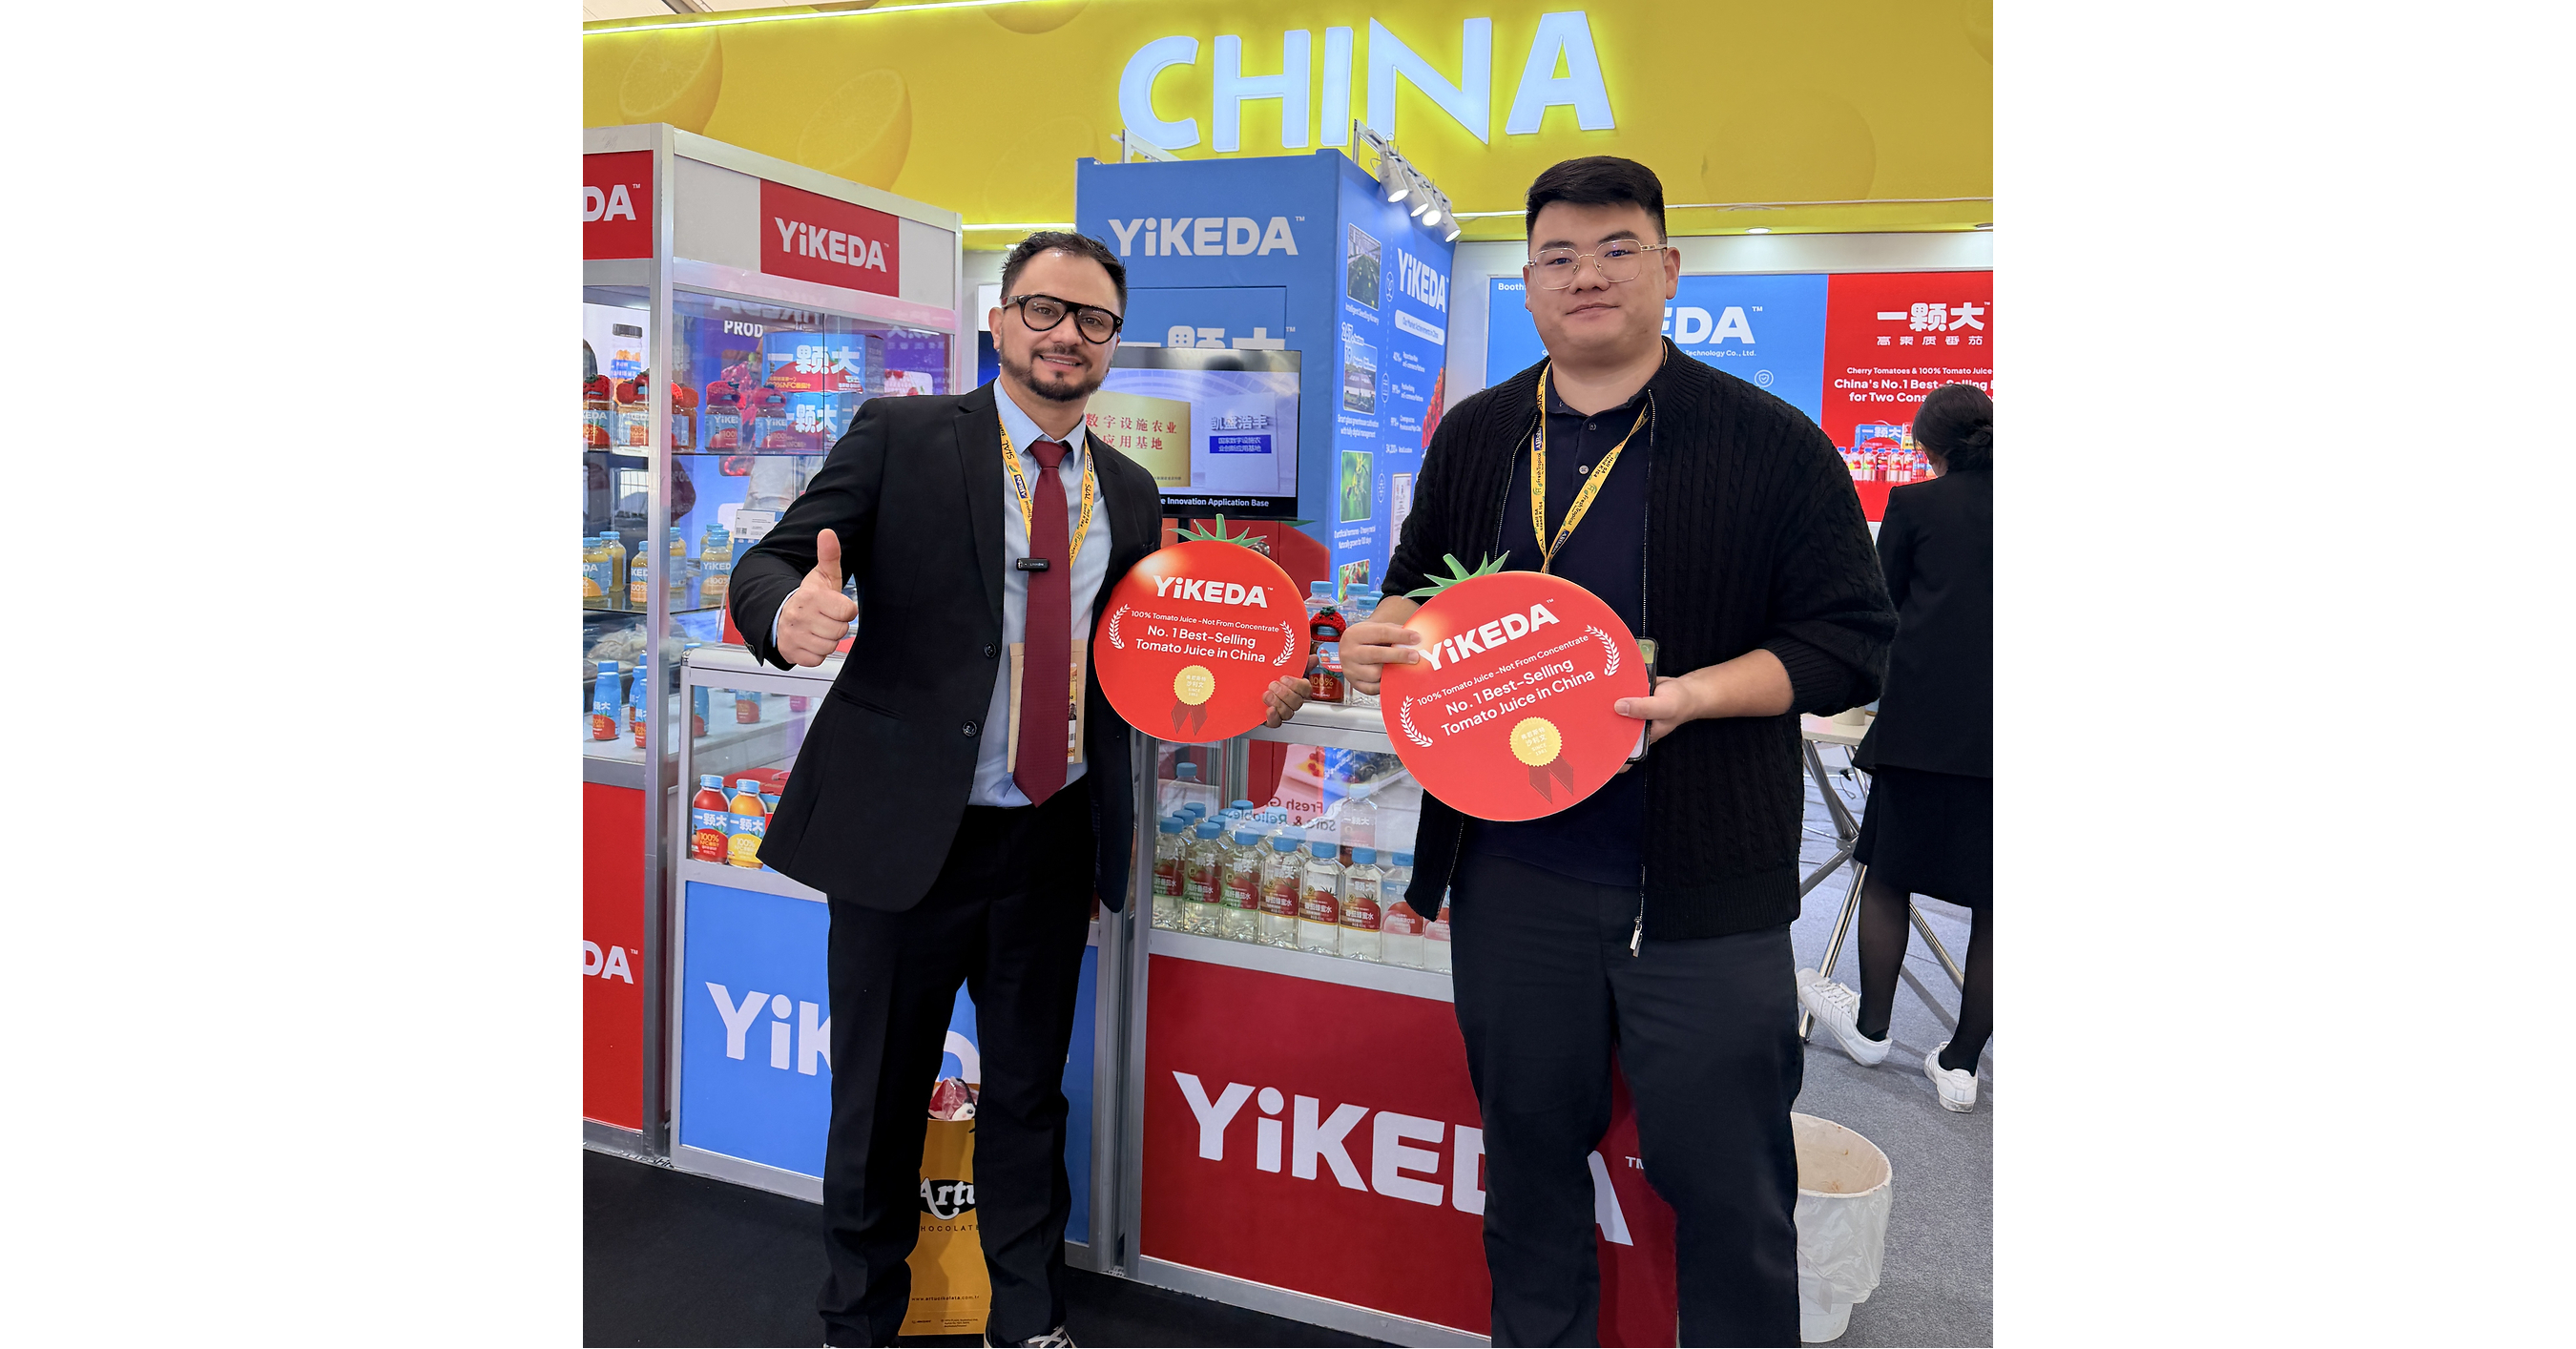
YiKEDA™ debuted at SIAL Paris 2026, presenting its 100% NFC tomato juice and flavored tomato-water beverages to international buyers. The company says its NFC juice is China’s first in the category to receive low-glycemic-index certification, and that the product and its cherry tomatoes each ranked No. 1 in China sales for two consecutive years, according to a Frost & Sullivan recognition it cited. The brand reports exports to multiple markets and plans further international expansion; the announcement provides no sales or financial figures.
Analysis
This is a brand-awareness event, not yet evidence of a material earnings catalyst: a trade-show debut does not establish retailer listings, repeat purchases, or profitable export scale. The potential upside is category differentiation—single-ingredient and low-GI positioning could support premium pricing if consumers accept the taste and the claim is recognized by relevant regulators and retailers. Conversely, scaling tomato beverages beyond existing fresh-produce channels adds processing, packaging, shelf-life, and distribution requirements; controlled greenhouse production alone does not prove competitive delivered cost. Established juice and beverage companies could respond through their own sourcing and distribution advantages, limiting the entrant’s pricing power.
Near term, there is no clear public-equity exposure in the supplied company identities, and no basis for inferring a parent-company earnings impact. Over 1–3 months, the useful catalysts are independently verifiable export listings, reorder evidence, and disclosure of beverage sales or capacity—not further event publicity. Over 6–18 months, energy and packaging costs, utilization, and cold-chain or shelf-stable logistics will determine whether greenhouse integration creates margin advantage or merely transfers costs into a premium product. The key contrarian point: the claimed domestic sales ranking may sound like product-market fit, but without scope, channel, and audited sales data it cannot establish international demand. Thesis weakens if listings fail to convert to repeat orders, the low-GI claim faces regulatory or retailer constraints, or pricing cannot cover distribution costs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No trade on this announcement alone: the company is not mapped to a listed security in the supplied data, and the release provides no verifiable incremental financial disclosure.
- Treat as a watch item for established juice and beverage producers, including Campbell’s and large beverage distributors; do not assume meaningful share loss absent evidence of scaled retail placement or repeat purchasing.
- Set an alert for independently confirmed international listings, reorder rates, and revenue contribution, alongside gross-margin implications from packaging, freight, and shelf-life requirements.
- Reassess only if the company or a mapped parent discloses commercially material export volumes or capacity plans; failure to secure repeat orders within the next few quarters would undermine the premium-growth thesis.
More News
- The U.S. market has never been more focused on one single bet—but AI’s payoff will likely take decades
- Meta put out an ambitious roadmap to Muse monetization after strong quarter and guide
- Russian Drones Are Already Killing People Within EU Territory
- CoreWeave’s market confidence erodes as bond yields spike and stock sinks
- Meta ordered to pay $25 billion in case related to Cambridge Analytica scandal
- Why is Tesla stock falling after-hours today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?
- Earnings-Triggered Research Automations: A Control Guide