
Will Martinez Refinery Restart Strengthen PBF Energy's Cash Flow?
Source: zacks.com
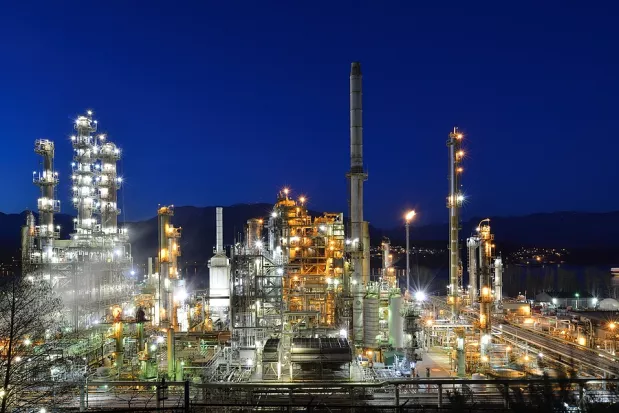
PBF's Martinez refinery returned to full operations in May 2026 after repairs from the February 2025 fire; the company received $250 million in Q2 insurance proceeds, bringing incident-related recoveries to $1.25 billion net of deductibles and retentions. PBF generated $1.6 billion in Q2 operating cash flow, supported by strong refining margins and favorable working capital, and management expects further insurance payments in the second half of 2026. A Martinez hydrocracker turnaround is scheduled to conclude in October. PBF shares gained 140.8% over the past year, and full-year 2026 earnings estimates were revised upward.
Analysis
The key question is whether Martinez adds durable, margin-accretive throughput or merely normalizes PBF’s capacity while easing the scarcity conditions that made West Coast barrels valuable. More local supply can compress California product differentials even as higher utilization lifts PBF’s own volumes; the net benefit depends on realized cracks, crude/feedstock access and sustained run rates—not the restart headline alone.
Near term, the hydrocracker work through October leaves execution risk and may limit the product slate. Over the next 1–3 months, verify utilization, regional cracks and the final insurance settlement. Insurance proceeds and favorable working capital improve liquidity but are not recurring earnings; reconcile reported operating cash flow before extrapolating it. The settlement is also a timing/certainty catalyst, not a new operating profit stream.
PBF’s large prior share advance raises the bar for positive surprises. A below-industry EV/EBITDA multiple is not automatically cheap for a cyclical refiner if current EBITDA reflects unusually strong margins. MPC and VLO’s yield projects are incremental competitive supply, but are not direct substitutes for Martinez’s regional position. The contrarian risk to the bullish thesis is that restored capacity and broader supply growth erode the very margins supporting near-term cash generation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing PBF on cash-flow headlines; treat it as a conditional, event-driven long only after confirming Martinez utilization and West Coast crack spreads remain supportive through the hydrocracker turnaround. Falsify the thesis if operating rates disappoint or regional differentials materially weaken.
- Do not annualize the reported cash generation. Track the cash-flow statement’s working-capital contribution, insurance receipts and remaining claim; regard further proceeds as a liquidity buffer, not a valuation basis for recurring earnings.
- For the next 1–3 months, monitor the October turnaround completion, restart reliability, realized refining margins and final insurance settlement. Reassess if completion slips, guidance weakens, or the settlement falls short of management expectations.
- No strong outright relative-value trade is established from the supplied evidence: MPC and VLO’s upgrades do not prove superior returns, and PBF’s lower stated multiple may reflect higher cyclicality and execution risk. Revisit a PBF-versus-peer position once comparable utilization, margin capture and balance-sheet data are verified.
More News
- SK Hynix Posts Record Profit Amid AI Rush
- SK Hynix third-quarter profit sharply beats estimates on AI memory boost
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Anthropic IPO Seeks Investors, With Risks of Catastrophe, Rogue AI
- Iran’s calculations as US escalation looms: Trust, midterms, Hormuz
- Tech's relief rally extends as attention turns to tough decisions for the Fed