
Moldova eGovernance Agency Launches Banking Use of EVO Digital Identity Credentials Built to European Standards
Source: PR Newswire
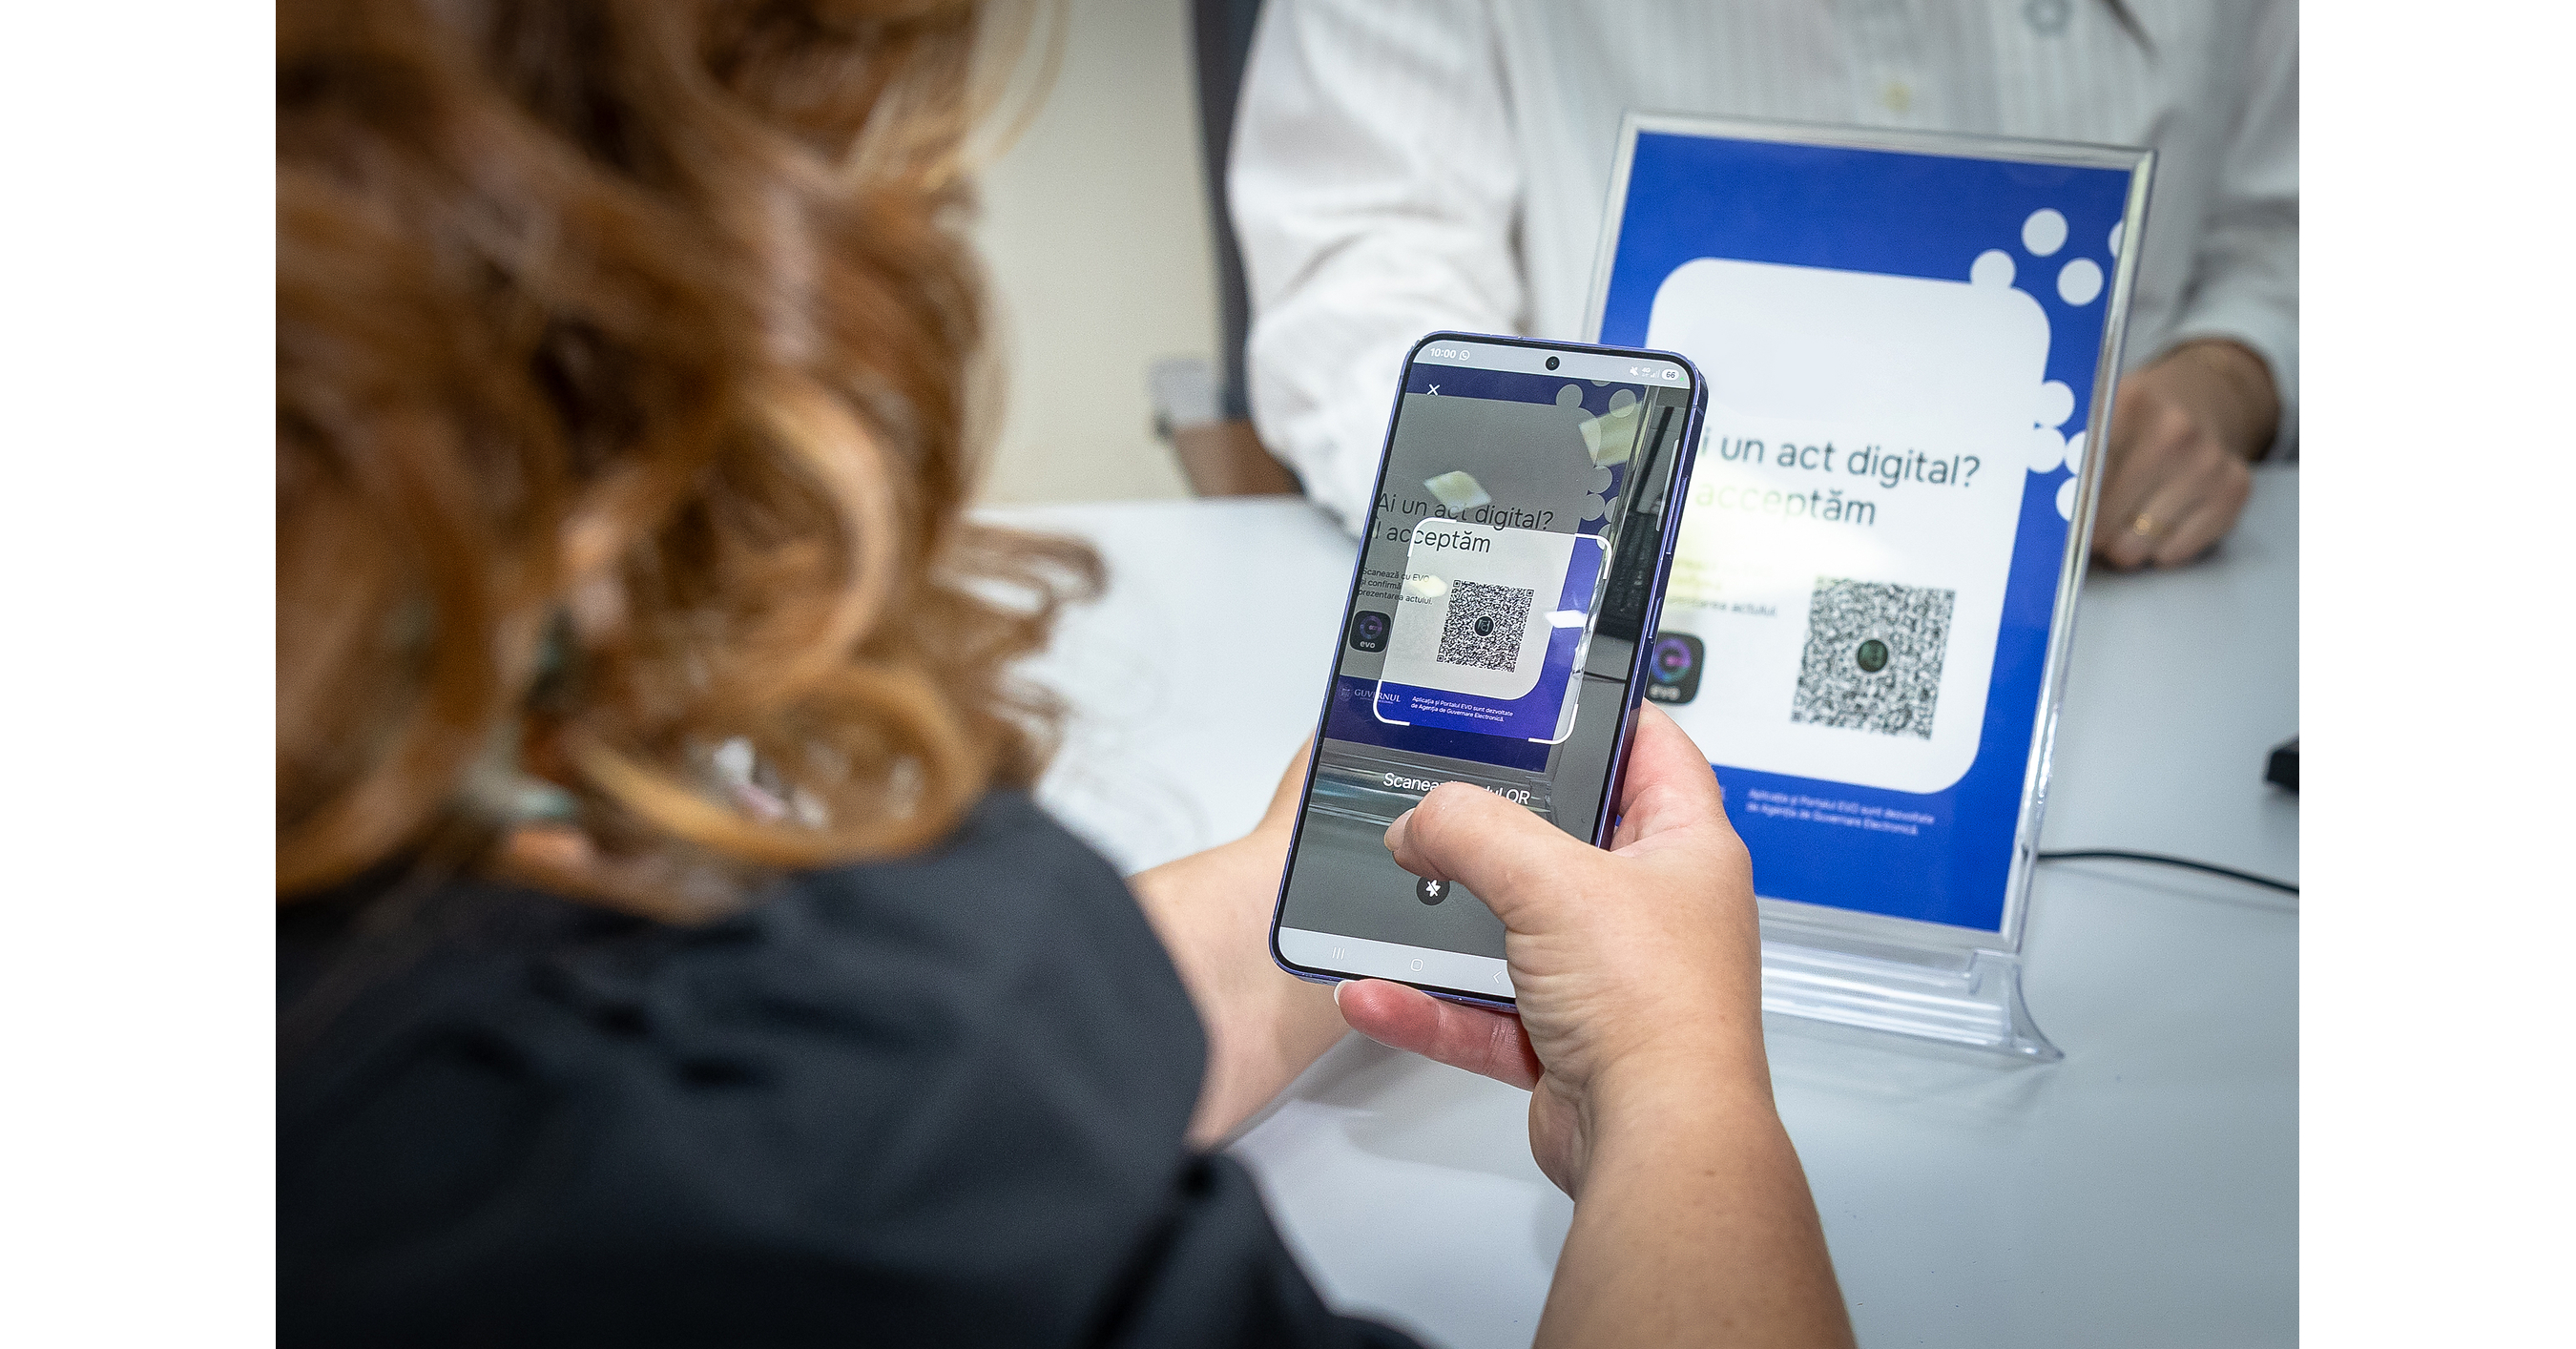
Moldova's EVO digital identity credentials are now accepted by four banks—Moldindconbank, FinComBank, EuroCreditBank and Victoriabank—enabling QR-based digital customer identification without physical document copies. Since private-sector integrations opened on April 1, 2026, 30 relying parties have begun connection processes, with at least 20 expected to be operational by year-end. The rollout aligns EVO with European Digital Identity Wallet standards and supports future cross-border interoperability.
Analysis
There is no investable read-through to NBHC, a U.S. regional bank whose earnings are driven by Colorado-area deposit pricing, commercial credit and loan growth rather than Moldovan digital-ID adoption. Treating this as a fintech catalyst for NBHC would be a category error; the named banks are private/local institutions and the announcement provides no transaction-volume, customer-acquisition or cost-saving disclosure from which to underwrite an earnings impact.
The broader second-order implication is modestly constructive for European digital-identity infrastructure over a 6-18 month horizon: reusable, government-verified credentials can reduce bank onboarding friction, manual KYC cost and certain fraud vectors. However, those economics accrue only after relying-party scale, consumer adoption, liability rules and cross-border credential acceptance are proven. Near-term, the primary beneficiaries are likely unlisted identity-software and systems-integration vendors; listed European payments or bank-core software names should not re-rate on this isolated rollout.
The contrarian point is that digital identity may initially increase, not reduce, bank compliance expense: banks must maintain parallel physical-ID processes, upgrade onboarding controls and absorb fraud/liability ambiguity during migration. A meaningful capital-markets catalyst would require evidence that adoption lowers customer acquisition cost or account-opening time at scale, rather than simply digitizing an existing verification workflow.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No action in NBHC: do not attribute a valuation or earnings catalyst to this development. Reassess only if NBHC announces a relevant U.S. digital-identity partnership with disclosed onboarding, fraud-loss or operating-expense targets.
- Create a 6-12 month watchlist around European digital-ID beneficiaries rather than initiate a position: monitor Worldline (WLN.PA), Nexi (NEXI.MI) and Temenos (TEMN.SW) for contract wins tied to EU wallet implementation. Require disclosed revenue backlog or measurable onboarding-volume growth before underwriting upside.
- For European bank exposure, monitor whether wallet interoperability changes KYC cost or digital-account conversion in 2027 results; absent such KPIs, avoid paying a multiple premium for the theme. Thesis is falsified if parallel compliance requirements keep cost-to-income ratios unchanged despite adoption.
- Watch for regulatory liability allocation and mandatory acceptance deadlines under the European Digital Identity Wallet framework. Clear merchant/bank acceptance obligations could accelerate implementation spend; delayed standards or fragmented national interoperability would push any earnings benefit beyond the current planning cycle.
More News
- What is BRICS Pay, and can it rival the West’s SWIFT payments system?
- Fed hikes again - an AI-Picked insurer is still cashing in
- Congress passes sweeping US sanctions bill targeting Russia
- US official says upcoming spectrum auctions could generate more than $100 billion
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- Analysis: How Trump could reignite the Fed independence fight after Warsh's rate hike
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Financial Research Benchmarks: What the Scores Mean
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper