
ProLogium Begins Mass Production of High-Energy-Density All-Solid-State Battery, Reaching 381 Wh/kg and 903 Wh/L
Source: globenewswire.com
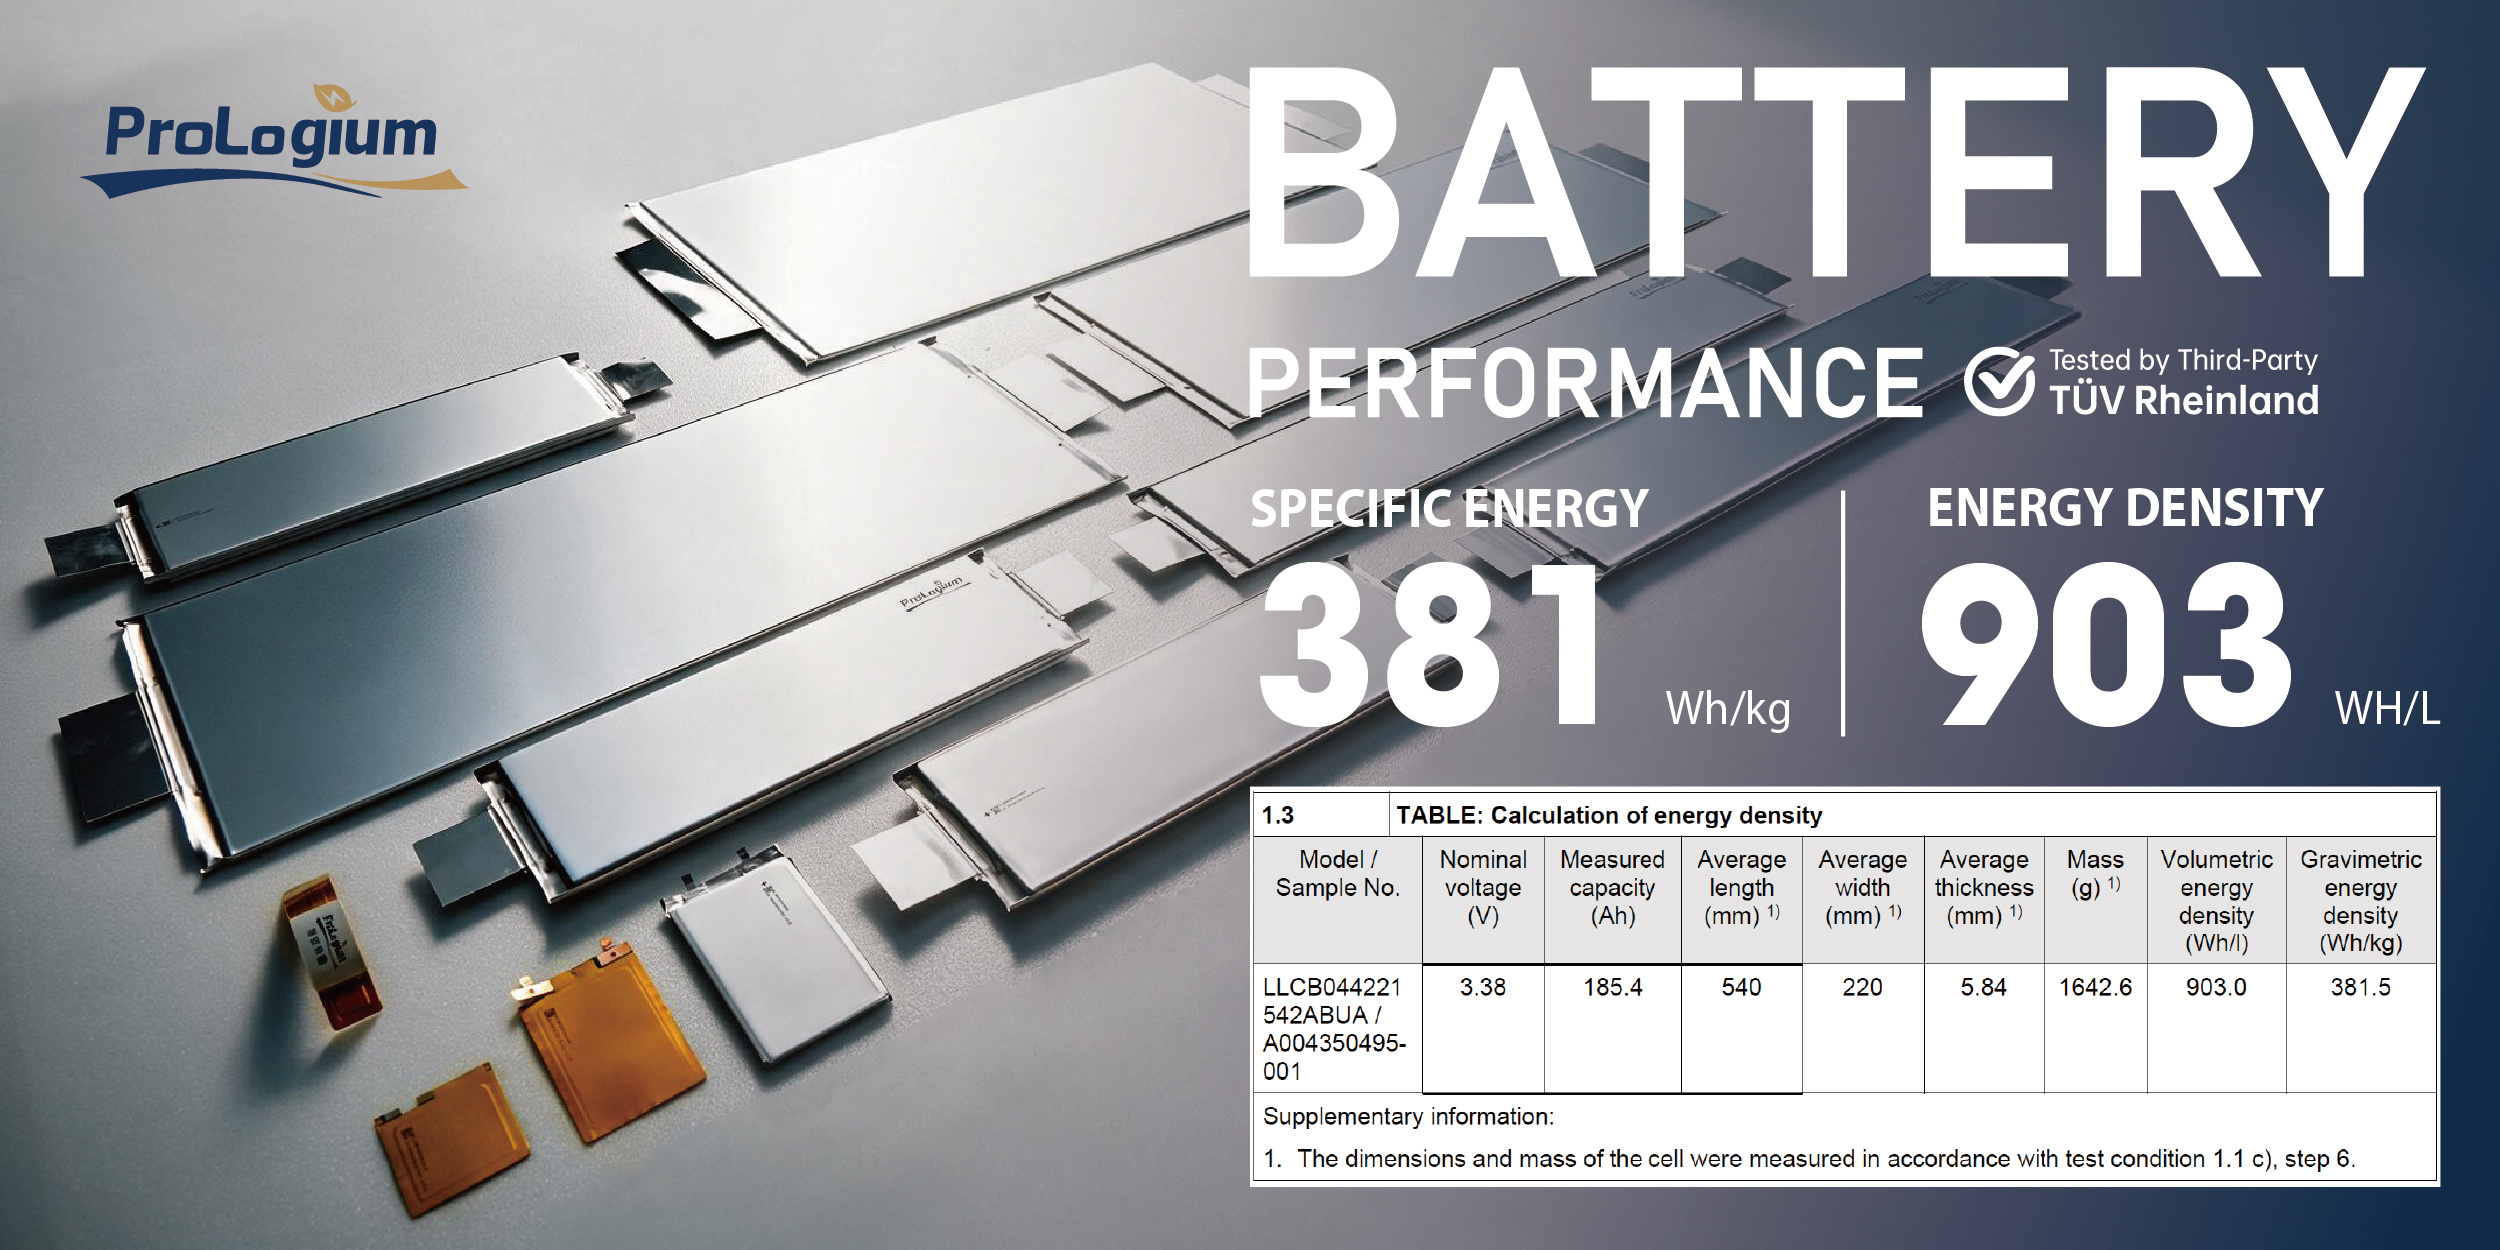
ProLogium said its Gen 3.5 Lithium Ceramic Battery (LCB) has entered mass production at its Taiwan gigafactory, marking a move from lab/pilot to scaled all-solid-state battery manufacturing. The update is supportive for commercialization momentum in high-energy-density storage technology, but specific financial impact was not disclosed.
Analysis
This reads more like a validation milestone than a near-term earnings event. The immediate market mechanism is option value: public solid-state battery names get a credibility bump, while incumbent lithium-ion suppliers only face real pressure if OEM qualification and yields prove out over the next 1-3 quarters. The bigger second-order effect is on OEM negotiating power — a believable next-gen chemistry can help automakers defend premium pricing and extend range narratives, but only if manufacturing economics stop being the bottleneck.
The likely losers, if this scales, are the content-heavy parts of today’s cell stack: separators, liquid electrolyte, and some graphite exposure. That substitution is still a 6-18 month story at minimum; a private-company production announcement alone does not change global EV pack mix or commodity demand in the next quarter. In the meantime, the most tangible beneficiaries may be the ecosystem around high-precision manufacturing and advanced ceramics, but the revenue pool is too small today to move large-cap tool names by itself.
Contrarian view: the consensus will probably overreact to the phrase "mass production" and underweight utilization, yield, and automotive qualification risk. If this is a low-volume line with weak economics, the headline is noise; the falsifier is any lack of third-party OEM validation, poor cycle-life data, or evidence that capex is rising faster than throughput. Near term, I would expect little direct impact on listed equities unless a major OEM publicly references the technology in a production program.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate listed-equity trade: treat this as a watch item for 1-3 month OEM validation and yield disclosures rather than a revenue driver today.
- Conditional long optionality in QS: buy a small Jan-2027 call spread only if a second OEM qualification or automotive production program is announced; target 2-3x on category re-rating, invalidate if yield/cycle-life metrics disappoint.
- If you want a longer-duration expression, add TM only on pullbacks and only if management reiterates a credible solid-state launch window; otherwise the stock is already too broad to pay up for this optionality.
- Do not short incumbent battery suppliers on this headline alone; the substitution risk is multi-year and likely to be offset by their own semi-solid and silicon-anode responses.
- Set an alert for any public OEM partnership news in the next 60-90 days; that is the first catalyst that could turn this from a science-story into a tradable EV supply-chain event.
More News
- Christine Lagarde, Boris Vujčić: Monetary policy statement
- Wall St set for lower open after hotter-than-expected producer inflation data
- Oil Hits $105 as Iran Shows No Signs of Backing Down
- Nasdaq invests $100 million in Kraken parent, eyeing 2027 launch of 'tokenized' stock trading
- ECB hikes rates as Iran war adds to inflation angst
- Stocks Waver Ahead of PPI, Earnings, Brent Hits $102, Trump Vows Midterm Payout to Voters