
Global Semiconductor Equipment Billings Increased 23% Year-Over-Year in Q2 2026, SEMI Reports
Source: PR Newswire
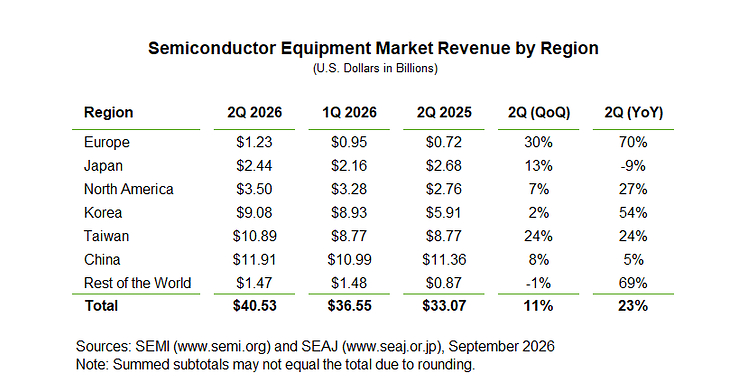
SEMI reported global semiconductor equipment billings rose 23% YoY to $40.53B in Q2 2026, with an additional 11% QoQ increase and the second straight record quarter. The rebound is attributed to sustained AI-driven capex momentum and global buildout of AI computing infrastructure, with growth spanning Asia, North America, and Europe. Overall, the data points to continued strength in semiconductor equipment demand supporting advanced manufacturing capacity.
Analysis
This print reinforces that AI capex is still translating into real spend, which is constructive for the highest-leverage picks-and-shovels in semicap: ASML, AMAT, KLAC, LRCX and the SMH basket. The immediate market mechanism is not just top-line upside; it is backlog confidence and higher utilization at the most constrained process steps, which tends to flow through with a 1-2 quarter lag into service, spares and install-base margins. That makes this more durable than a one-day headline reaction, but it also means the best equity response is often in names with operating leverage rather than the broadest beta.
The important caveat is that billings are a lagging signal disguised as a bullish catalyst. A strong print can simply confirm orders already in the pipe, so the next leg depends on whether hyperscaler capex and advanced packaging budgets keep expanding into Q4 and 2027 guidance. If AI spend pauses, the sector can de-rate quickly because these stocks are priced for multi-year growth; the first names to feel it are the most crowded leadership semicap names rather than the whole tech complex.
Second-order winners are the service-heavy and leading-edge exposure chains; relative losers are mature-node equipment vendors and any supplier dependent on non-AI logic/memory demand. The contrarian risk is that investors may be extrapolating a broad cycle when the demand is still highly concentrated in a small set of customers and technologies. If the next bookings or capex commentary from ASML/AMAT/KLAC does not confirm this pace, the trade likely works only as a short-duration momentum move, not a structural re-rating.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Key Decisions for Investors
- Add to SMH on a 2-3% pullback; use a 1-3 month horizon and target high-single-digit upside, but cut if semicap leadership loses relative strength to the Nasdaq for more than 2 weeks.
- Prefer AMAT and KLAC over the broad SOXX basket for a cleaner operating-leverage expression; the best entry is on weakness after the open, not chase-on-news, because the billings data is partly backward-looking.
- If you want convexity, buy a 3-month SMH call spread instead of outright calls to capture continuation while limiting premium bleed if AI capex cools faster than expected.
- Watch for confirmation in the next ASML/AMAT/KLAC commentary cycle; if guidance does not accelerate, take profits on any semicap momentum trade because the move may already be fully discounted.
- Avoid shorting broad tech against this signal; if you want a hedge, use a smaller hedge via QQQ puts rather than a direct semicap short, since the upside is concentrated but the downside could remain limited until capex rolls over.
More News
- AI stocks plunge. Inflation heats up. Where we're still finding opportunities
- Bending Spoons wants to revive software castoffs. Berkshire is backing the plan
- AI rapidly improving, could vastly boost U.S. GDP, Anthropic's Clark tells policymakers
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- Semiconductor market to remain solid ‘at least through next year,’ South Korea finance minister says
- Nasdaq Index: AI Selloff Deepens as Chips and CoreWeave Break