
From Bangkok to the World: Central Park Unveils "Bangkok's World Stage" as Its Next Global Ambition
Source: PR Newswire
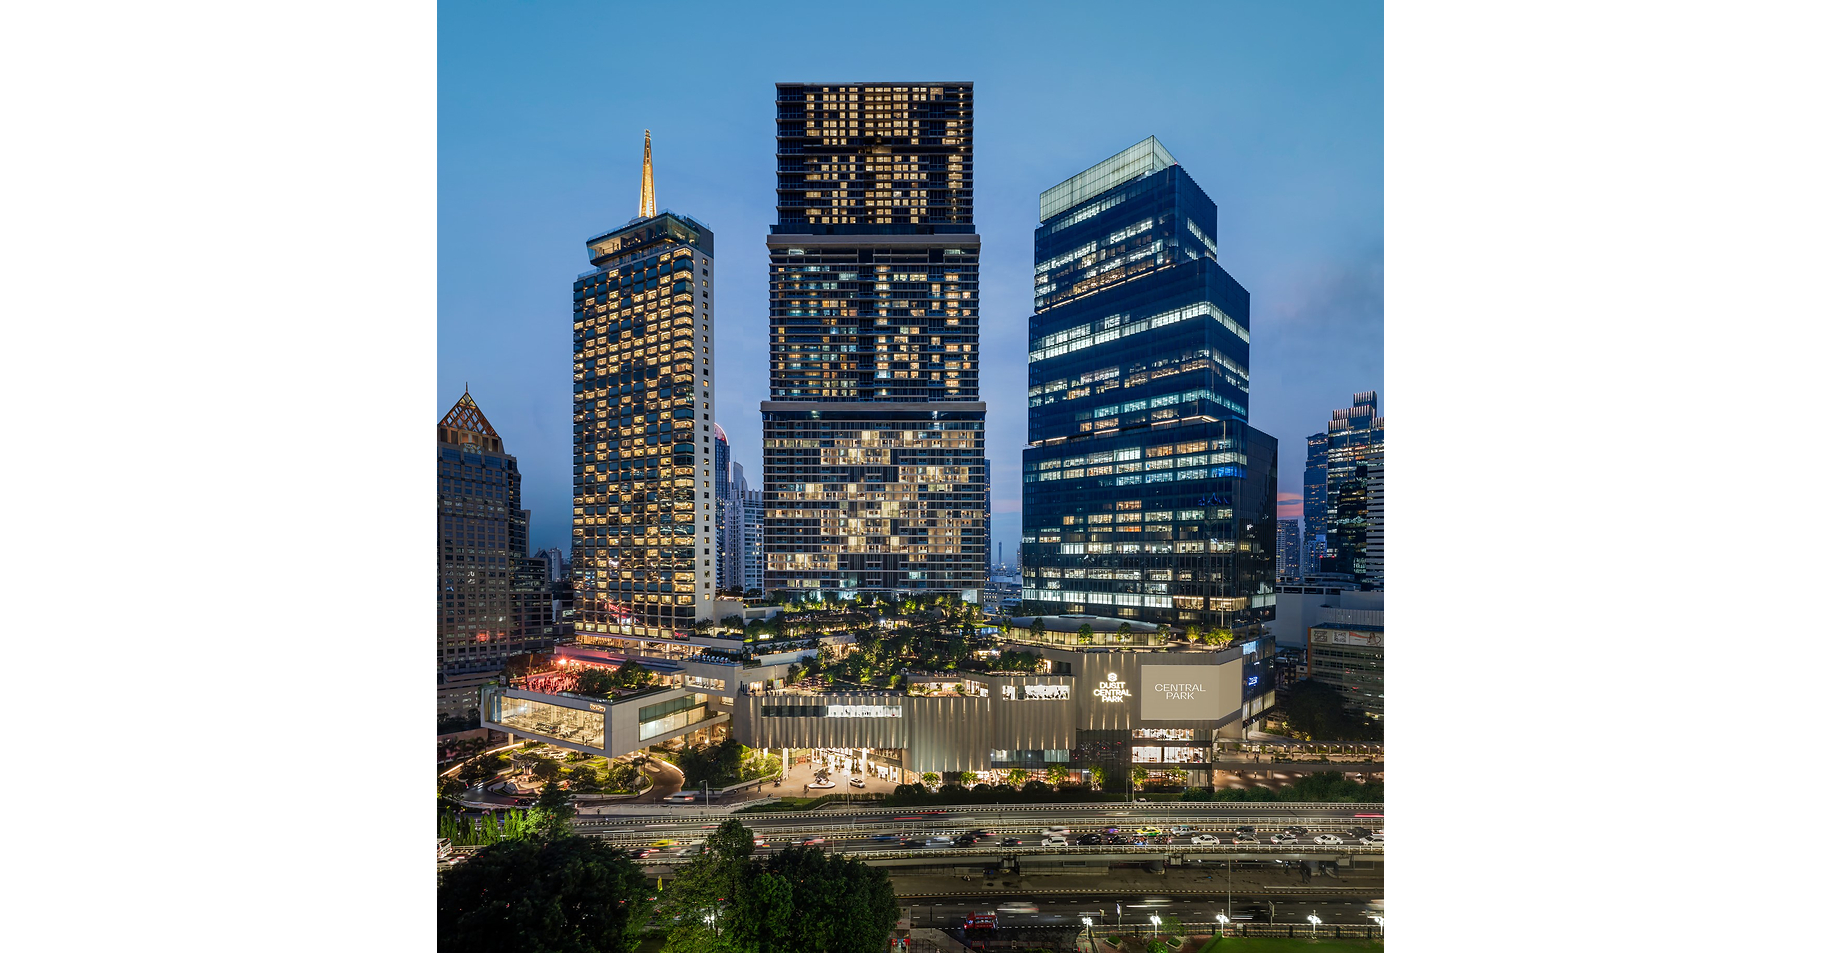
Central Park Bangkok marked its first anniversary with more than 25 million visits, including over 10 million international tourist visits, placing it among Central Pattana's top-performing destinations. The shopping centre unveiled its "Bangkok's World Stage" strategy, focused on global brand launches, cultural programming and international audience growth. The retail asset is part of the broader Dusit Central Park mixed-use development spanning retail, offices, hotel, residences and more than seven rai of green space.
Analysis
The relevant investable signal is not the venue-level traffic claim but the potential proof point for premium Bangkok mixed-use absorption: retail footfall can support lease-rate escalation, office/hotel cross-selling, and residential branding only if tourist spend converts into tenant sales productivity. Central Pattana is not directly accessible through a widely traded U.S. ticker; investors seeking Thai consumption exposure should monitor CPN.BK, while CPNREIT.BK is a more direct read-through on retail-property cash flows. The press release provides no tenant-sales, occupancy, lease-reversion, or EBITDA contribution data, so it does not yet justify an earnings revision.
Near term, this is largely a sentiment and tourism-confidence datapoint rather than a catalyst. Over the next 1-3 months, the critical verification points are Thai international-arrival trends, luxury and F&B tenant openings, and evidence that spending per visit—not simply visits—is rising; high tourist mix can lift turnover rents but can also make the asset more exposed to Chinese outbound travel volatility and baht appreciation. A stronger flagship retail node may marginally pressure older central-Bangkok malls and discretionary merchants without differentiated concepts, while benefiting airport, hotel, restaurant, and premium-brand ecosystems.
Over 6-18 months, the more consequential effect is whether the integrated development creates a self-reinforcing district premium across office, hotel, and residential components. If it does, CPN could earn a higher multiple for development execution and recurring-income mix; if not, expensive experiential programming becomes an operating-cost drag with limited incremental rent capture. Consensus may overvalue headline visitor volume: 25 million annual visits implies substantial local repeat traffic, making incremental tourist spending and tenant productivity—not global-brand announcements—the key marginal variables.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No immediate trade on the release. Create a CPN.BK watch item for the next results cycle: consider a long only if retail occupancy remains above 95%, same-store tenant sales/traffic demonstrate positive conversion, and management discloses positive lease reversion or turnover-rent uplift attributable to the project.
- For a 3-6 month Thailand-consumption expression, prefer a conditional long CPN.BK versus a short Thailand broad-market proxy only after tourism-arrival data and CPN retail guidance improve together; this isolates premium retail/mixed-use execution from broader Thai macro exposure. Falsify on weaker tourist arrivals for two consecutive months or a material occupancy/lease-spread miss.
- Monitor AOT.BK and CENTEL.BK as second-order beneficiaries of sustained high-spending international arrivals rather than treating mall traffic as a standalone tourism signal. AOT offers cleaner passenger-volume sensitivity; CENTEL adds hotel/F&B operating leverage but carries greater margin risk from wage and food inflation.
- Avoid extrapolating the visitor figure into a structural Thai property rerating until disclosed sales productivity supports it. A rising baht, a setback in Chinese outbound travel, or tenant incentives needed to maintain occupancy would challenge the thesis within 1-3 quarters.
More News
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
- French police use tear gas and water cannons after some protests turn violent as shopkeepers board up storefronts across Paris
- IMDELLTRA® IN COMBINATION WITH IMFINZI® REDUCED RISK OF DEATH BY AN UNPRECEDENTED 58% IN FIRST-LINE EXTENSIVE STAGE SMALL CELL LUNG CANCER
- France Faces New Protests After Week of Violence
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect