
AI Industry Stands to Lose in Midterm Elections After Aligning With Trump
Source: Bloomberg
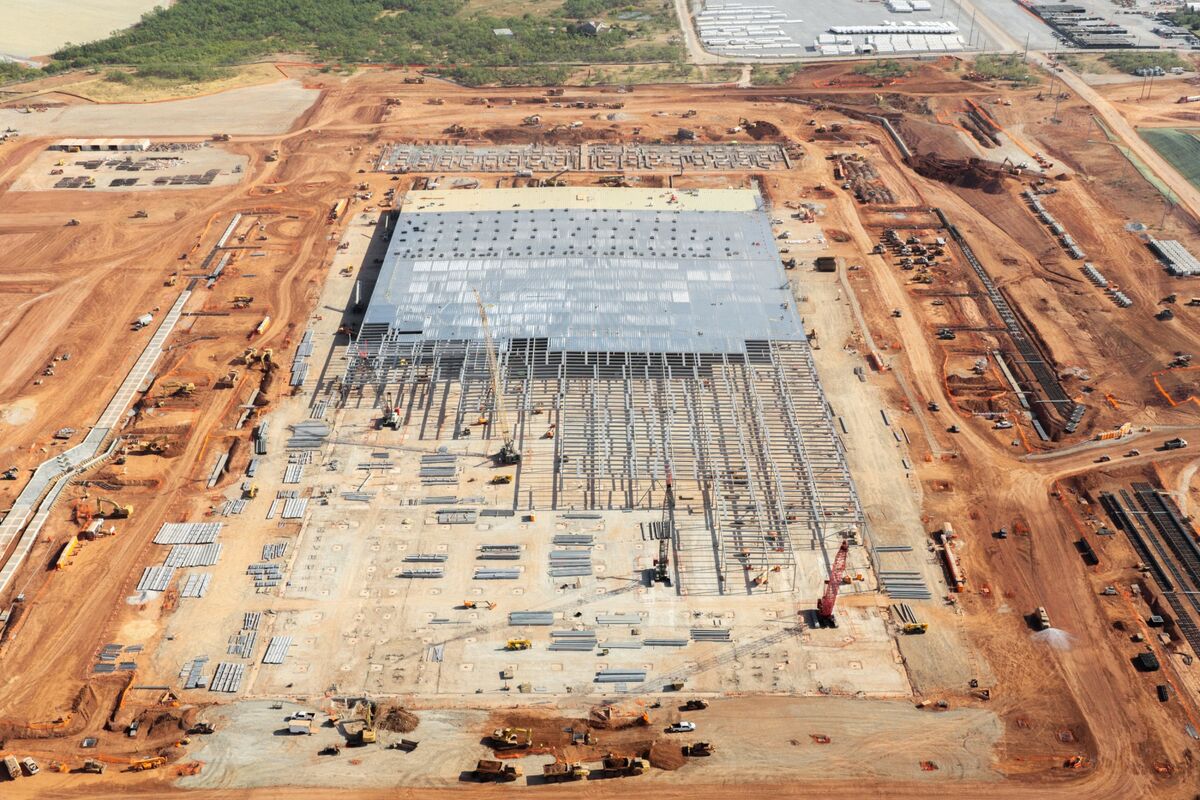
Meta disclosed that political backlash, trade disputes, and potential new taxes or regulations could raise its capital expenditures and operating costs as it prepares to seek a record $98 billion share sale. The filing points to possible strain in the relationship between Silicon Valley and the White House, but reports no policy changes or realized financial impact.
Analysis
The market-relevant risk is not political rhetoric itself, but whether it converts into higher marginal costs or slows AI monetization. If policy friction raises data-center, power, compliance, or content-moderation costs, Meta could face a longer payback period on AI investment; that would pressure returns on incremental capital before it necessarily affects near-term ad demand. Competitors with cloud businesses may be better positioned to spread infrastructure costs across external customers, while Meta’s exposure is more dependent on improving its own products and ad economics. The risk is sector-wide, however, so a simple long-cloud/short-Meta trade may not isolate it cleanly.
The filing language is a risk disclosure, not evidence that new taxes or rules are imminent. Political backlash could also constrain smaller AI developers more than scaled platforms, potentially strengthening Meta’s relative position. The claimed $98 billion share-sale reference needs verification: confirm the filing, transaction type, and whether it implies dilution before treating it as a financing signal.
Near term, sentiment may weigh on AI-linked multiples, but the 1–3 month catalyst is whether Meta changes capex, expense, or monetization guidance and whether policy proposals become concrete. Over 6–18 months, watch realized AI-related ad efficiency and infrastructure returns. The thesis weakens if guidance shows costs contained and monetization improving; it strengthens if policy moves translate into measurable expense increases or a longer investment payback.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Ticker Sentiment
Key Decisions for Investors
- Do not short META solely on the political-risk language; treat it as a modest risk premium rather than evidence of near-term earnings deterioration.
- Verify the purported $98 billion share-sale reference against the underlying filing before trading. If it is an actual equity issuance, reassess dilution and financing implications; if not, discard that angle.
- Over the next 1–3 months, monitor capex and operating-expense guidance, AI-driven ad monetization commentary, and concrete tax, data-use, or permitting proposals. A cost increase without corresponding monetization progress would support reducing exposure.
- For existing META exposure, consider a limited downside hedge only if the stock reprices on policy or capex news; thesis falsifiers are stable cost guidance, improving monetization metrics, or policy proposals failing to advance.
More News
- AI build-out hits snag as Google and Microsoft put off raising capex forecasts
- Amazon AWS revenue grows 39%, leading to wider margin
- How Todd Gordon is trading Meta as the stock market rotates out of growth and into value names
- Jefferies reiterates Buy on AMD stock, sees data center upside
- Meta loses appeals against interim measures imposed by French regulators
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn