
Novelis Produces First Coil at Greenfield Aluminum Rolling and Recycling Plant in Alabama
Source: PR Newswire
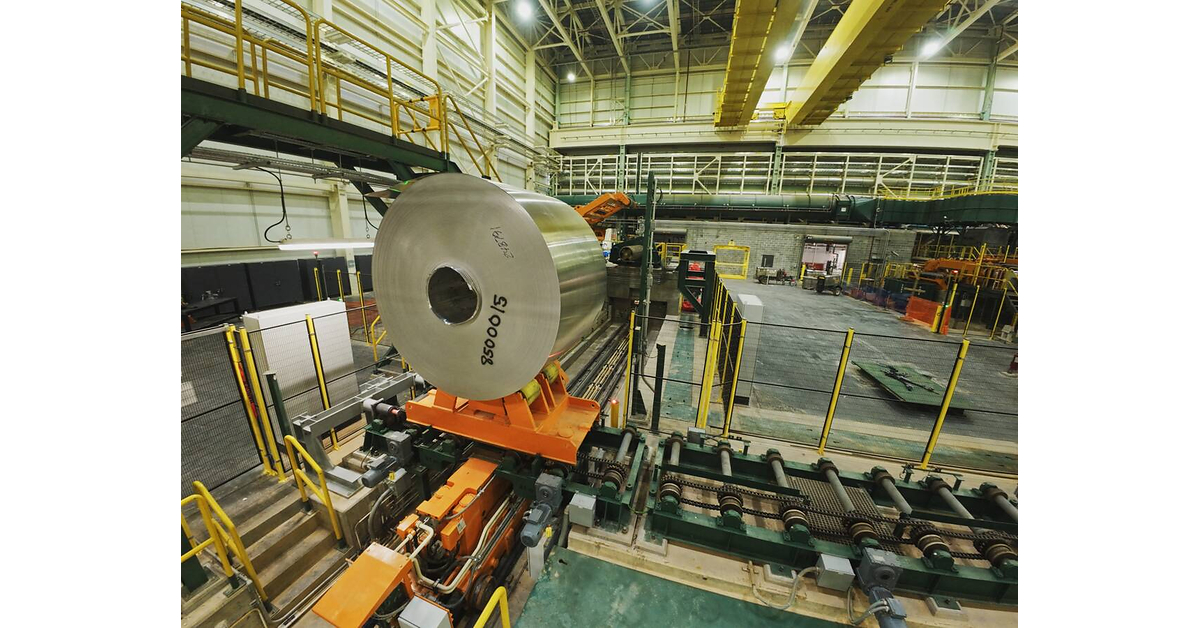
Novelis produced the first coil on the cold mill at its $5 billion Bay Minette, Alabama, aluminum rolling and recycling plant, advancing commissioning. The facility is expected to add 600 kilotonnes of annual rolled-aluminum capacity and process more than 15 billion used beverage cans annually when fully operational. Customer qualification and commercial shipments are on track to begin in Q2 2027; the plant is expected to create up to 1,000 jobs.
Analysis
The key investment question is not whether the plant can make a coil, but whether it can clear customer qualification and ramp yields without disrupting Novelis’ existing production. Until shipments begin, this is execution evidence—not incremental earnings. In the 1–3 month window, watch commissioning milestones and customer qualification; the meaningful operating catalyst is commercial shipment timing and ramp quality into Q2 2027. A delay or slow yield ramp would defer returns on a large project and could raise the risk that expected capacity arrives later than customers’ procurement plans assume.
If the capacity is absorbed, the structural effect is more U.S. rolled-product availability and less dependence on imports. That may pressure conversion economics for competing North American rollers, including Constellium, while giving beverage-can and automotive customers another qualified source. The effect is product-specific: qualification and mix matter, so nameplate capacity alone does not establish near-term displacement. The recycling center also increases demand for used beverage cans and other suitable scrap; local scrap collectors may benefit, while existing recyclers could face tighter feedstock competition. This is more likely to affect scrap spreads than the underlying aluminum price.
The contrarian point: a first-coil milestone is easy to celebrate but says little about sustained throughput, saleable yield, or customer acceptance. No immediate directional trade is warranted on this release alone. Over 6–18 months, successful ramp could strengthen Novelis’ competitive position, but the parent Hindalco’s consolidated benefit depends on utilization, product mix, and project economics that are not disclosed here.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No event-driven position on the milestone alone. Treat it as a modest execution de-risking signal, not evidence of revenue or margin uplift before customer qualification and commercial shipments.
- Set an alert for updates on qualification, shipment timing, utilization, and saleable yield. A slip beyond the stated Q2 2027 start or evidence of a slow ramp would falsify the near-term de-risking thesis.
- Monitor North American rolled-product conversion economics and scrap spreads. Sustained weakening in competing rollers’ pricing alongside tighter regional scrap availability would support the oversupply/ feedstock-competition thesis; absent those signals, avoid assuming broad sector earnings pressure.
- For a 6–18 month relative-value watch, compare Novelis/Hindalco execution updates with Constellium’s relevant product-market commentary. Consider a relative position only after confirming comparable product exposure and evidence that Bay Minette is winning qualified customer volume.
More News
- Tanker hit by multiple projectiles off north coast of Qatar, UKMTO says
- Elon Musk blames Indian 'oligarchs' for stalling Starlink launch
- High Court coal decision, Firmus IPO, diesel prices
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Yemeni government forces claim 1,860 Houthis ‘neutralised’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense vs Hebbia vs AllMind: Choose by Workflow
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace