
CRRC presenta su cartera de energía eólica en WindEnergy Hamburg
Source: PR Newswire
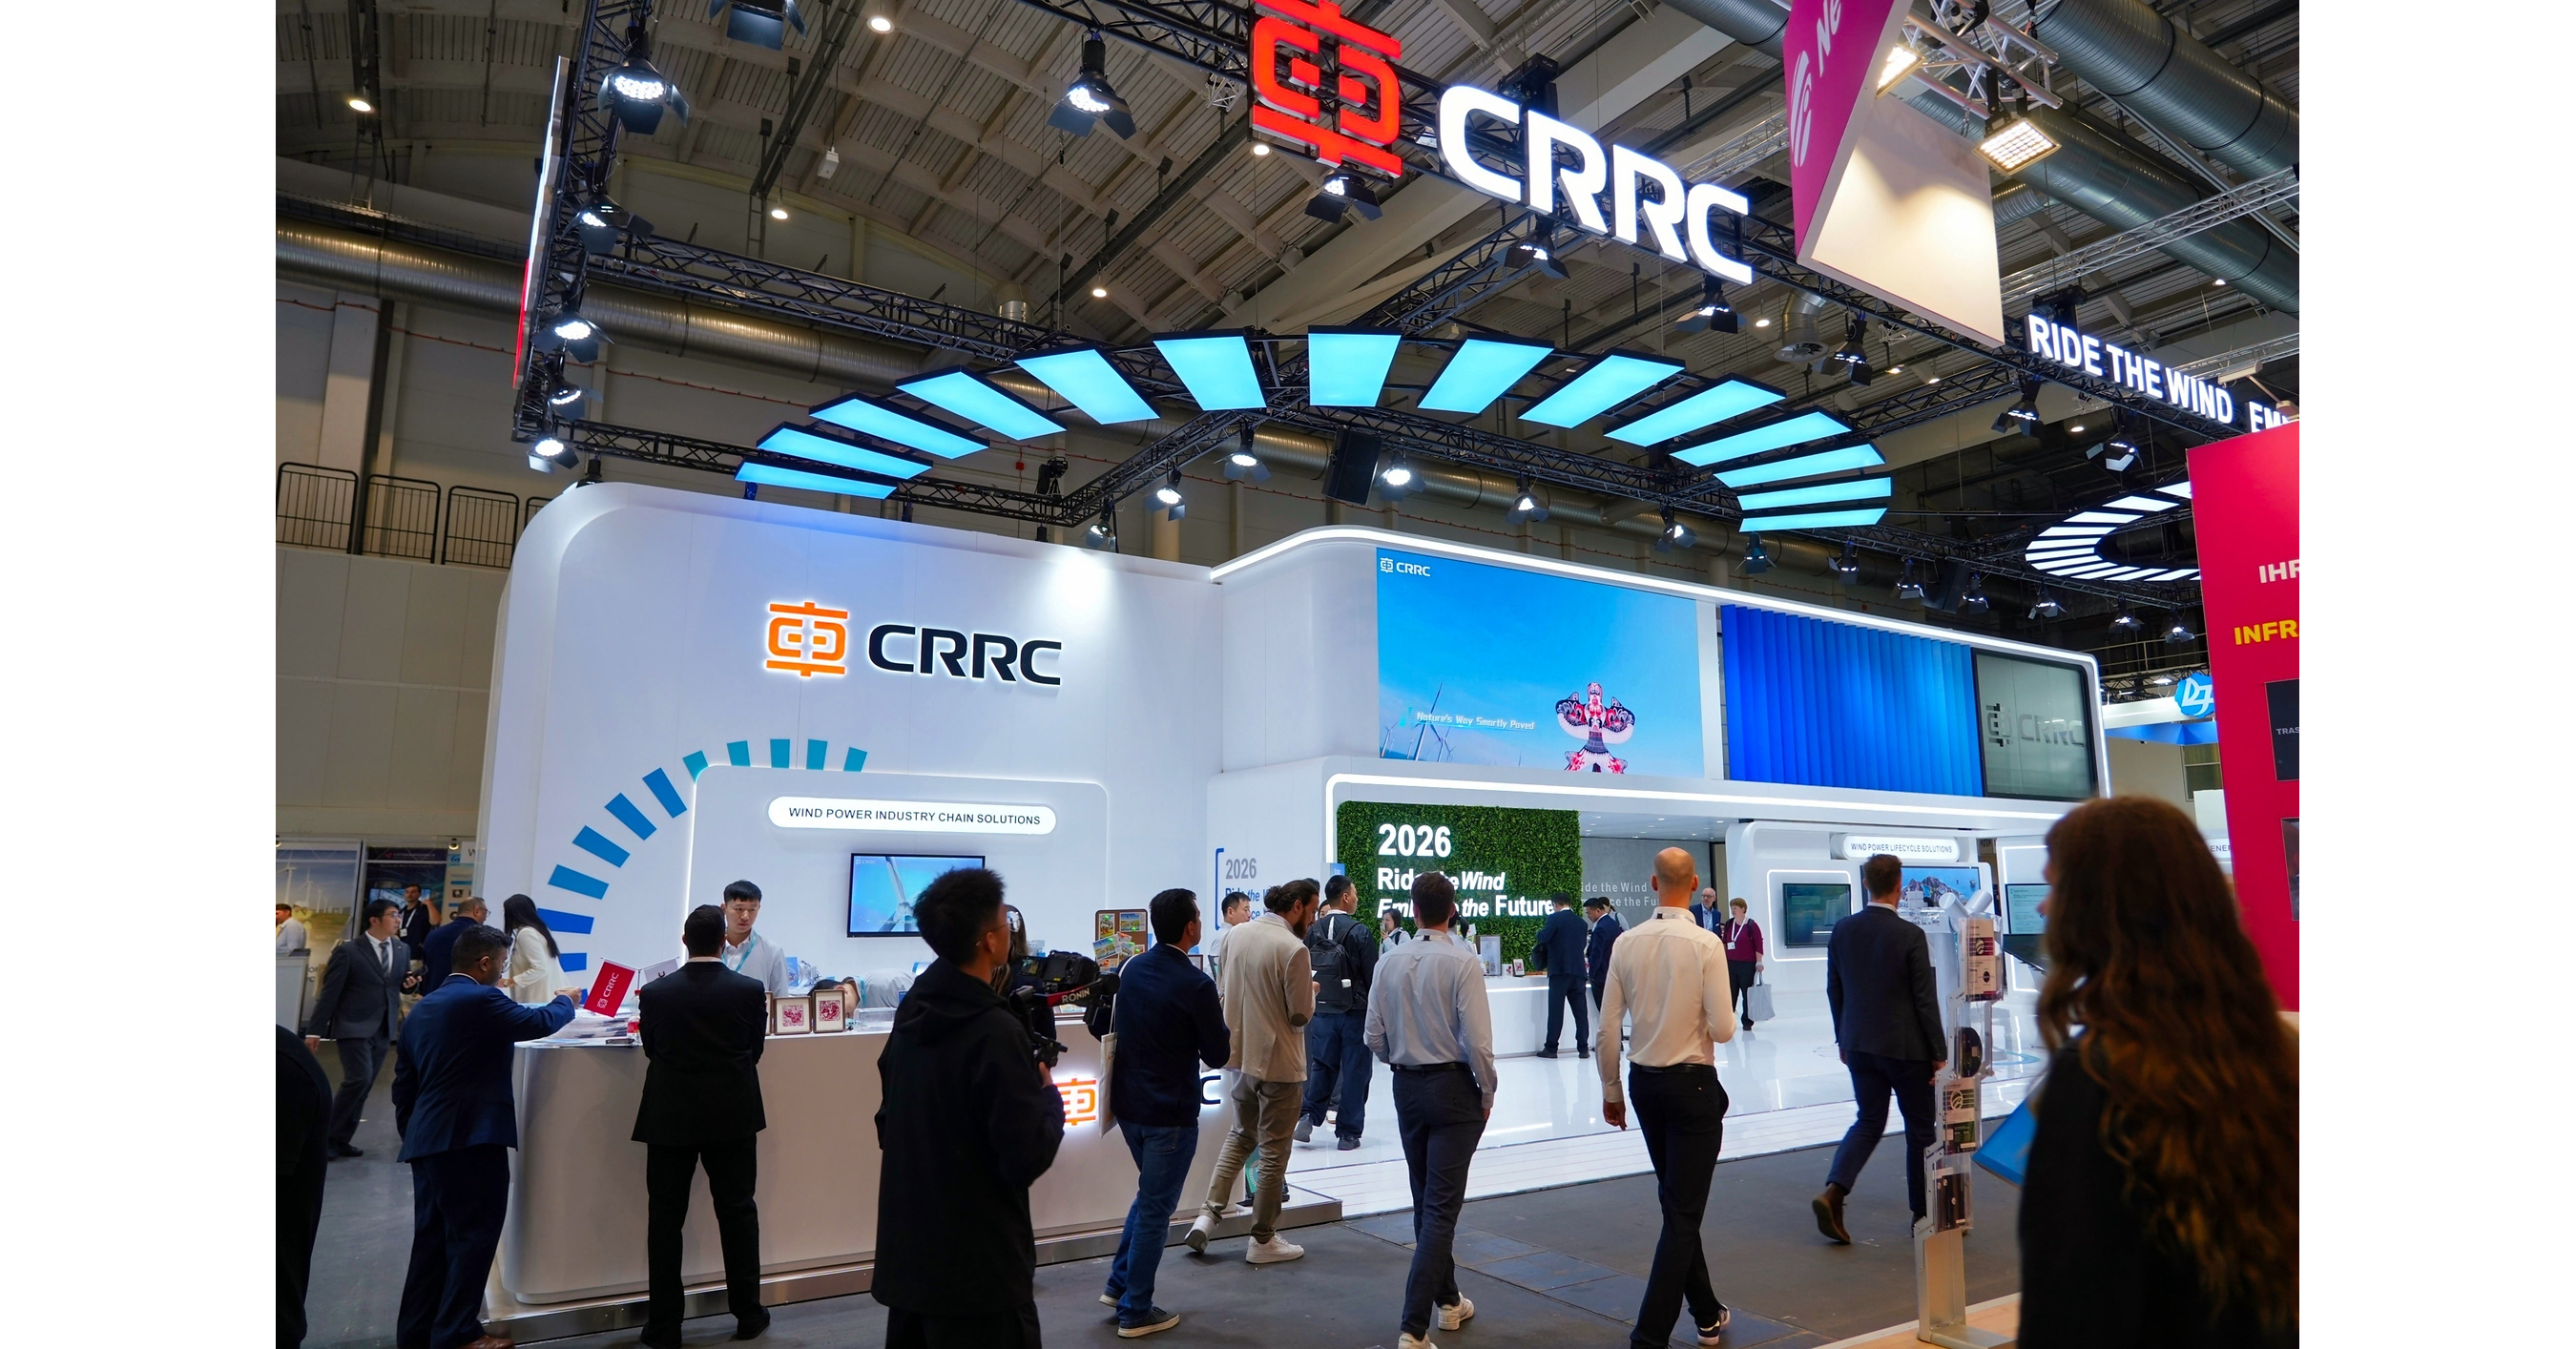
CRRC showcased its full wind-energy portfolio at WindEnergy Hamburg 2026 and received TÜV SÜD type certification for its 7.15MW D195 wind turbine. The company expanded its technical partnership with X1 Wind for joint R&D, while highlighting a global wind manufacturing and service network spanning more than 20 plants and nearly 400 wind farms. CRRC’s wind-turbine range extends from 1.5MW to 12MW onshore and 8MW to 20MW offshore, supporting its push for further international renewable-energy market expansion.
Analysis
The investable signal is potential export-driven price competition, not the certification itself. A Chinese vertically integrated entrant can use lower component costs and bundled EPC/O&M offers to compress turbine ASPs in contested emerging-market tenders before it materially penetrates Europe; this is most negative for OEMs with weak service mix and fixed-cost absorption, while blade, gearbox and tower suppliers face greater localization pressure. European incumbents retain an installed-base, financing and bankability advantage, so any earnings impact is likely to lag tender wins by 12-24 months.
For the next 1-3 months, watch whether the company converts marketing activity into named European orders, local manufacturing commitments, or developer financing partnerships. A certification alone does not establish insurer, lender, grid-code, cybersecurity, spare-parts or warranty acceptance; those are the gating items for higher-margin EU projects. The more immediate read-through is likely in India, Southeast Asia, Latin America and Central Asia, where procurement is more price-sensitive and local-content rules can be negotiated.
Consensus may overstate near-term disruption to Vestas (VWS.CO) and Siemens Energy (ENR.DE). EU foreign-subsidy scrutiny, security restrictions and developers' aversion to lifetime warranty risk can keep Chinese participation confined to lower-value equipment packages; conversely, a successful localized European reference project would force a reassessment of OEM terminal margins and valuation multiples. The key falsifier for the bearish-incumbent thesis is continued European tender pricing discipline alongside no disclosed CRRC order backlog through the next two tender cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate directional trade on the announcement: treat 1766.HK / 601766.SS as a watch item until a named non-China order, disclosed contract value and margin/working-capital terms are available.
- Set a 1-3 month alert for European or Indian turbine awards involving CRRC. If it wins a financed project at a visibly discounted bid, initiate a 3-6 month relative-value short in the most exposed pure-play OEM versus VWS.CO; avoid using ENR.DE as the short leg because its grid-equipment earnings can offset wind-turbine pressure.
- Maintain preference for VWS.CO over smaller/less service-heavy wind OEM exposure on a 6-18 month horizon: recurring service revenue and customer bankability should cushion equipment-price pressure. Reassess if order intake shows sustained price-per-MW declines or service-attachment rates weaken.
- For European transmission exposure, retain a separate long bias toward NKT.CO or Prysmian (PRY.MI) only if offshore project awards accelerate; turbine competition can lower generation-equipment costs and improve project economics, but this article alone is insufficient to trigger entry.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Latest Oil Market News and Analysis for Sept. 23
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings