
AliExpress Brand+ s'impose comme une rampe de lancement mondiale pour les innovations de pointe à l'IFA 2026
Source: PR Newswire
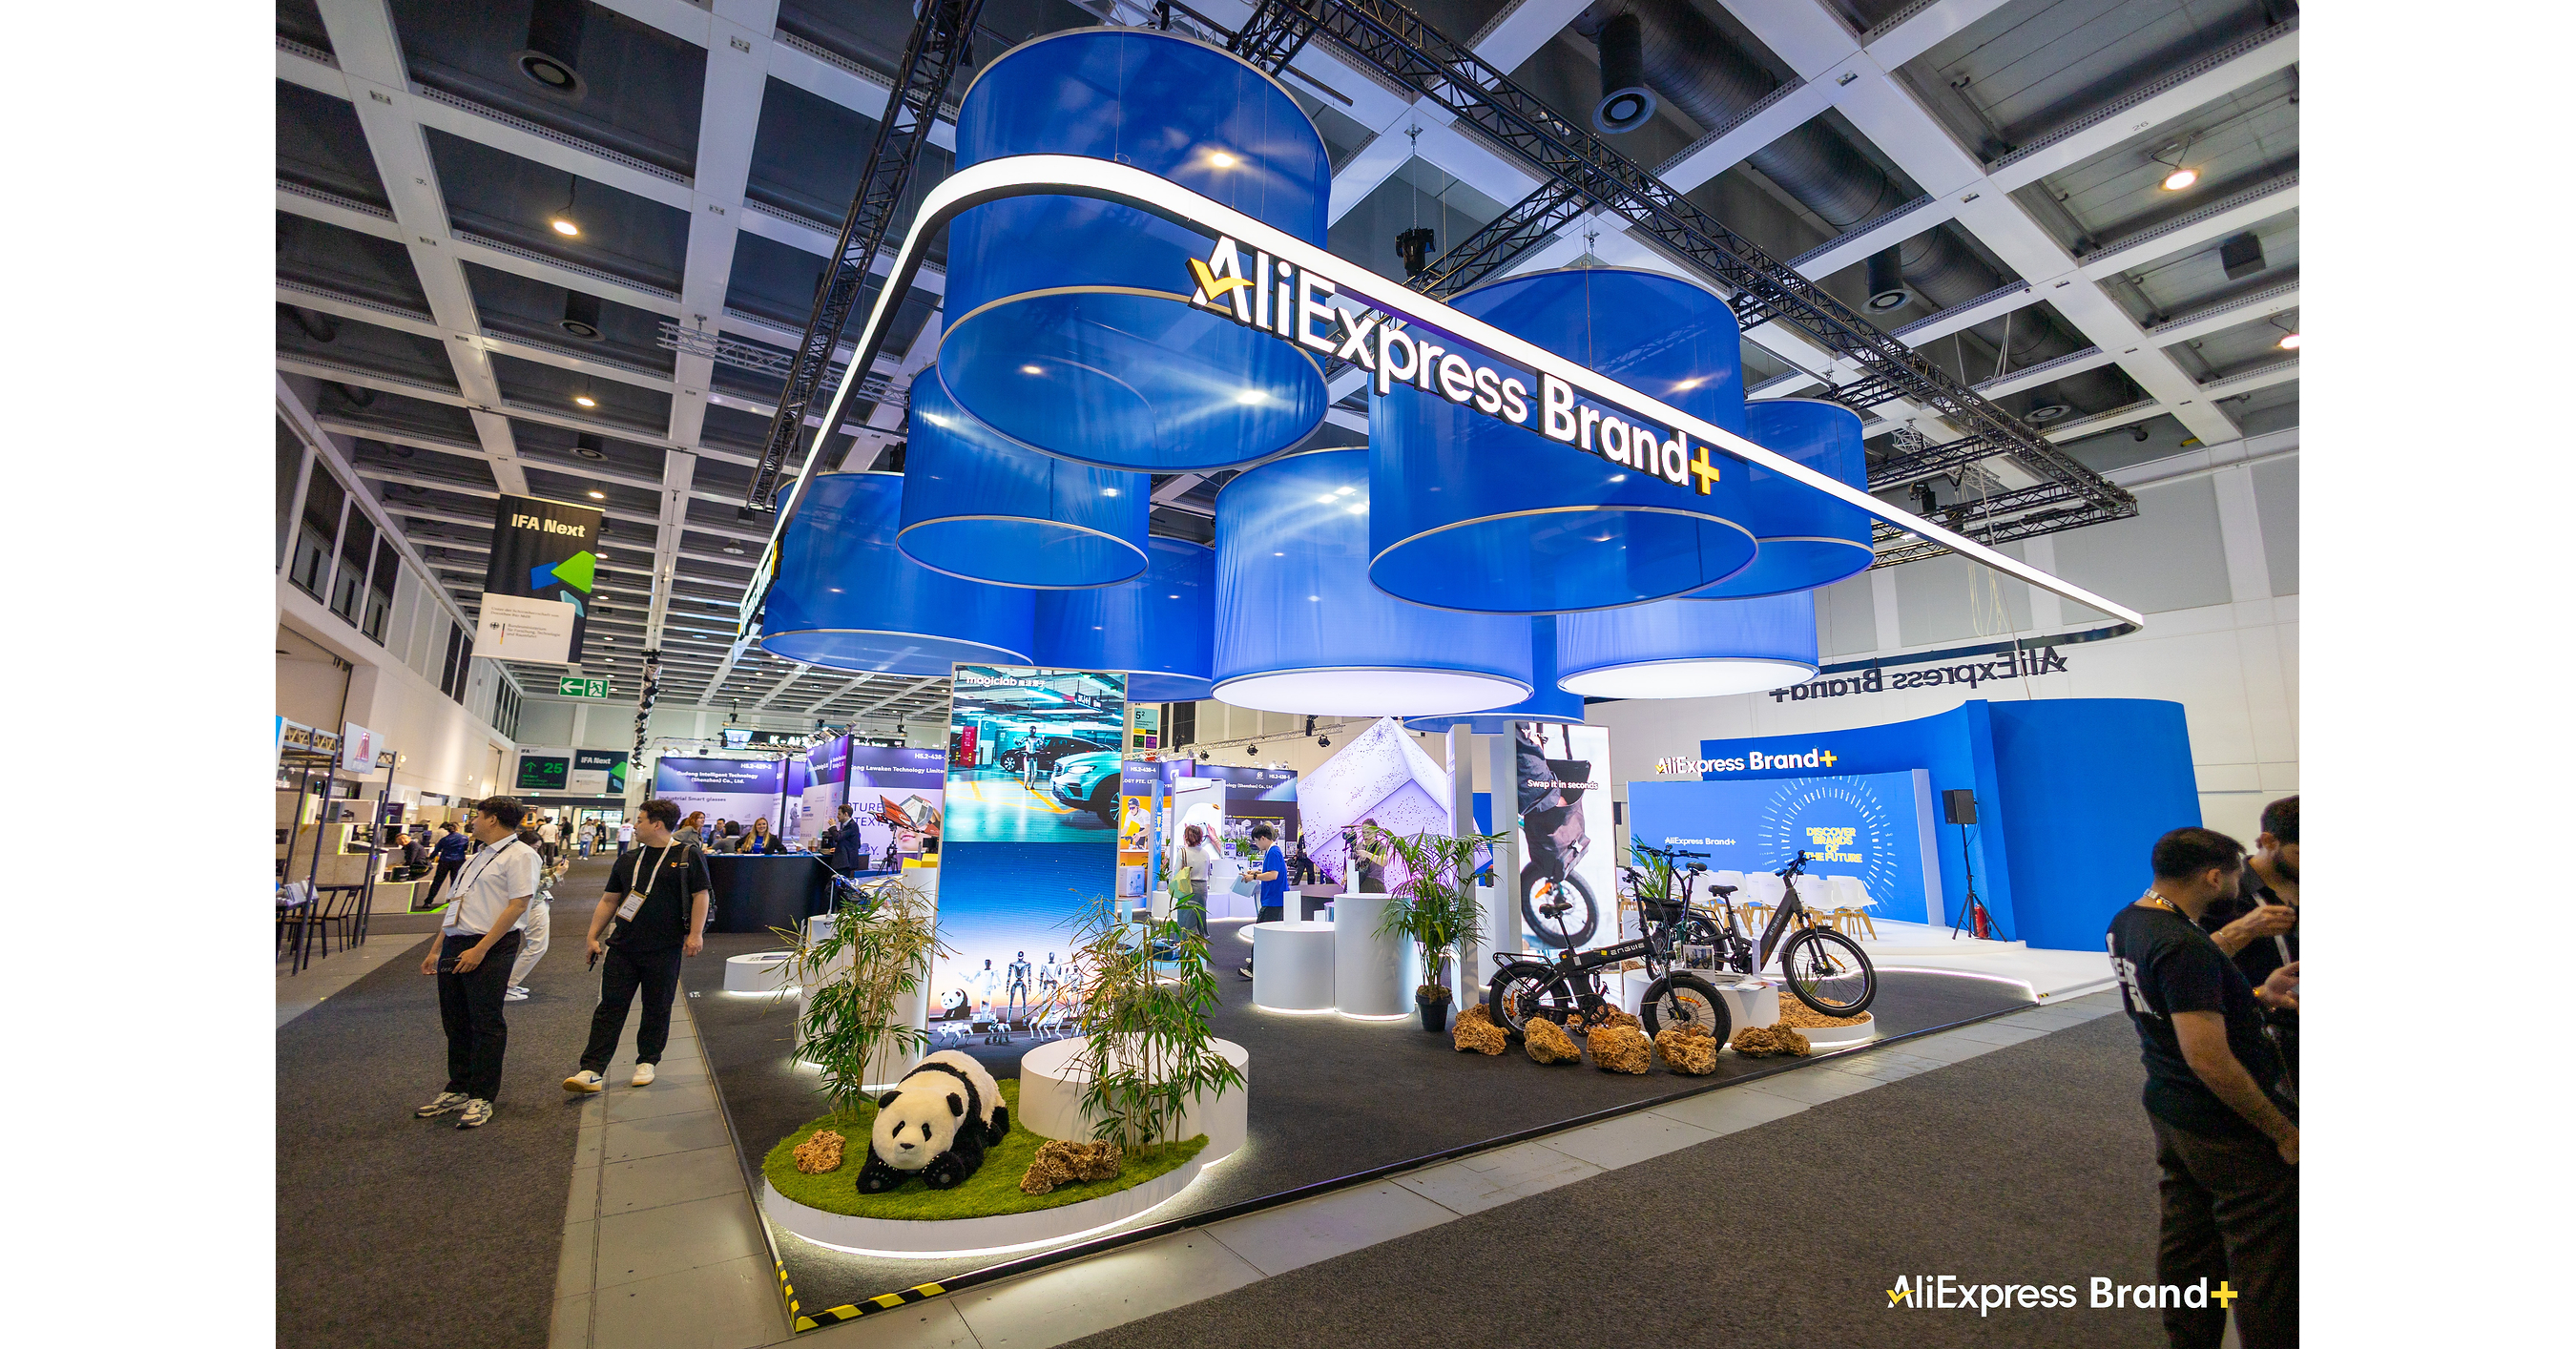
AliExpress Brand+ positions IFA 2026 as a global showcase for consumer technology and AI hardware, citing participation by 1,500+ major brands. The initiative reached ~40% penetration of GMV from Brand+ brands during the mid-year mega-sale, while orders from local warehouses in Spain/France/Poland accounted for over 50% of total revenue. The article frames a supportive demand shift toward premium “tech that integrates into daily life,” alongside investments in rapid delivery, simplified returns, and an additional German warehouse under construction.
Analysis
The investable signal here is not the product demo set; it is Alibaba using local fulfillment plus branded assortment to push cross-border commerce up the value chain. That is structurally better for BABA than pure volume growth because it can lift conversion, reduce refund friction, and support a higher take rate if the user experience becomes more Amazon-like in Europe. The catch is that this strategy also front-loads logistics and service costs, so near-term margin optics may lag the GMV narrative even if top-line momentum improves.
Competitive pressure lands most directly on incumbent EU marketplaces and electronics retailers that compete on speed, trust, and after-sales service rather than on price alone. The second-order effect is that smaller consumer-tech brands get a cheaper route to pan-European distribution, which can widen the long tail and intensify category fragmentation. For AMD, the reference is too incremental to matter financially on its own; any upside is indirect through mini-PC and edge-AI channel checks, not a revenue driver.
The key risk is regulatory or operational: product compliance, customs/VAT scrutiny, or a holiday-season service miss would quickly reverse the thesis because the model depends on trust, not just discounting. The market may be overestimating the immediacy of earnings impact, but underestimating the durability of a local-warehouse moat if BABA can keep delivery times and returns competitive over the next 1-3 quarters. Falsify the BABA thesis if international commerce growth does not inflect while fulfillment costs rise, or if EU enforcement makes cross-border economics less attractive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Long BABA on pullbacks for a 1-3 month trade: thesis is improving international mix and logistics moat, with upside if the next quarter confirms higher branded GMV and stable fulfillment costs; cut if international margin fails to improve.
- Optional expression: buy BABA call spreads 3-6 months out to capture multiple expansion from execution confirmation while capping downside if Europe remains mostly a PR story.
- Do not add AMD on this headline; treat the AMD mention as de minimis channel color unless independent PC/OEM data shows broader AI-PC design wins over the next 1-2 quarters.
- If BABA rallies sharply on this PR without follow-through in reported take rate or Europe revenue, fade strength via call overwrites or a reduced long rather than chasing the narrative.
- Watch for EU regulatory or customs headlines as the main falsifier; any tightening on platform compliance or import friction should trigger a reassessment of the BABA long.
More News
- Alibaba Backs Chinese Robovan Maker in $400 Million Fundraising
- AI stocks bounce back after bruising selloff, CoreWeave gets Goldman upgrade
- Why this bull market is unlike any we've seen before
- AI chip startup Tenstorrent more than doubles its valuation to $6.2 billion in funding round
- TD Cowen reiterates AMD stock buy rating on AI workload strength
- Cathie Wood’s ARK sells Palantir and Shopify stock, buys CoreWeave
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Search Earnings Call Transcripts With AI
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI