
BayPort Credit Union Celebrates Grand Reopening of Its First-Ever Branch in Newport News
Source: PR Newswire
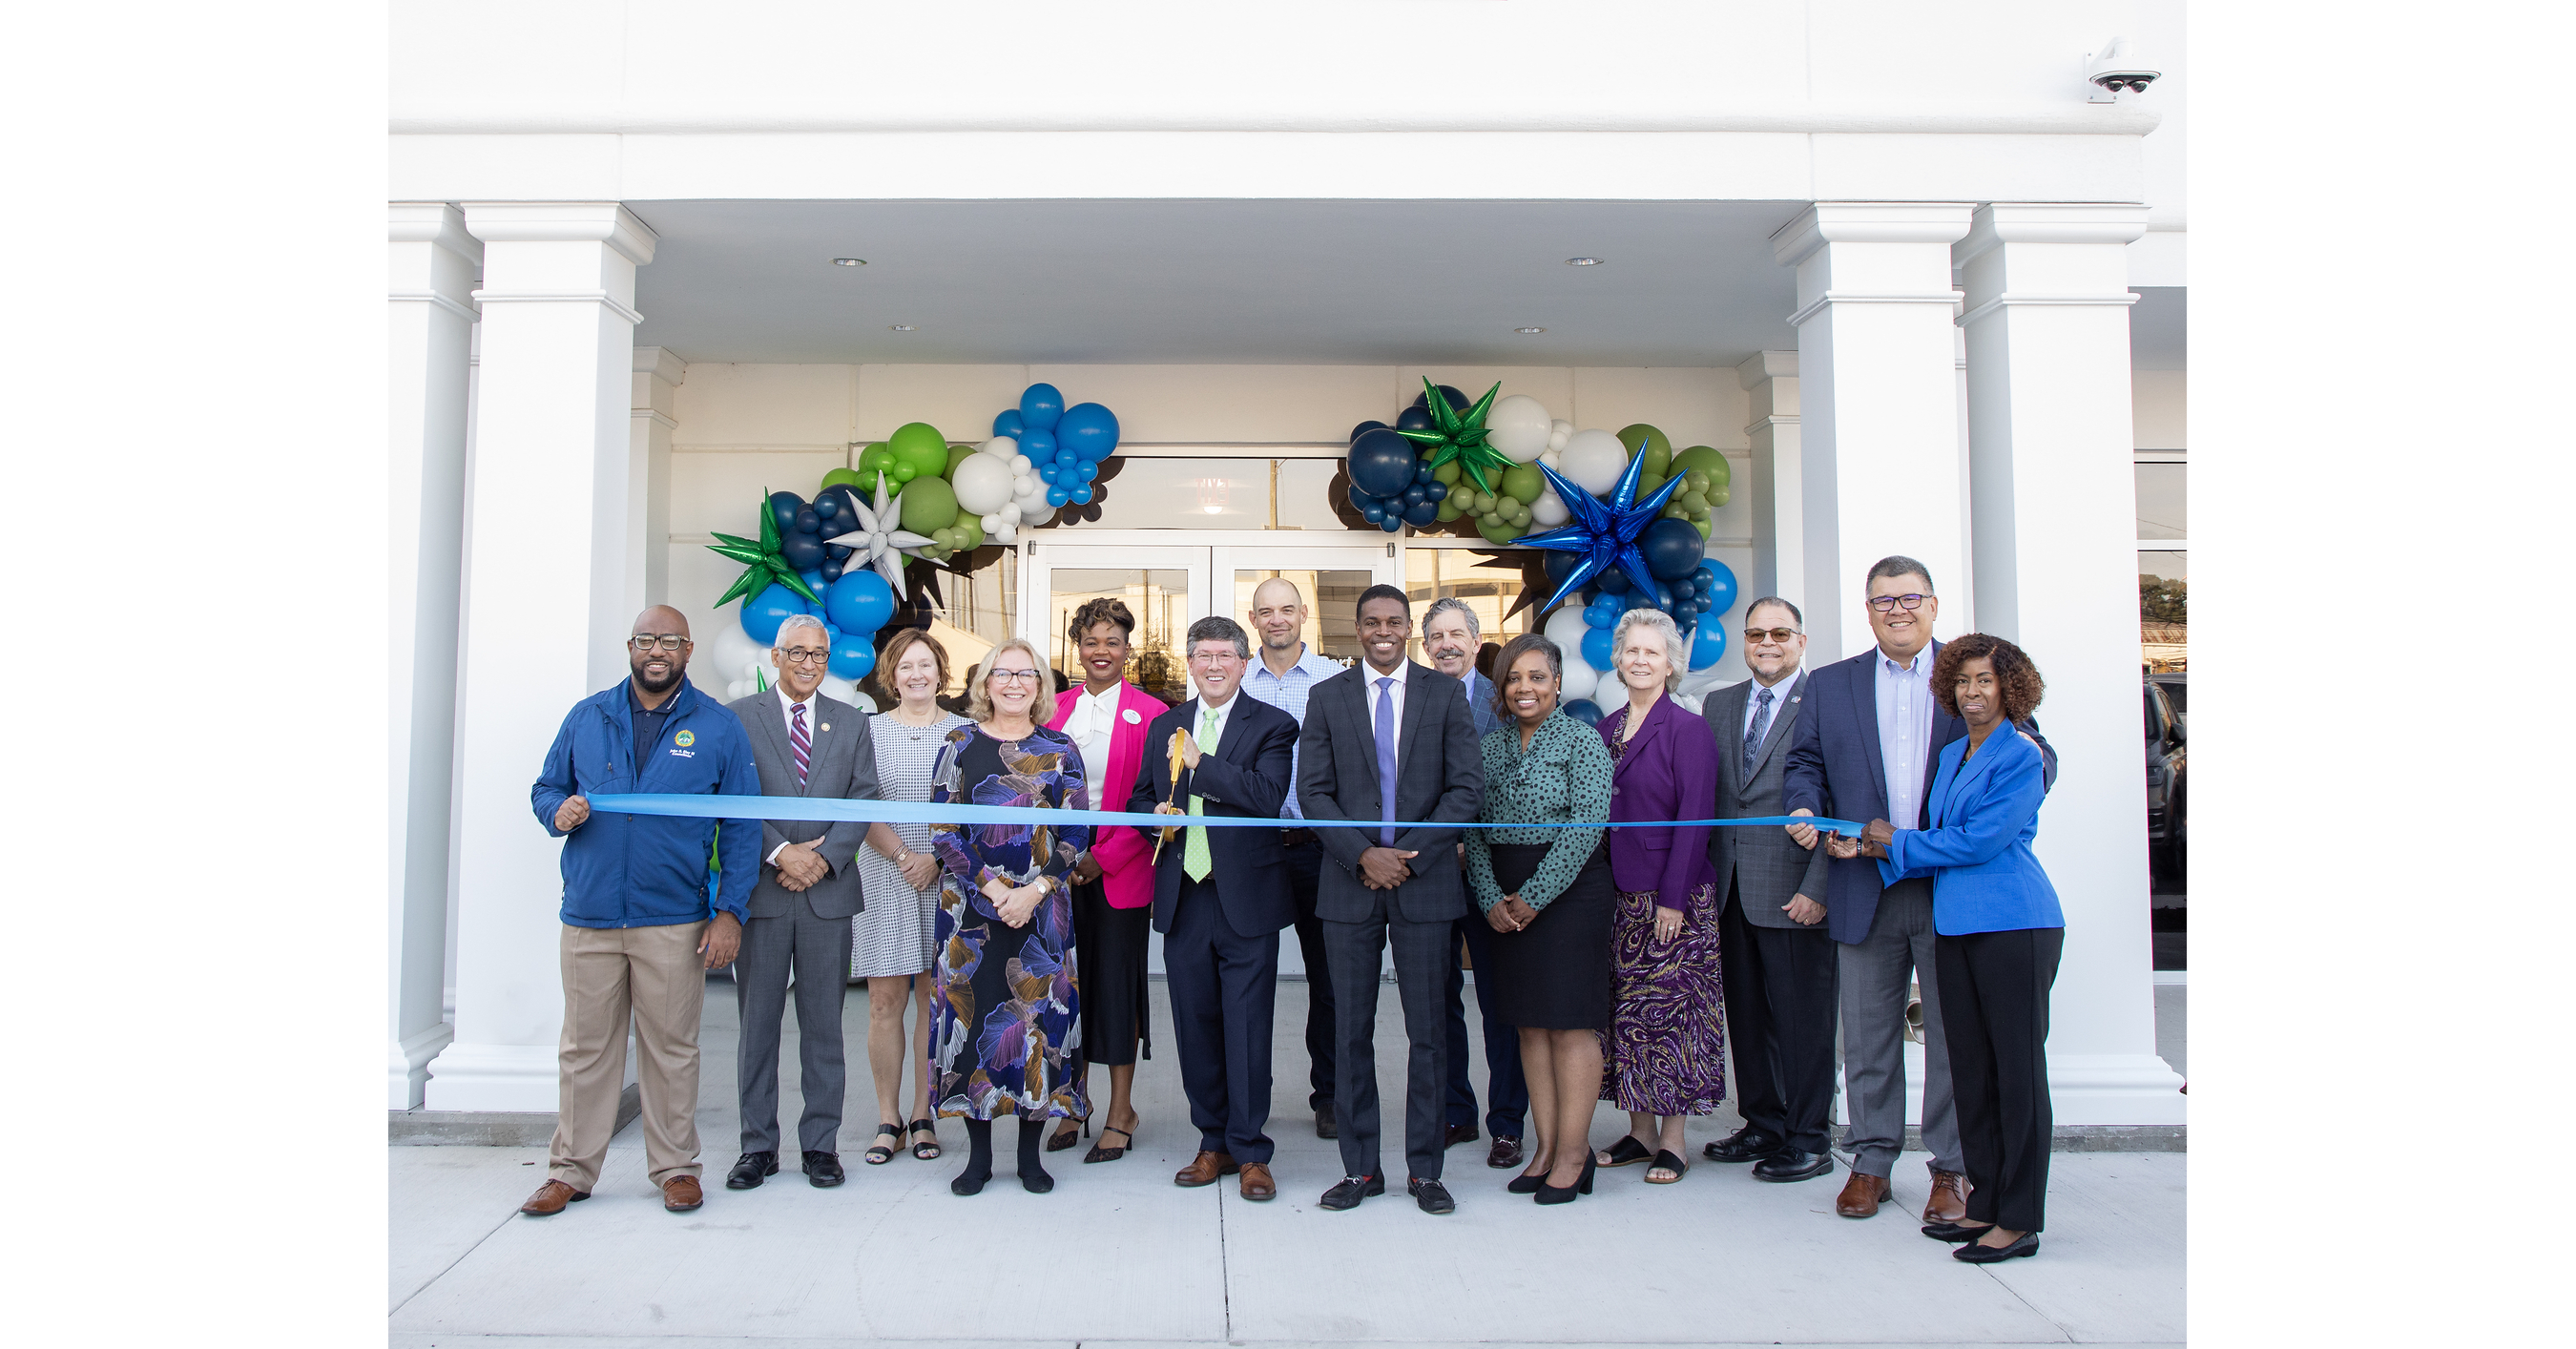
BayPort Credit Union celebrated the reopening of its renovated 37th Street branch in downtown Newport News, its first branch and a location serving the shipyard community for generations. The branch adds interactive teller machines and parking; BayPort also donated $25,000 to The Mariners' Museum and Park. BayPort reports $2.7 billion in assets and more than 156,000 individuals and business members across 31 Virginia branches.
Analysis
This is franchise maintenance, not an earnings catalyst. A sole downtown branch can support relationship retention and local deposit gathering, but the article provides no evidence that the renovation materially changes account growth, funding costs, or operating efficiency. ITMs and a consolidated service floor could improve staff throughput over time; renovation costs and ongoing branch expenses work the other way, and neither effect is quantified. The strategic asset is local access and identity, while the constraint is that a single location does not establish a meaningful competitive advantage across BayPort’s broader footprint.
The less obvious exposure is local concentration: the shipyard connection may help anchor member relationships, but it also makes employment and credit performance worth monitoring against the regional shipbuilding cycle. The article does not establish current member or loan concentration, so this is a diligence question—not a claim of material exposure. Digital-first providers and larger institutions can still compete for deposits and payments without a nearby branch.
Near term, expect little price discovery: BayPort is a credit union, and no public security is identified. Over 1–3 months, the useful evidence would be deposit growth, member acquisition, branch operating costs, and loan delinquencies. Over 6–18 months, broader branch modernization could matter if it demonstrably lowers service costs while retaining deposits. The contrarian point is that “only branch downtown” sounds like a moat, but may reflect limited market economics rather than unmet, profitable demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No direct trade: BayPort has no identified publicly traded security, and this ceremonial reopening alone does not support a directional position in listed banks.
- Treat the branch as a watch item, not a catalyst. Seek evidence of deposit/member growth and lower cost-to-serve before assigning value to the ITM and layout changes.
- For regional-bank exposure, monitor competitive deposit pricing and local funding trends rather than inferring that BayPort’s location automatically pressures other lenders; the article gives no market-share or rate data.
- Falsifiers for the local-franchise thesis: persistent deposit outflows, rising branch costs without improved service efficiency, or worsening local loan delinquencies. Verify BayPort’s member, loan, and deposit concentration by employer and geography before treating shipyard ties as a material risk.
More News
- CH Robinson to Buy RXO for $5.8B in Bet on AI Model
- Nike’s China troubles: What are the implications for other sportswear brands?
- SpaceX stock climbs to highest since June, returning Musk to trillionaire status
- Schneider Electric drops $22.6B on PTC as datacenter boom rains money on infra companies
- Wells Fargo gets a bold upgrade ahead of earnings. Why the stock can play catch-up
- Why did Mattel stock surge 5% today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Run Cost-Controlled Financial Research in AllMind Agent Studio
- State of Public Markets, June 2026: Higher for Longer Meets the AI Supercycle