
Holland America Line Unveils New Beach Club and Food Pavilion at RelaxAway, Half Moon Cay
Source: PR Newswire
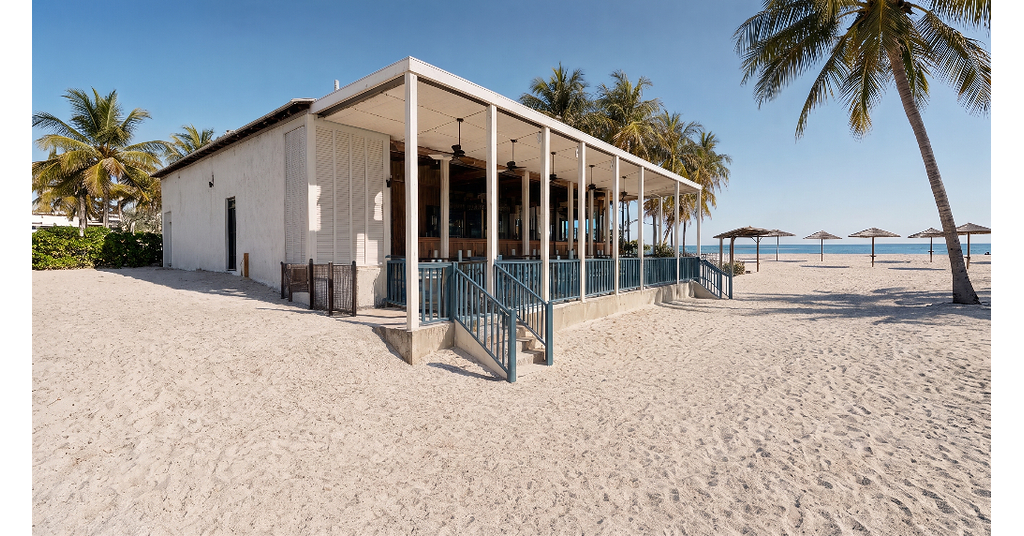
Holland America Line completed upgrades to its RelaxAway, Half Moon Cay private island ahead of its 30th anniversary in 2027, including a new paid Beach Club, food pavilion, renovated bars, upgraded cabanas and four pickleball courts. The enhanced destination will be offered on more than two dozen Caribbean itineraries from October 2026 through April 2027, alongside a promotion offering up to 50% off fares and free kids' fares on select sailings. The investment supports guest experience and Caribbean cruise demand but is unlikely to materially affect Carnival Corporation's near-term financial results.
Analysis
The economic significance is not the island refresh itself but whether Carnival can monetize scarce private-destination capacity through higher onboard-equivalent spend and reduced tender friction. A premium beach product can lift per-guest excursion/F&B revenue with minimal incremental vessel fuel or port-cost burden, making contribution margins potentially higher than broad fare discounting. However, the concurrent promotional intensity implies management is prioritizing occupancy; that is supportive of load factors but limits confidence that yield improvement, rather than ancillary mix, will drive 2027 EBITDA.
For CCL, the relevant 1-3 month catalyst is early booking uptake and disclosed pricing for the Beach Club versus existing cabanas/excursions. Strong attach rates would validate a repeatable private-island monetization playbook across Carnival’s portfolio; weak uptake would indicate the offering is mostly a cost center designed to defend Caribbean share. Norwegian (NCLH) and Royal Caribbean (RCL) have stronger investor-recognized private-destination monetization narratives, so a successful rollout modestly narrows that competitive gap rather than creating a differentiated advantage.
Consensus may over-credit any guest-experience announcement as evidence of premiumization. The key falsifier is Caribbean net yield: if 2027 bookings require continued deep fare promotions or onboard revenue per passenger cruise day does not accelerate, incremental island spend will not offset pricing pressure. Longer term, weather disruptions, tendering constraints, and destination-capacity regulation remain more material to returns than amenity breadth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone CCL trade on this release; treat it as a watch item until Beach Club pricing, capacity, and booking attach-rate data are available in the next earnings update.
- For existing CCL exposure, monitor 2027 Caribbean net-yield guidance and onboard revenue per passenger cruise day over the next 1-2 quarters; reduce if promotional activity persists without a measurable ancillary-revenue lift.
- Use a relative-value screen rather than directional exposure: consider long CCL / short NCLH only if CCL’s forward EBITDA estimate revisions turn positive while its valuation discount to NCLH remains wider than its historical range; invalidate on weaker Caribbean yield guidance.
- If private-destination monetization appears in reported results, favor RCL as the cleaner confirmation vehicle over chasing CCL: RCL has greater earnings sensitivity to premium destination spend, while CCL retains higher leverage and execution risk.
More News
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Trump Says US Team Met With Iranians at UNGA
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Australia’s IDP shares drop after rejecting $494 mln Blackstone offer
- Meta’s Muse AI is exploding in popularity—and already drawing heated backlash from another tech giant
- Lennar shares pop as Berkshire builds almost a 10% stake in beleaguered homebuilder
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect