
NIVEA Introduces New Smooth & Glow Body Milk to Immediately Smooth Dry, Rough Skin and Deliver 72-Hour Deep Moisture
Source: PR Newswire
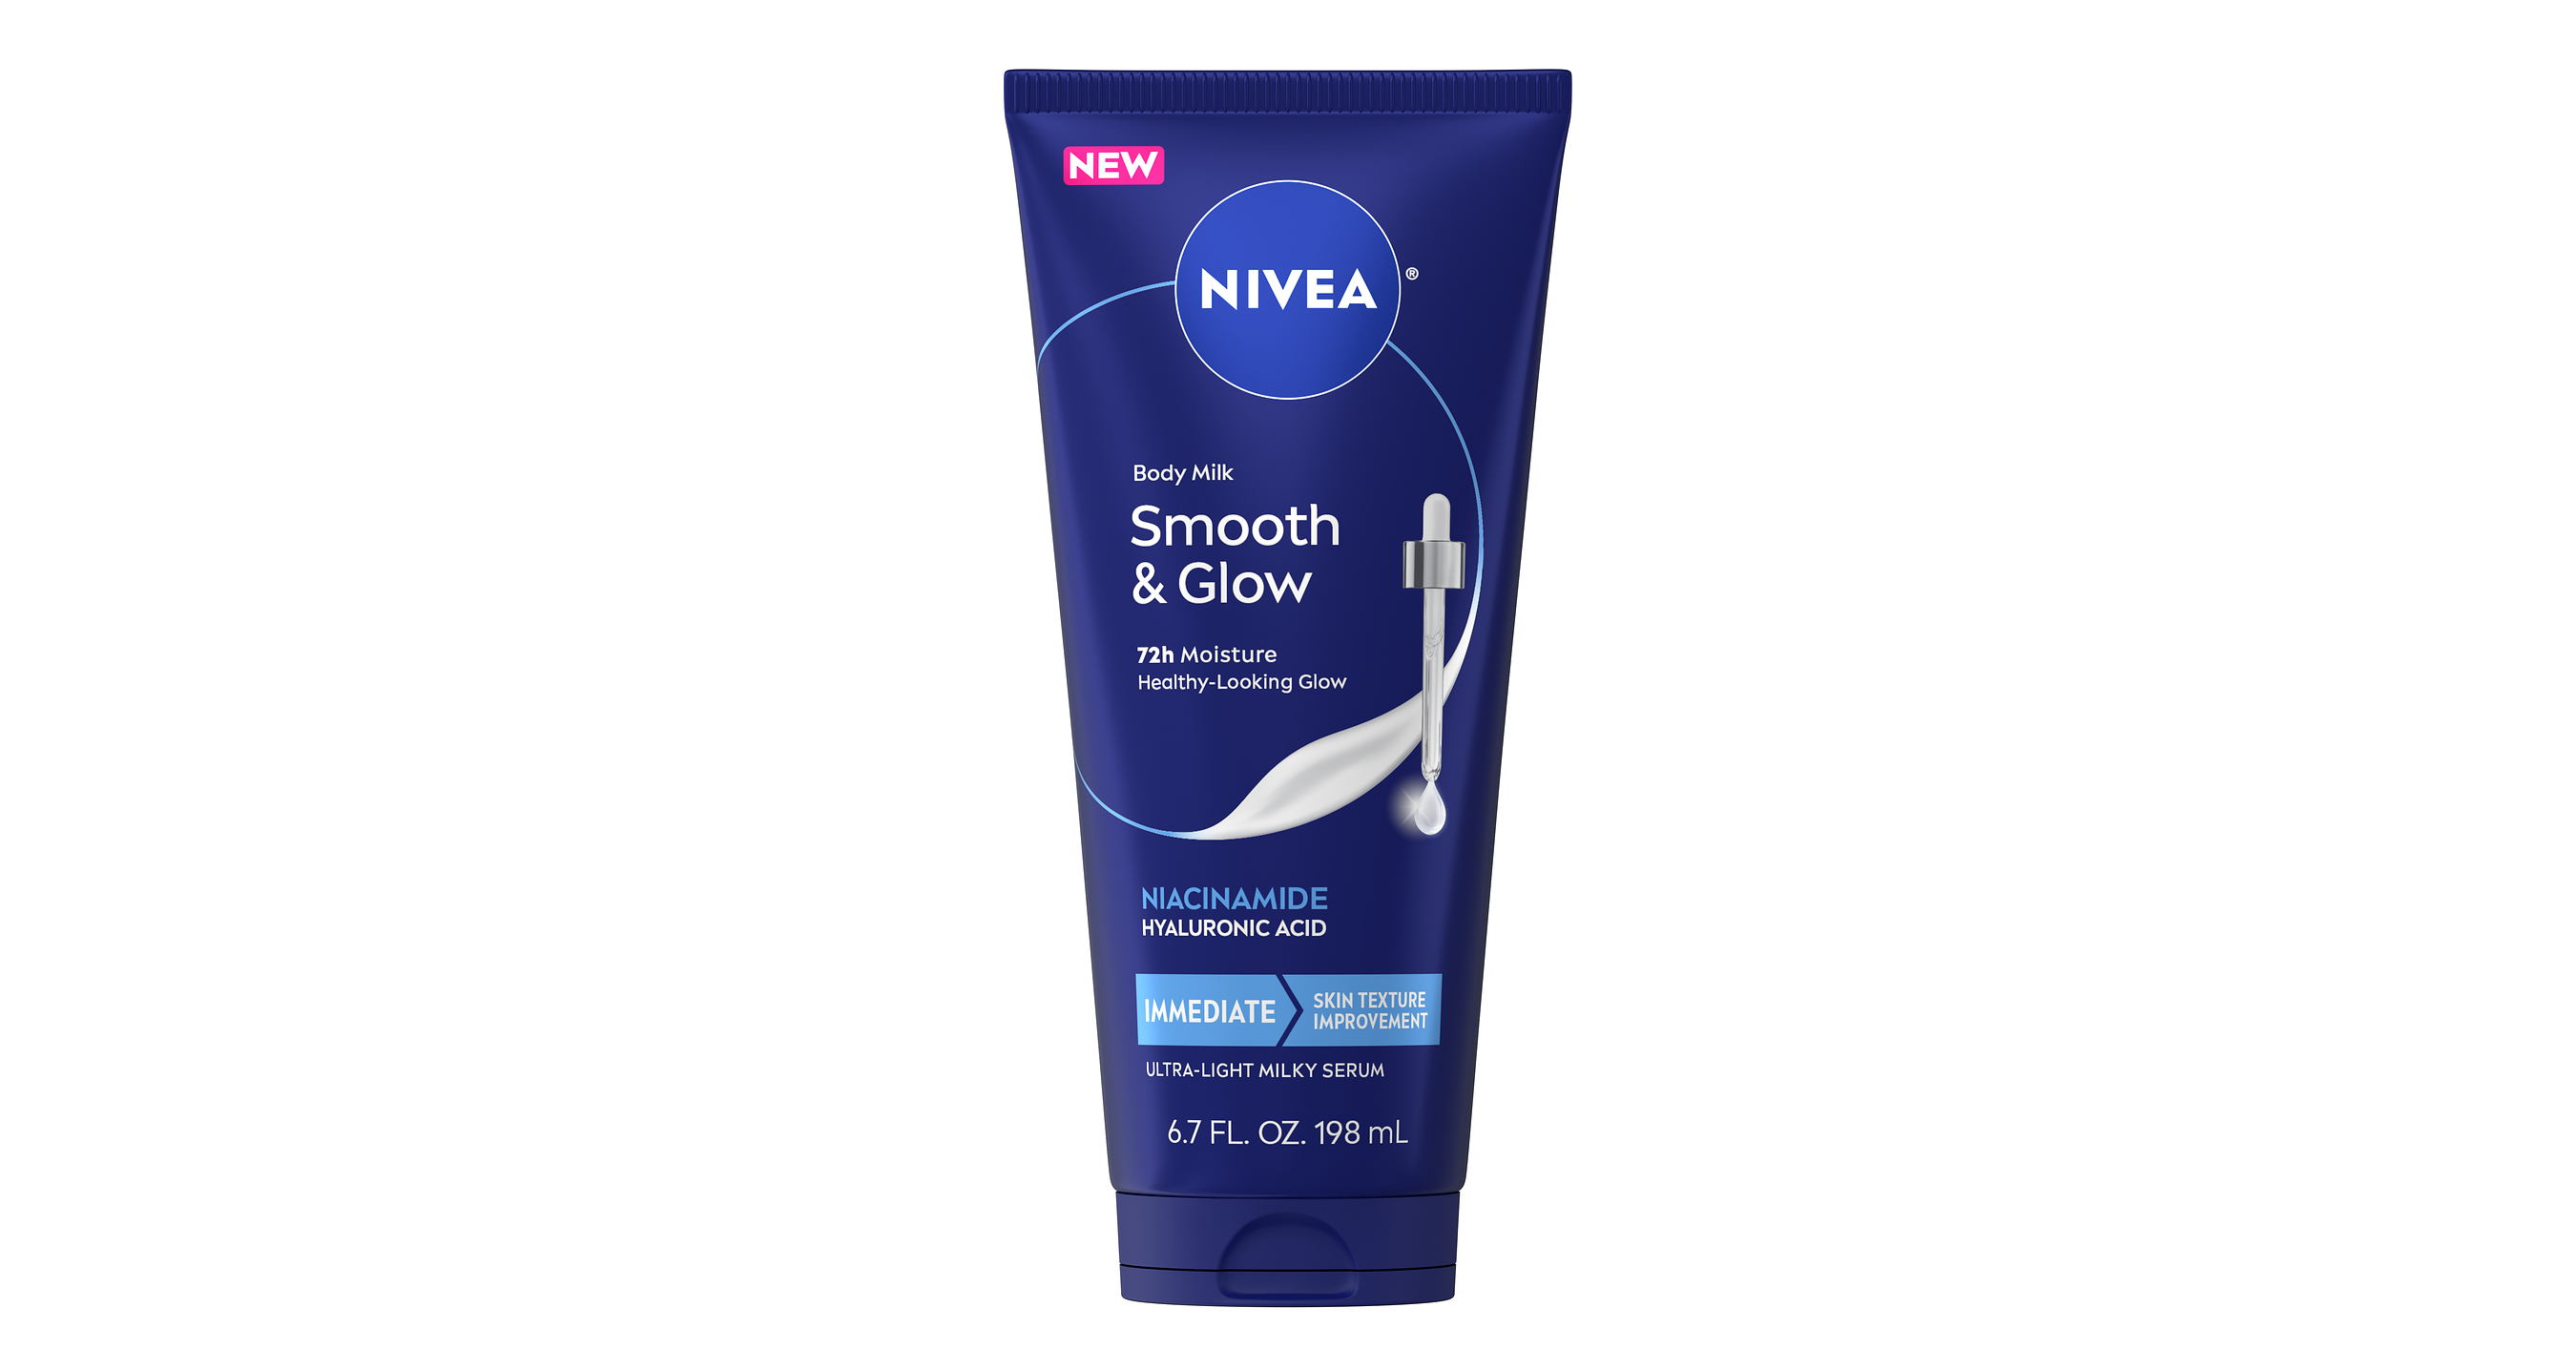
Beiersdorf's NIVEA launched Smooth & Glow Body Milk nationwide at a starting price of $5.99 through TikTok Shop, Amazon, Walmart, Walgreens and CVS. The product claims 72 hours of moisture and targets normal-to-dry skin with niacinamide, hyaluronic acid and an ultra-light formula. NIVEA cited a 2025 study finding that 43% of users treating rough, dry or dull skin are dissatisfied with existing body-lotion products, supporting the addressable consumer need. The launch is a modest portfolio innovation with limited near-term market impact.
Analysis
This is strategically more relevant for Beiersdorf (BEI.DE) as a test of whether its mass-market innovation can defend mix and shelf space without sacrificing pricing discipline. At a sub-$6 price point, incremental revenue is unlikely to move group estimates absent unusually rapid velocity, but the launch can protect NIVEA’s US relevance in a category where prestige-inspired ingredients have migrated down-market. The key financial question is not sell-in, but repeat purchase and whether promotional support raises customer-acquisition and trade-spend costs faster than gross profit.
The multi-channel rollout creates modest leverage for AMZN and WMT through traffic and category conversion, but the sales contribution will be immaterial. The more meaningful competitive read-through is negative for body-care brands whose proposition depends on premium pricing for niacinamide/hyaluronic-acid claims—especially Unilever’s Vaseline/Dove franchise and smaller Amazon-native brands—if NIVEA achieves strong reviews and organic TikTok conversion. CVS is a potential shelf-space beneficiary only at the margin; its more relevant exposure is category margin and vendor funding, neither disclosed here.
Near term, this is not a standalone trading catalyst. Over 1-3 months, track Amazon Best Seller Rank, review velocity/rating, TikTok Shop unit sell-through, and retailer promotional intensity versus comparable NIVEA SKUs; a sustained top-tier rank without deep discounting would support an upside case for BEI’s US organic-growth assumptions. The thesis is falsified if the product rapidly enters coupon-heavy promotion, indicating that the low ticket price is cannibalizing existing NIVEA volume rather than expanding the category.
Consensus may over-credit ingredient-led launches in mature body care: texture and absorption can improve trial, but repurchase is determined by sensory differentiation and retailer execution, not efficacy claims. Conversely, BEI’s broader portfolio gives it an underappreciated advantage in converting body-care trial into cross-brand skincare baskets, particularly at Walmart and Amazon, if merchandising links NIVEA with Eucerin or Aquaphor.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in AMZN, WMT, or CVS: the implied revenue contribution is too small to affect estimates; use the launch only as a consumer-staples category data point.
- Maintain or modestly add to BEI.DE only on independently observable evidence of traction: initiate after 6-8 weeks if Amazon ranking/review velocity is strong and average realized price remains near list. Target a 3-6 month horizon; exit if promotional intensity rises materially or management signals US margin dilution.
- Monitor ULVR/UL as the cleaner relative loser rather than shorting on launch day. Consider long BEI.DE / short ULVR only if NIVEA gains measurable US body-care distribution or share while Unilever’s personal-care growth decelerates; the required confirmation is scanner-data share movement, not press-release claims.
- Set an alert for Beiersdorf’s next results: prioritize North America organic sales growth, NIVEA gross-margin commentary, and A&P/trade-spend changes. A growth uplift accompanied by stable EBIT margin would validate incremental upside; higher spending with no sales acceleration would invalidate it.
More News
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Meta’s Muse AI is exploding in popularity—and already drawing heated backlash from another tech giant
- Meta's quick success with Muse puts consumers back in the driver's seat of the AI trade
- The SaaS debt trap
- $2.5 billion Amazon Prime settlement update: See if you qualify for a $200 payout and learn how to cancel unwanted subscriptions
- Alibaba Cloud plans six-year stroll to 20GW of datacenters, reveals chip to power them
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Track Guidance Changes Across a Coverage List With AI
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?