
Gator Metal Roofing Expands Delivery Fleet to Meet Growing Demand Across the Carolinas
Source: PRWeb
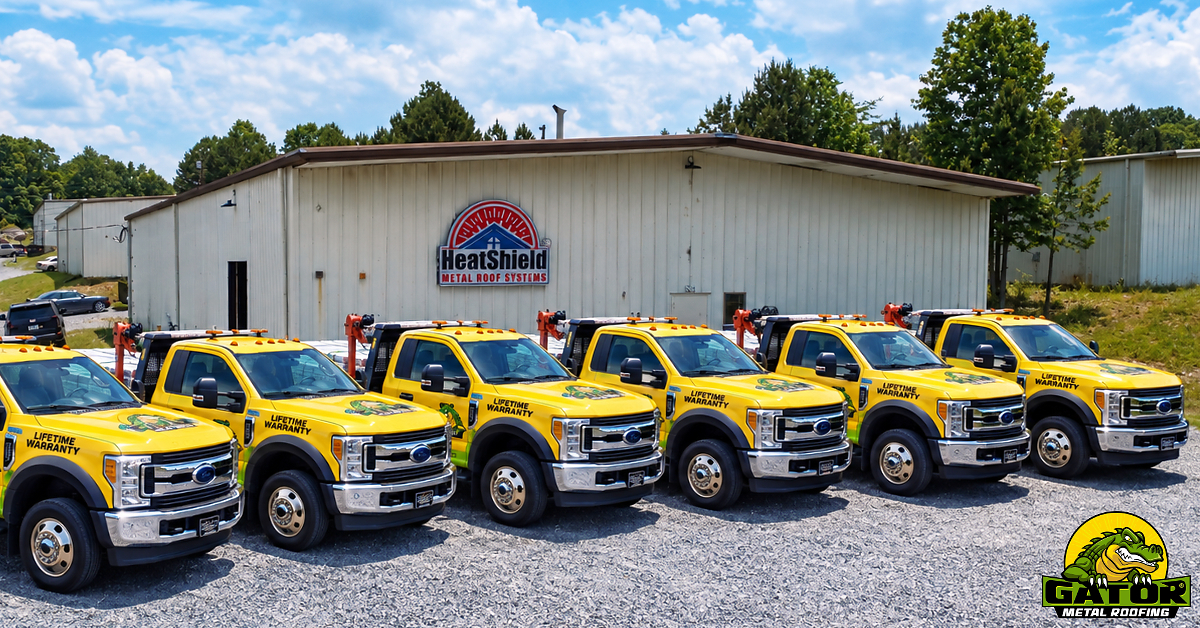
Gator Metal Roofing added a specialized delivery truck to expand capacity for HeatShield metal roof installations across North Carolina and South Carolina amid reported strong homeowner demand. The vertically integrated contractor manufactures its systems in Asheboro, North Carolina, and said the fleet investment will improve material delivery and support a growing installation schedule. No financial metrics, fleet size, revenue figures, or quantified demand growth were disclosed.
Analysis
This is not an investable demand datapoint: a single privately held installer’s fleet addition has no measurable read-through to public roofing, building-products, steel, or freight earnings. The relevant signal is only directional—specialty metal reroofing continues to compete for replacement budgets that otherwise flow to asphalt shingles—but one contractor’s capacity decision cannot distinguish end-market demand from normal scheduling, route-density, or management optimism.
For listed companies, the structural substitution is modestly supportive of coated-steel and metal-building-material volumes (NUE, STLD) and potentially a marginal headwind to asphalt-heavy roofing mix at OC, but Carolinas residential reroofing is far below a level that can move consolidated forecasts. Over 6-18 months, sustained insurance premium inflation, storm activity, and homeowner financing availability matter far more than installer fleet investment; higher mortgage rates or weakening home-equity liquidity would pressure discretionary premium reroofing first. Treat this as a channel-check prompt, not confirmation of a demand inflection.
The contrarian point is that vertical integration can improve a local installer’s delivery reliability without implying superior industry pricing. Additional owned logistics capacity may instead reflect rising last-mile costs, longer installation lead times, or an effort to protect service levels; absent evidence of backlog duration, realized price per square, cancellation rates, and factory utilization, there is no basis to extrapolate margin expansion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No standalone trade recommended; do not alter positions in BECN, BLDR, OC, NUE, or STLD on this release.
- Add a 1-3 month channel-check watch item for BECN and OC: seek corroboration in Southeast distributor volumes, reroof backlog, and price/mix commentary. A broad-based acceleration in metal-roof demand would be more relevant to coated-steel suppliers than to national shingle earnings.
- For any existing long OC exposure, monitor roofing segment volume versus price/mix at the next earnings release; sustained volume declines alongside rising metal-roof penetration would be the falsification trigger for an asphalt-roofing resilience thesis, though this announcement alone provides no such evidence.
- Use housing-finance and storm-loss data rather than contractor fleet announcements as the actionable catalysts: a meaningful easing in consumer borrowing costs or elevated insured-loss activity over the next 6-12 months would provide a stronger basis for long BECN/BLDR exposure.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- History shows financial calamities occur when rates rise rapidly like this: 'Something always breaks'
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- 30-year fixed mortgage rate jumps sharply Thursday to 7.45%
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Tools for Pension Funds and Allocators
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals