
Fortitude Gold Acquires Dreadnaught Property
Source: Newswire
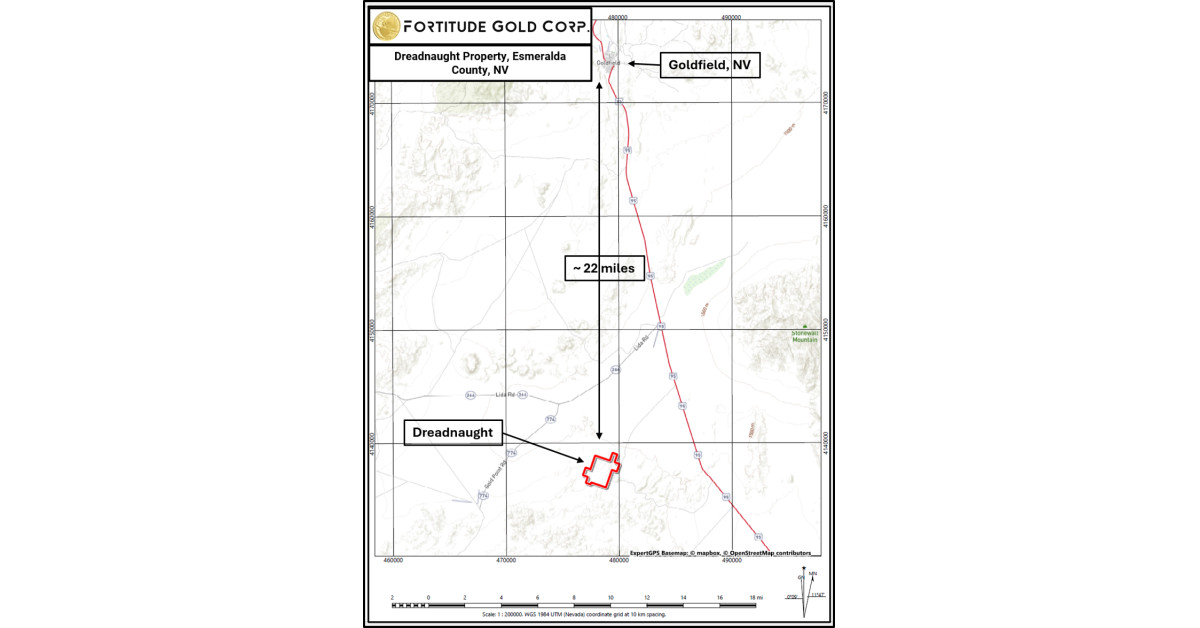
Fortitude Gold acquired 100% of the 1,343-acre Dreadnaught property in Nevada through low-cost staking, adding its ninth Nevada gold property with no net-smelter-return royalty burden. Recent surface sampling returned gold grades up to 17.18 grams per tonne, supported by historic soil, geophysical and shallow drilling data. The company plans property-scale sampling and targeting work, but has not disclosed a resource estimate, development timeline, or expected production impact.
Analysis
This is an option-value addition rather than a near-term NAV event: staking cost and the absence of a royalty create favorable theoretical economics, but surface samples and legacy shallow drilling do not establish tonnage, continuity, metallurgy, recoveries, or permitting viability. FTCO's valuation should not re-rate materially until a defined drill program produces repeatable intercepts and management provides a development sequence relative to its existing Nevada pipeline. In a thin OTC security, a promotional liquidity-driven move is more likely than a durable fundamental response over the next several days.
The relevant 1-3 month catalyst is disclosure of drilling targets, budget and timing, followed by first-pass drilling; the key risk is that alteration and high-grade float/outcrop are structurally discontinuous, leaving no economic feeder zone at depth. Over 6-18 months, a genuine discovery could be strategically valuable because any future mine could leverage regional operating knowledge and potentially preserve more project-level cash flow than royalty-burdened peers. Conversely, exploration spending competes with sustaining capital, reserve replacement and the dividend mandate; if production guidance or free cash flow weakens, investors are unlikely to assign value to another early-stage claim package.
Contrarian view: the no-royalty framing may attract disproportionate attention, but royalty-free ownership has little value without a compliant resource and a demonstrated processing route. The more investable Nevada exploration exposure remains larger, liquid operators with funded drill programs and independently reported resource bases; this announcement alone does not justify substituting FTCO for names such as NGD, EQX or SSRM.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No new FTCO position on this release. Treat any near-term volume/price spike as liquidity-sensitive; reassess only after the company publishes drill spacing, intercept widths, QA/QC and an exploration budget.
- For existing FTCO holders, retain only a small exploration-option allocation through the next 1-3 months; reduce if management raises exploration spend without reaffirming production, dividend coverage and liquidity. Thesis is falsified by downward production guidance or a dividend reduction.
- Set a diligence alert for a resource-definition program: a potential long requires multiple coherent drill intercepts, disclosed metallurgy and a credible path to economic scale, not additional surface-chip results. Absent those data within 6-12 months, assign negligible project NAV.
- Use liquid Nevada-gold proxies rather than FTCO for a gold-price tactical view; FTCO-specific upside is discovery-dependent while downside includes OTC liquidity, single-jurisdiction operating concentration and capital-allocation pressure.
More News
- Trump says US may ask Europe to release diesel reserves
- Latest Oil Market News and Analysis for Oct. 2
- Oil holds gains as U.S. weighs more Middle East military presence
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year