
Newmark Arranges $482.5 Million Financing to Advance The Stockman, Auberge Collection in Steamboat Springs, CO
Source: PR Newswire
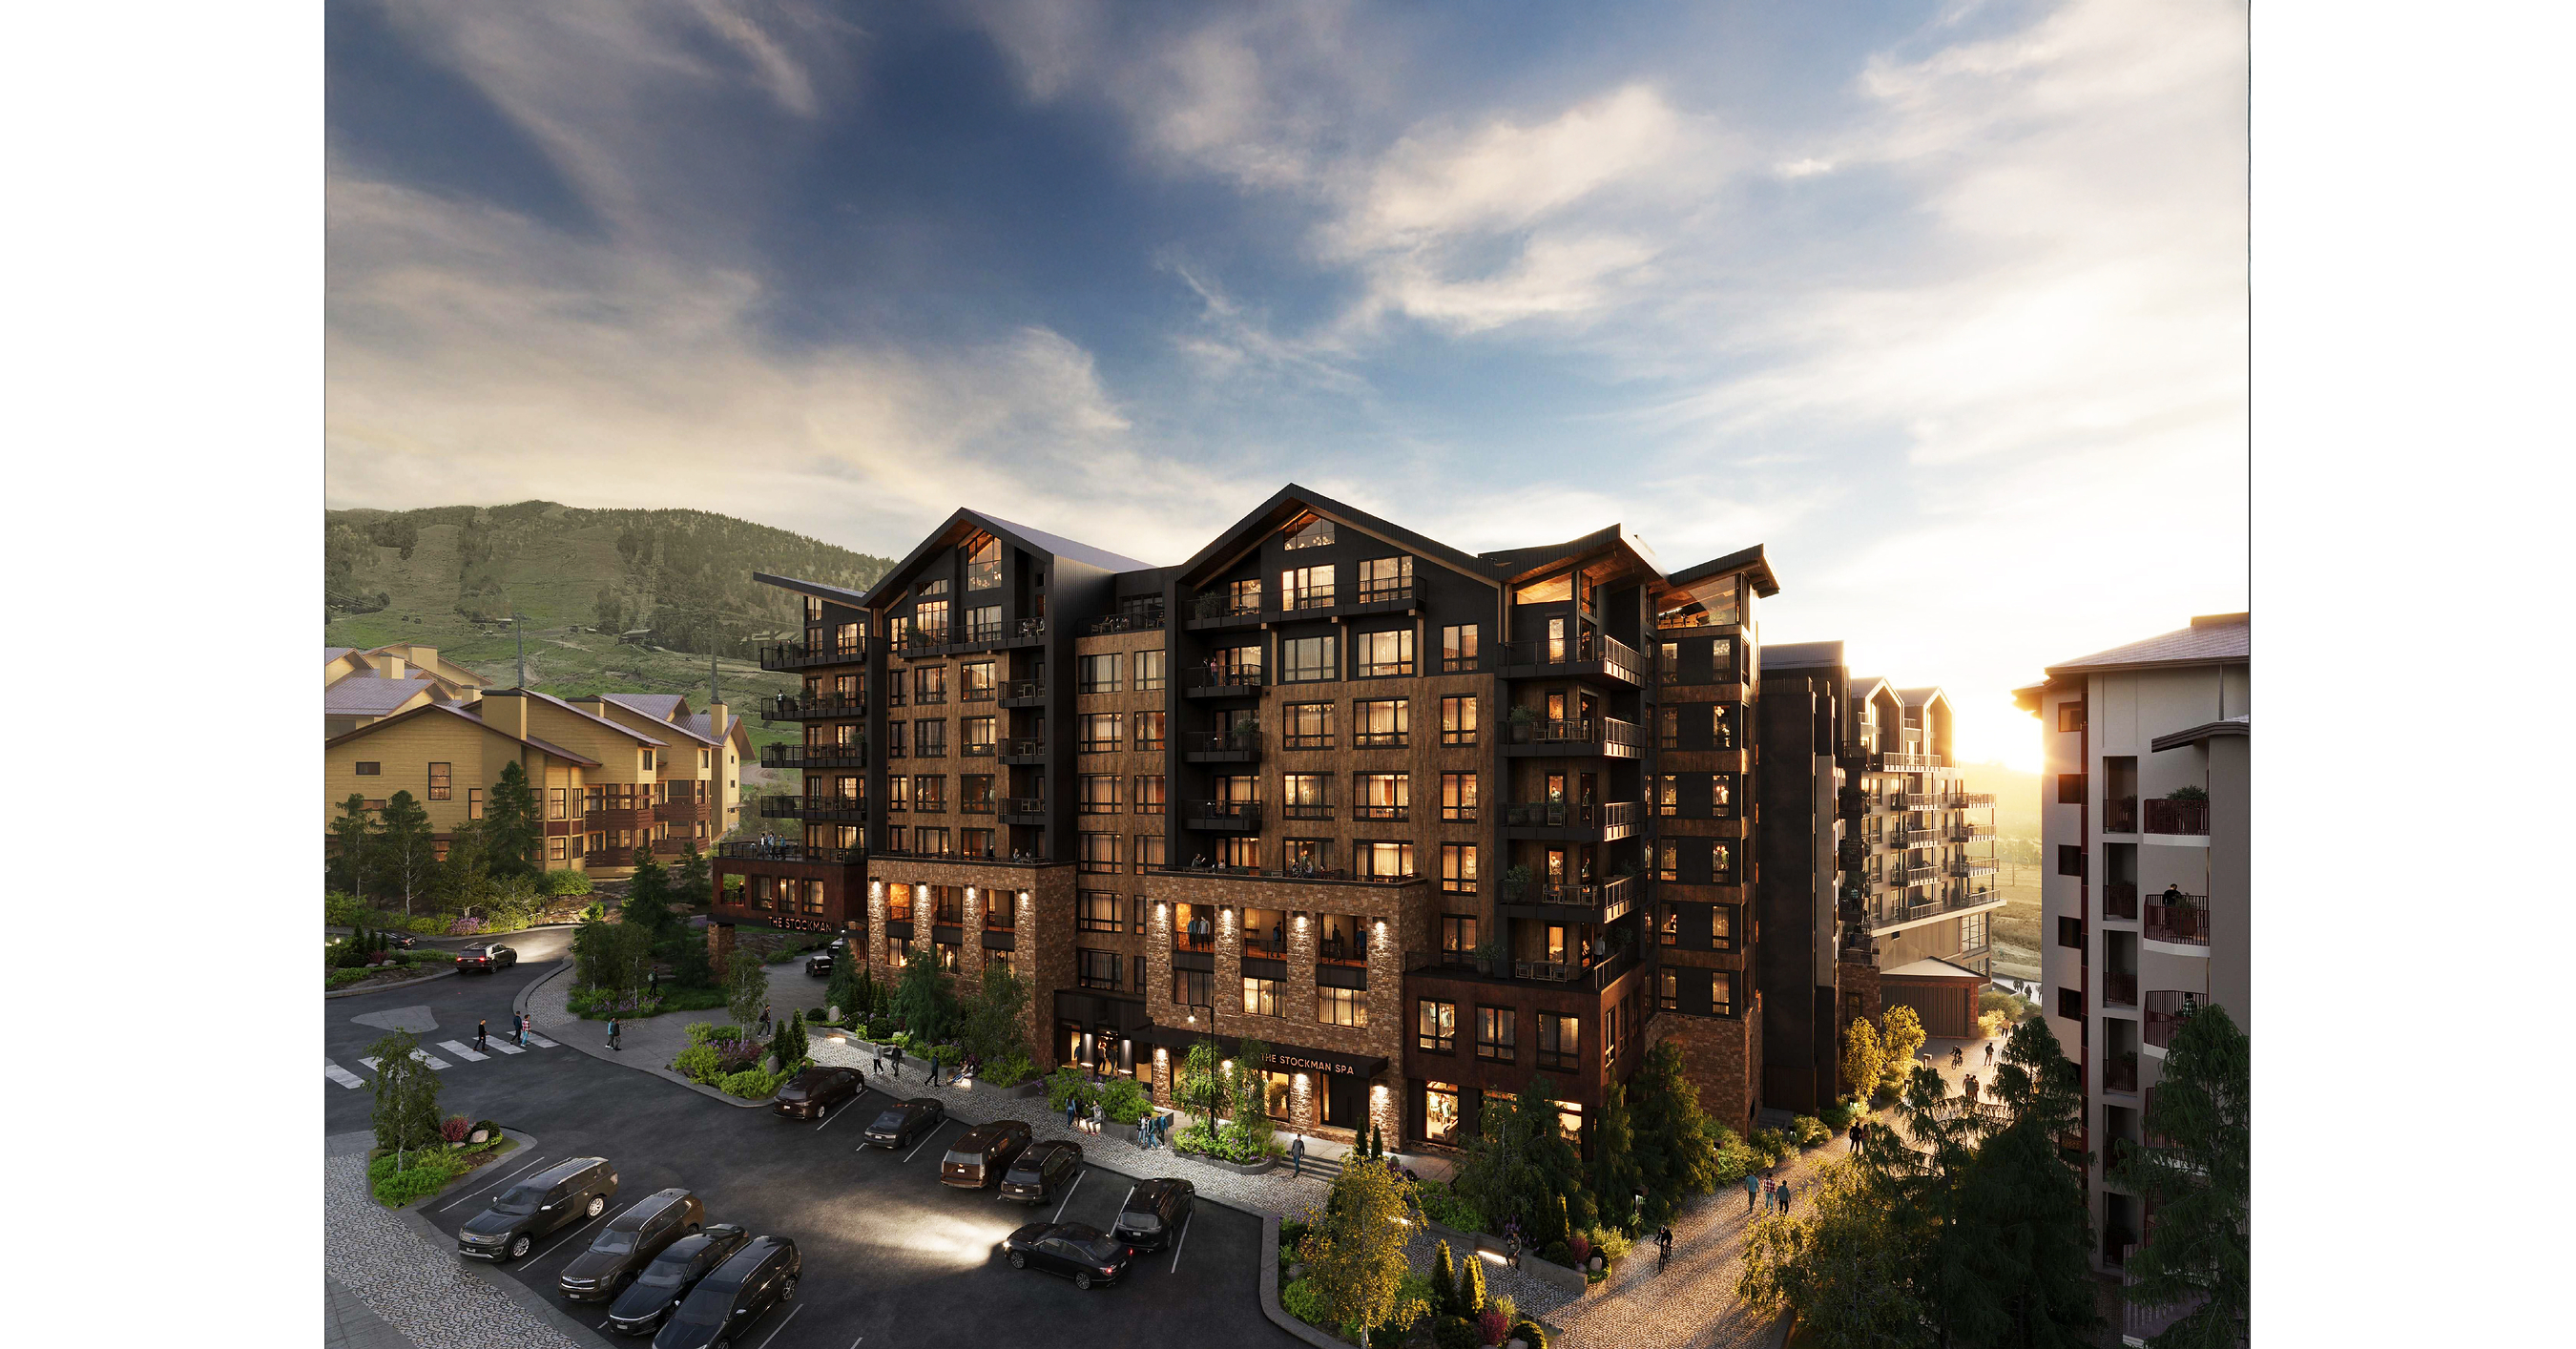
Newmark arranged a $482.5 million loan from GoldenTree Asset Management for The Stockman, Auberge Collection, an ultra-luxury ski-in/ski-out resort under construction in Steamboat Springs, Colorado. The project will include 95 branded residences and a 59-key Auberge-operated hotel, adding to Alterra's prior $250 million "Full Steam Ahead" investment program at Steamboat Resort. The financing is a meaningful transaction for Newmark's commercial real-estate debt platform but is unlikely to materially affect its broader financial outlook.
Analysis
The underwriting signal matters more than the advisory fee: a large private-credit commitment to a single-asset, discretionary hospitality project suggests lenders remain willing to fund differentiated collateral despite broader commercial-real-estate caution. That is constructive for NMRK's debt-placement pipeline and, secondarily, for CBRE and JLL, but it is not individually material to NMRK earnings. The more relevant read-through over the next 1-3 months is whether this is followed by comparable resort, branded-residence, or high-end mixed-use financings at stable leverage and spreads.
Private credit is taking share where banks remain constrained by concentration limits and regulatory capital costs. That structurally favors intermediaries with lender relationships, while benefiting alternative-credit managers such as BX, KKR and APO only if deployment occurs at attractive yields without weakening covenants. The contrarian risk is that a marquee transaction can represent sponsor-specific collateral and presales rather than a reopening of the broader construction-finance market; it should not be extrapolated to office, commodity multifamily, or lower-tier hospitality.
For NMRK, the 6-18 month upside is a higher mix of capital-markets and structured-finance revenue, which carries operating leverage as transaction volumes recover. The key falsifier is not this closing but sequential evidence in quarterly disclosures: debt and structured-finance activity must outgrow the broader leasing/advisory base, with no offset from fee-rate compression. A widening in private-real-estate credit spreads, weaker luxury-home absorption, or rising construction costs would quickly reduce lender appetite and impair the pipeline.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- No standalone event trade in NMRK: treat this as a watch signal, not an earnings catalyst. Reassess long exposure ahead of the next results only if management indicates sequential growth in debt/structured-finance mandates and capital-markets backlog; otherwise the transaction is too small to support a valuation rerating.
- Use NMRK as a tactical long versus JLL over a 3-6 month horizon only if private-credit spreads remain contained and additional high-end construction financings emerge. Thesis: NMRK can gain from debt-placement volume recovery; exit if private-credit spreads widen materially or NMRK's capital-markets revenue fails to improve sequentially.
- Avoid treating BRK.A as a beneficiary. Residential brokerage economics are immaterial to Berkshire's consolidated earnings, while any luxury-residential sales upside carries project-completion and absorption risk.
- Monitor BX, KKR and APO credit-deployment commentary rather than buying on this item. A broader investable signal requires evidence of rising originations at maintained underwriting standards, not isolated large-ticket lending.
More News
- Warren Buffett’s son worked on a farm instead of going to college—he’s now the chairman of $1 trillion Berkshire Hathaway
- Tumbling Global Government Bonds Put Yields on Brink of 4%
- Japan's 10-year bond yield hits 30-year high following sell-off in Treasurys
- US Debt Selloff Spans Most Maturities: Evening Briefing Americas
- Here's what happens to the economy when Treasury yields soar like they are now
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet