
The 2026 Sales Tax Year in Review
Source: PR Newswire
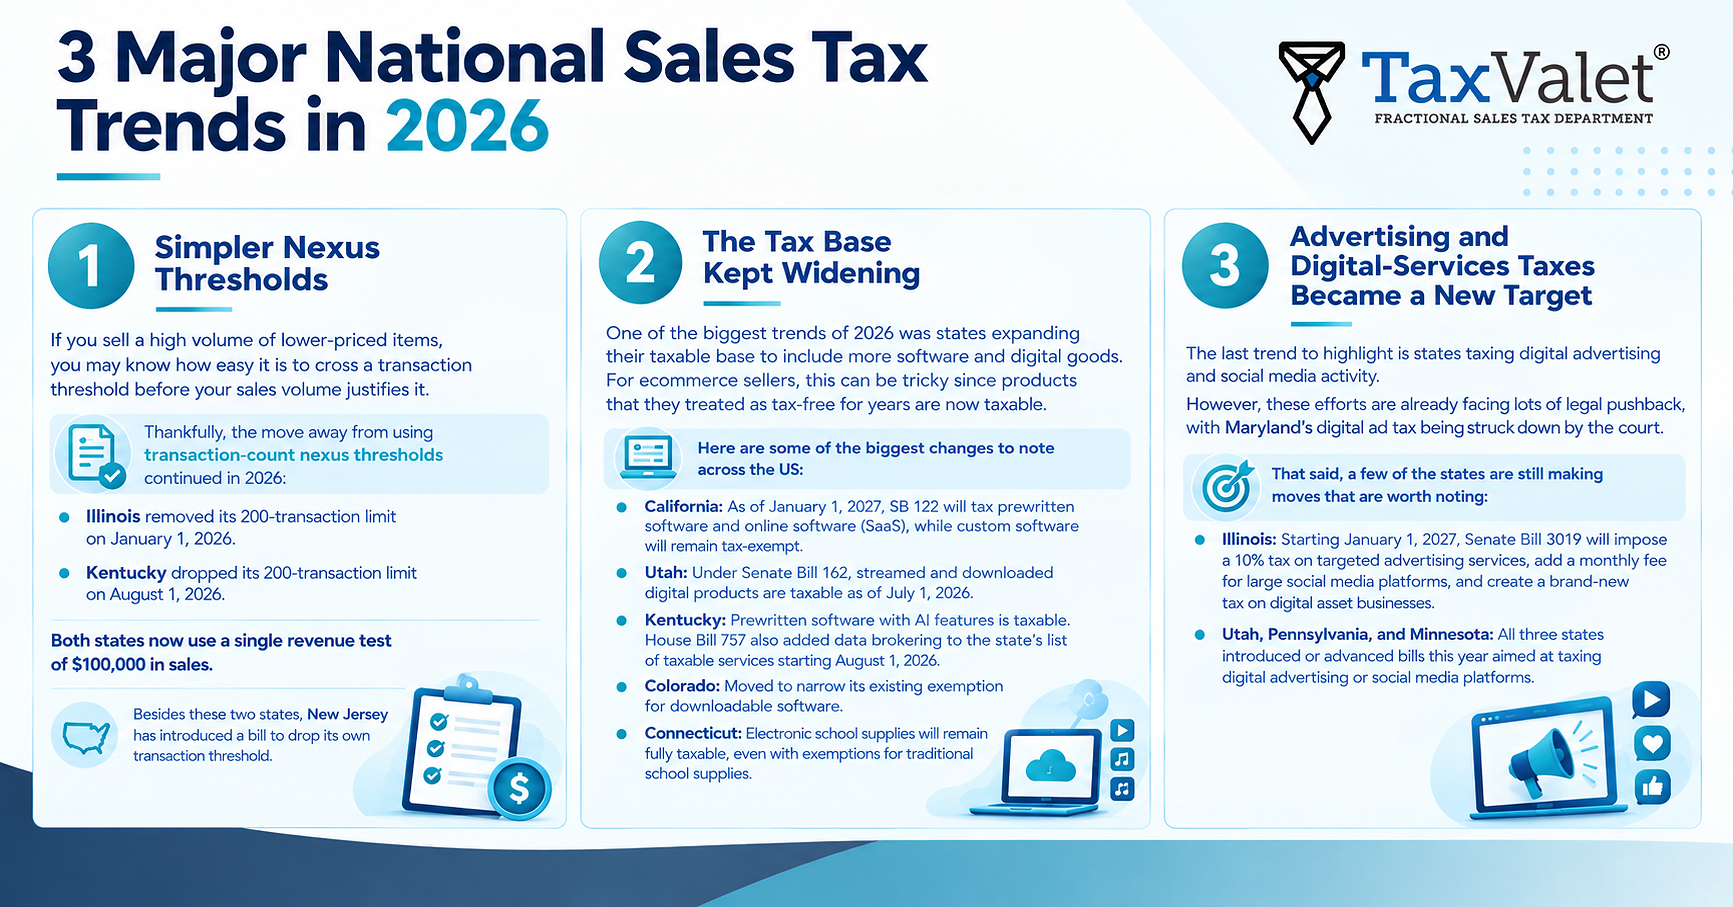
Illinois (January 1) and Kentucky (August 1) removed their 200-transaction sales-tax nexus thresholds, retaining a $100,000 sales threshold. California is set to tax prewritten software and SaaS beginning January 1, 2027, while custom software remains exempt; Kentucky clarified taxation of AI-enabled prewritten software and began taxing data brokering as a service on August 1. A Maryland Tax Court ruled against the state’s digital advertising tax on August 14 in cases brought by Apple, Google, and Peacock, ordering refunds and citing federal-law and constitutional violations.
Analysis
This is a low-signal, compliance-focused update—not a basis for changing AAPL or GOOG earnings estimates on its own. The Maryland ruling is directionally favorable to digital-ad platforms: if upheld or followed elsewhere, it could constrain states’ ability to target ad revenue and reduce a potential layer of tax drag. But a state tax-court decision is not a nationwide safe harbor; appeals and different statutory designs could limit spillover. Treat any benefit to Apple or Alphabet as contingent and likely secondary until there is evidence of material tax expense, refunds, or revised guidance.
The more durable economic pressure runs the other way for software and digital-product sellers. California’s 2027 change may raise compliance costs and, where sellers pass tax through, customer friction; the incidence will depend on product classification, exemptions, and pricing power. Meanwhile, higher sales thresholds in Illinois and Kentucky ease transaction-count monitoring for some sellers, but do not remove sales-based nexus obligations. Net effect: fewer low-value registration triggers in those states, offset by broader taxable categories elsewhere. TaxValet’s commercial framing is not independent evidence of market-wide cost or demand impact.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Ticker Sentiment
Key Decisions for Investors
- No immediate AAPL/GOOG trade: the Maryland ruling is a watch item, not a demonstrated earnings catalyst. Reassess only if appeals, other states’ cases, or company disclosures establish material exposure or refund value.
- Track the Maryland appeal path and any state proposals copying the challenged tax design over the next 1–3 months; a reversal or narrowly limited ruling would falsify the broader precedent thesis.
- For 2027, monitor California implementation guidance and disclosures from software/digital-product sellers for tax pass-through, churn, or compliance-cost commentary. Do not assume the tax is absorbed by sellers without evidence.
- For ecommerce and SaaS exposure, favor a company-by-company review of state sales mix and product taxability over a sector-wide trade; the article provides no revenue, margin, or valuation data to support a quantified position.
More News
- Voters rebuff data centers in every ballot measure except one during the 2026 midterms
- After the midterms, Big Tech’s AI data center problem is only getting bigger
- Uber says it alone can make robotaxis pay, hours after Waymo quit its app
- US markets rise as Democrats sweep midterm elections
- Democrat wins will slow data center construction and force tech to the negotiating table after even Republican stronghold of Texas flips
- How a blue wave crushed the tech right