
iRobot redefine la limpieza manos libres con su robot más potente hasta la fecha: el Roomba® Max 875 Combo
Source: PR Newswire
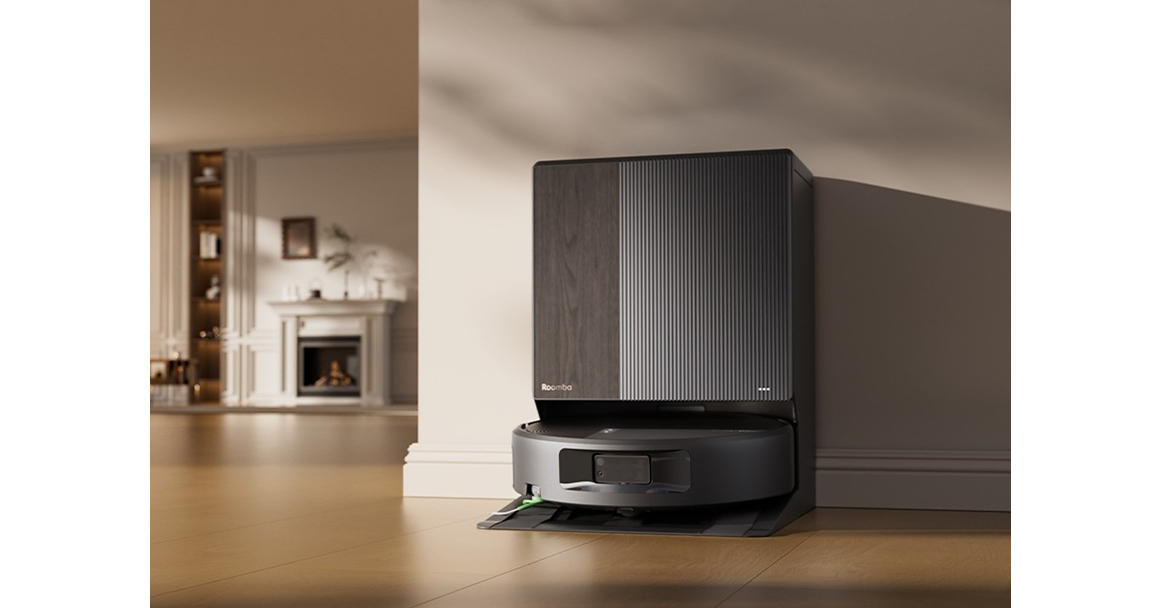
iRobot lanzó el Roomba® Max 875 Combo (Robot + Dock AutoWash™) con nuevas tecnologías de aspirado y fregado, incluyendo SealForce™ (35.000 Pa de succión y flujo tipo tornado de 20 L/s) para una limpieza de alfombras “3 veces más profunda” y ThermaMist™ para “2 veces mejor” eliminación de manchas. El sistema de fregado añade un rodillo PowerSpin™ Max Roller Mop con autolimpieza y 300 RPM, afirmando “3,75 veces más profunda” limpieza y 1,2x más cobertura por pasada, además de DriLift™ con IA para protección de alfombras. Saldrá a la venta el 2 de septiembre por 1.099 £, en línea con una mejora de producto orientada al consumidor (sin impacto financiero cuantificado en ingresos/beneficio en la nota).
Analysis
The near-term read-through is mostly sentiment, not fundamentals: a premium launch can support brand relevance and short-covering in IRBTQ, but it does not by itself solve the core issue, which is whether the company can convert product complexity into sustained gross margin and repeatable sell-through. At this price point, the bigger question is not feature superiority but whether the customer base is large enough to absorb a high-ASP device without heavy promo support.
Competitive dynamics likely tilt against mass-market vacuum players with weaker automation stacks, but the bigger second-order effect is on pricing across the category. If iRobot can defend the premium tier, it may force rivals to spend more on R&D and marketing just to hold share; if not, this becomes another evidence point that the category is commoditizing around ecosystem, service, and discounting rather than hardware specs. Compatibility with common voice assistants is table stakes, so it is unlikely to move AAPL, AMZN, or GOOGL beyond negligible ecosystem noise.
The catalyst path is 1-3 months: third-party reviews, Amazon/DTC pricing, and any signs of inventory build or discounting will matter more than the launch itself. Over 6-18 months, the thesis is falsified if unit economics deteriorate—higher warranty/returns, sluggish attach rates on the dock, or another round of markdowns. Conversely, a sustained premium mix and cleaner channel inventory would matter far more than the press-release optics.
Contrarian view: the market may be overestimating how much better hardware alone can be in a mature home appliance category. If consumers still buy on price, noise, and reliability, the launch is mostly defensive and the strategic winner is the competitor with better supply-chain scale, not the one with the flashiest spec sheet.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- IRBTQ: no high-conviction long here; treat any launch-day gap as a fade unless channel checks and review scores confirm sell-through within 2-4 weeks.
- IRBTQ: if already short, cover into strength; the event can create a 1-3 day squeeze even if the 1-3 month fundamental path is unchanged.
- Watch item: compare Amazon pricing, promo depth, and review velocity versus SharkNinja and Roborock over the next 30 days; a widening discount would falsify the premium-share thesis.
- Alert level: if IRBTQ can hold post-launch gains into the next earnings cycle while gross margin improves and inventory stays controlled, reconsider a tactical long; otherwise the launch is likely noise.
More News
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
- Chip Rout Intensifies and Tesla Showcases Flying Roadster
- All the news about the iPhone Duo
- I watched Nvidia's Jensen Huang work the room in London. He brought big checks — and a blunt message
- Alphabet stock analysis: stalled near 200-day average ahead of Q3 earnings
- iPhone Duo in Short Supply After Shipments Slip Into 2027