
Kinepolis completes acquisition of Showcase Cinemas, Expands its U.S. footprint with theatres in Massachusetts and New York
Source: PR Newswire
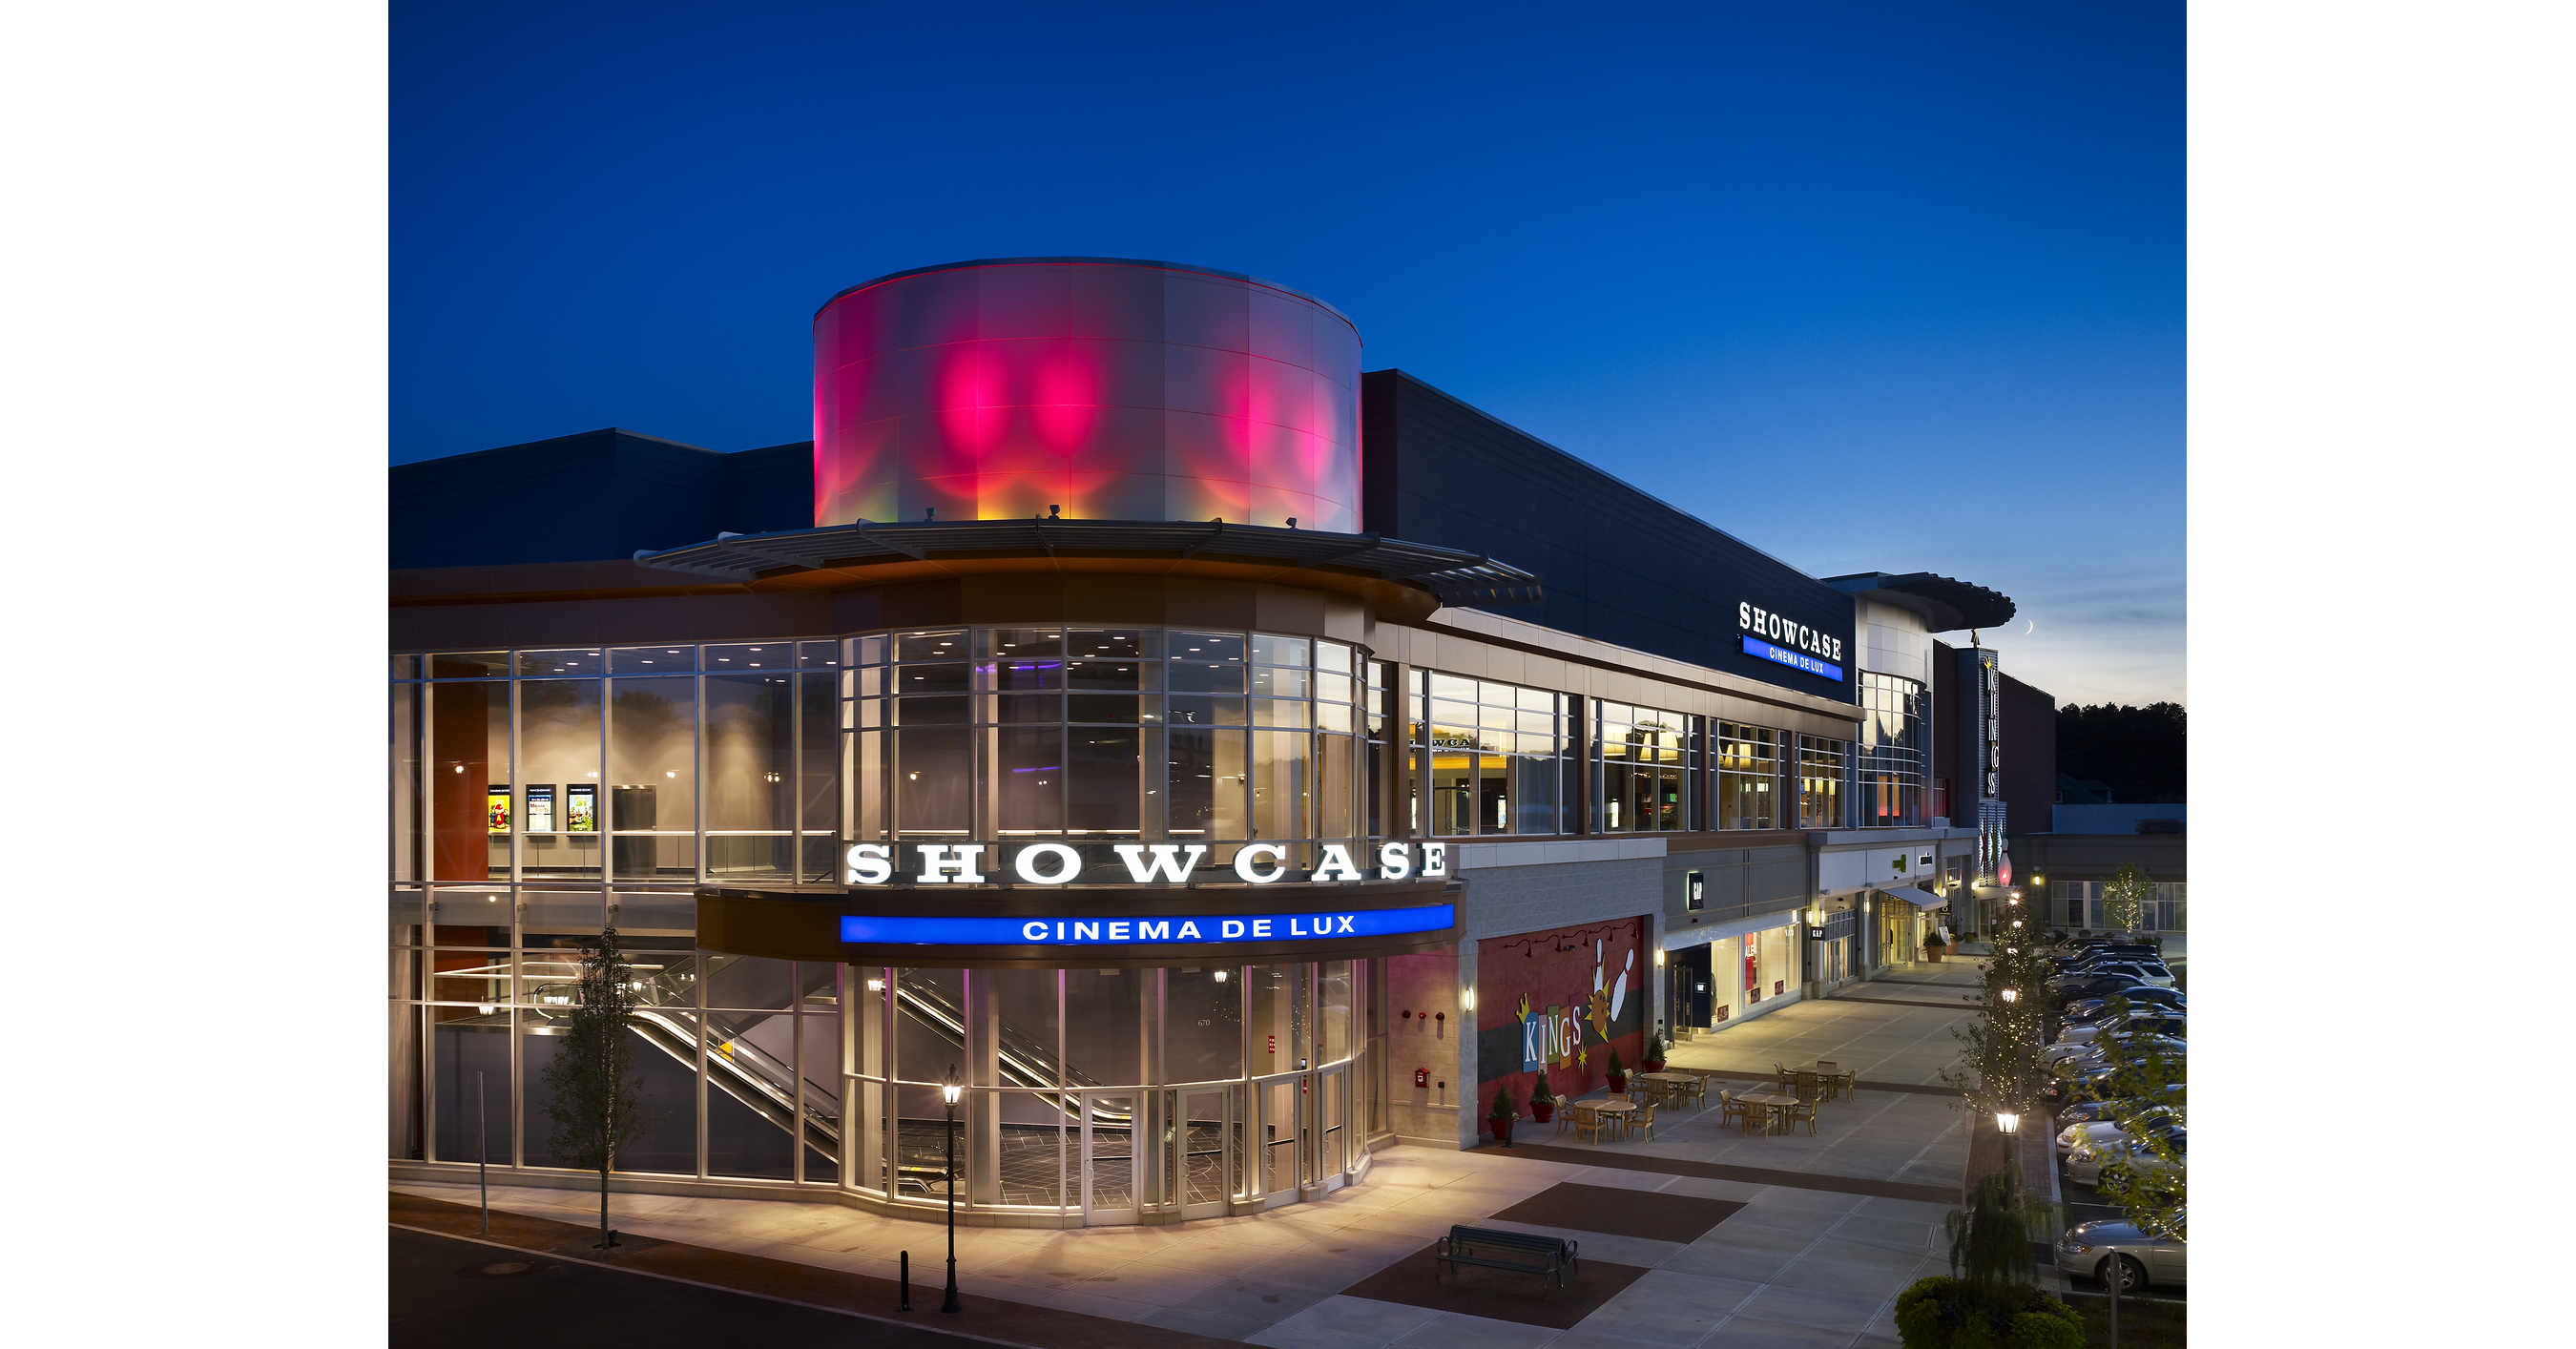
Kinepolis completed its acquisition of 13 Showcase Cinemas locations in the U.S. on September 11, expanding its U.S. presence and bringing its network to 134 cinemas, 1,474 screens and approximately 230,000 seats across nine countries. Kinepolis plans to continue operating under the Showcase name and invest in the properties, guest experience and premium offerings; executives also described the acquisition as a platform for regional growth.
Analysis
The strategic upside for Kinepolis is less the 13-site addition itself than the chance to spread procurement, programming, advertising and operating capabilities across a larger U.S. footprint while preserving local brands. But scale only creates value if acquired locations generate returns above the cost of refurbishment and integration; the release supplies no purchase price, capex plan or site-level economics. Treat claims of investment and premiumization as intentions, not evidence of near-term earnings accretion.
The transaction closed in September, so the October announcement is unlikely to be a fresh catalyst by itself. Over 1–3 months, the key evidence is whether Kinepolis discloses integration costs, planned spending and attendance or revenue trends. Over 6–18 months, successful upgrades could support higher spend per visitor and better asset utilization; the counter-risk is that premium-format capex raises depreciation and payback periods without expanding attendance, particularly if the film slate disappoints. Regional concentration also makes results more exposed to Northeast demand.
IMAX has conditional upside if Showcase upgrades include its systems, but no such commitment is disclosed; Kinepolis’ existing premium-format strategy also leaves room for competing formats. The contrarian read is that investors may overvalue the platform narrative: acquired screens do not automatically translate into pricing power or attractive returns. The thesis improves only with disclosed, measurable site investment and operating performance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- KIN: Do not chase the announcement as a standalone catalyst; it is post-close and lacks purchase-price, capex and return data. Reassess on the next results or any quantified Showcase integration update.
- Set a 1–3 month diligence alert for Kinepolis disclosures on refurbishment spending, integration costs, attendance and revenue per visitor. Without these, treat the promised premiumization as unverified.
- IMAX: Keep as a watch item, not a trade. Revisit only if Kinepolis confirms Showcase installations or a material commitment to IMAX; otherwise the incremental revenue linkage is speculative.
- Falsify the constructive KIN thesis if management indicates investment is deferred, operating performance weakens, or integration/capex costs rise without improvement in attendance or visitor spend; confirmation would require reported improvement alongside spending discipline.
More News
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- Wall Street Week | Michigan Manufacturing, AI Debt Investments, Baby Bonds, Canadian Coal Fight
- OpenAI's revenue scare, Delta earnings, what investors think of a Starbucks-Chipotle deal and more in Morning Squawk
- Tesla drops 'Full Self-Driving' brand name in Europe after regulator pushback
- SpaceX makes big move into wireless. These once 'obsolete' tech stocks could benefit
- Why is T-Mobile stock tumbling today?