
Tiger Group and Can-Am Machinery Set Oct. 8 Live Webcast Auction for Total Fiber Recovery Equipment
Source: PR Newswire
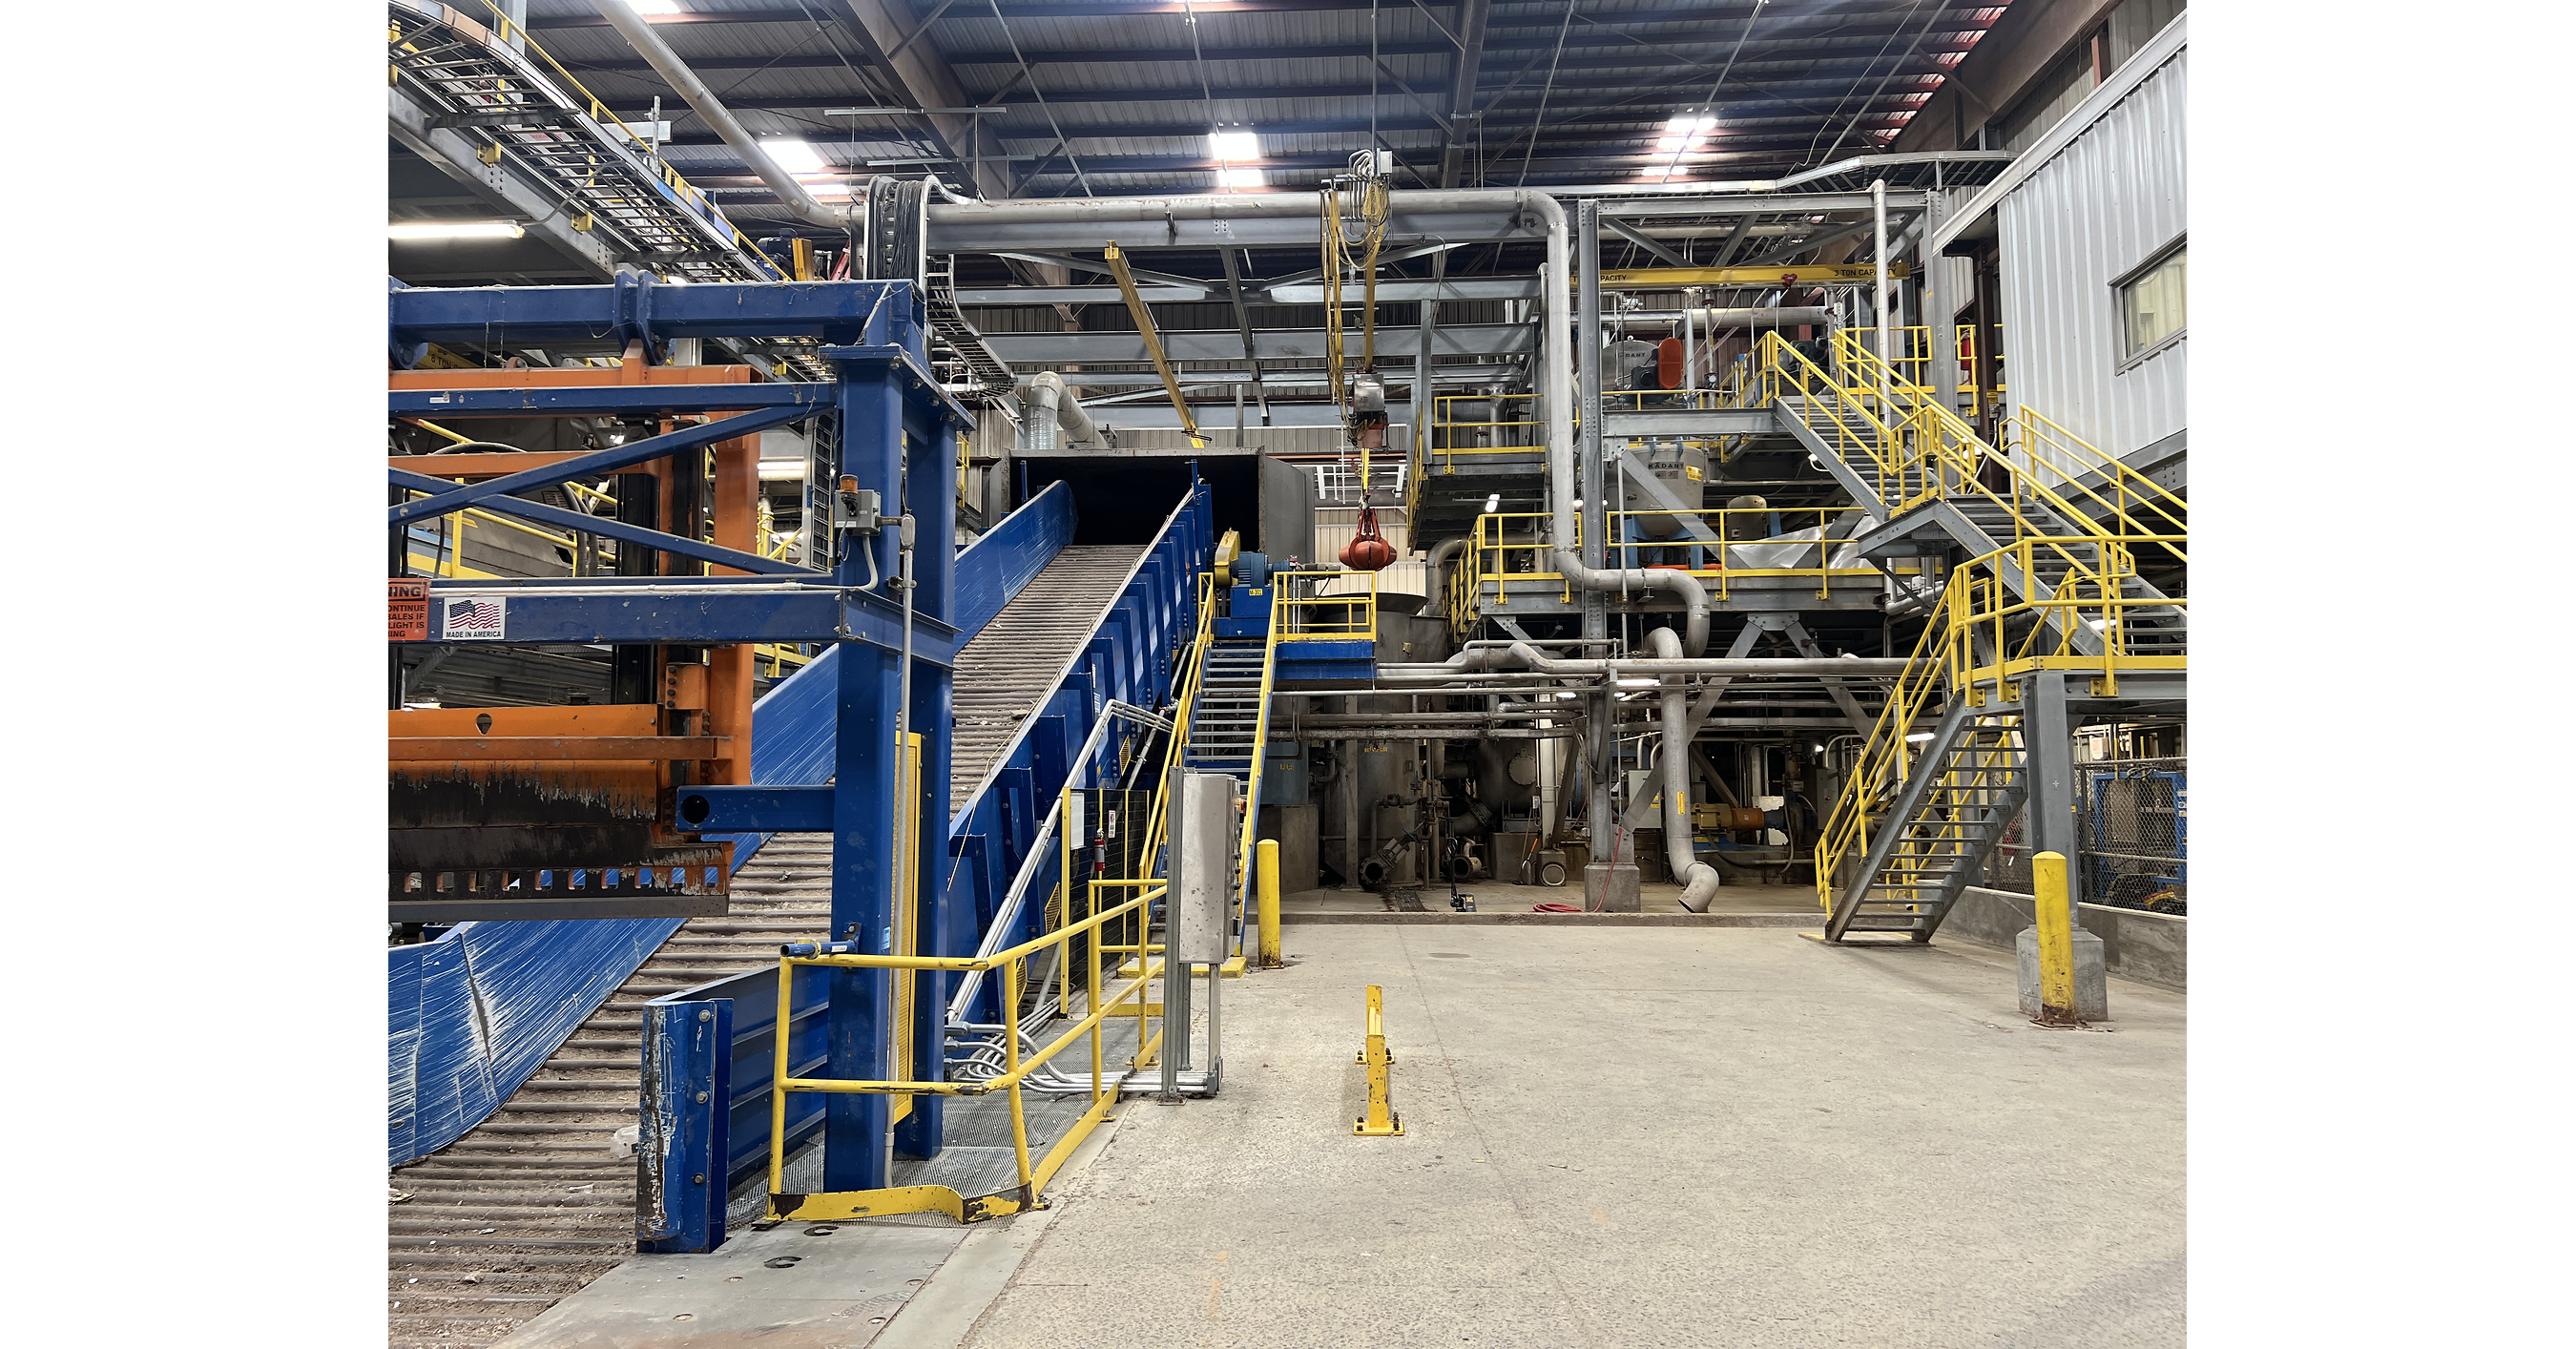
Tiger Group and Can-Am Machinery will auction Total Fiber Recovery's recently commissioned 600-ton-per-day OCC recycled-pulp facility on Oct. 8, while accepting advance offers for a turnkey acquisition or major systems. The Chesapeake plant, designed to produce up to 200,000 metric tons of unbleached recycled pulp annually, halted operations shortly after commercial production began because of funding challenges. The sale includes late-model pulping, drying, baling and packaging equipment and benefits from proximity to the Port of Norfolk.
Analysis
This is primarily a secondary-market price-discovery event, not an operating read-through for Kadant (KAI). Unless KAI discloses receivables, warranty reserves, or a meaningful service-contract exposure tied to the project, the asset sale should not alter consensus revenue or EPS. The more relevant signal is that recently delivered recycled-fiber capacity can fail before ramping: lenders and prospective greenfield developers may apply higher completion-risk discounts to comparable projects, delaying equipment orders rather than impairing the installed base.
A turnkey sale at a material discount to replacement cost could create a 6-18 month supply-side overhang for independent recycled-pulp projects. A buyer that relocates or restarts the line gains low-cost capacity, potentially pressuring regional OCC procurement and recycled-pulp margins; conversely, piecemeal liquidation removes a potential competitor and is modestly constructive for existing operators. The Port of Norfolk location raises the probability that the assets attract an export-oriented buyer, but freight economics and OCC price spreads—not equipment availability—will determine whether capacity is restarted.
The near-term equity implication for KAI is neutral: aftermarket parts and service revenue could eventually accrue if a credible operator recommissions the line, but this is too small and too uncertain to underwrite a position. The contrarian point is that the auction outcome may be more informative about financing conditions for circular-economy industrial projects than about recycled-fiber demand. A low realized value or absence of a turnkey bidder would reinforce a tighter-capital narrative for smaller projects over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- No standalone KAI trade on this announcement; maintain existing exposure only. Require disclosure of contract value, receivable/write-down exposure, or a restart/service agreement before changing earnings assumptions.
- Set an Oct. 8 event alert: a turnkey buyer at a credible valuation and stated commissioning plan would be a modest positive watch signal for KAI's aftermarket opportunity over 6-18 months, not an immediate catalyst.
- For a broader industrial-capex book, treat a failed turnkey process or deeply discounted equipment outcome as confirmation to avoid speculative positions in small recycled-materials project developers for the next 1-3 months; the thesis is falsified by multiple financed restart or greenfield commitments.
- Monitor OCC prices, export freight rates, and announced recycled-pulp offtake contracts. A sustained improvement in these economics alongside a restart announcement would shift the risk from stranded-asset liquidation to incremental regional supply and margin pressure for exposed pulp producers.
More News
- Italy to deploy warships to protect shipping through Bab al-Mandeb
- Oil prices fall as Saudi supply hopes outweigh fresh Houthi strikes
- Oil prices fall for 3rd day as supply concerns ease, diplomacy in focus
- Oil Traders Stymied by Iran War Stalemate: Evening Briefing Americas
- California AG Says Paramount-WBD Merger Would Hurt the State
- Saudi Pivots Oil Routes After Pipeline Attack