
Merritt Properties Begins Third Phase of Imeson Landing Business Park, Advances Gate Parkway Redevelopment
Source: PR Newswire
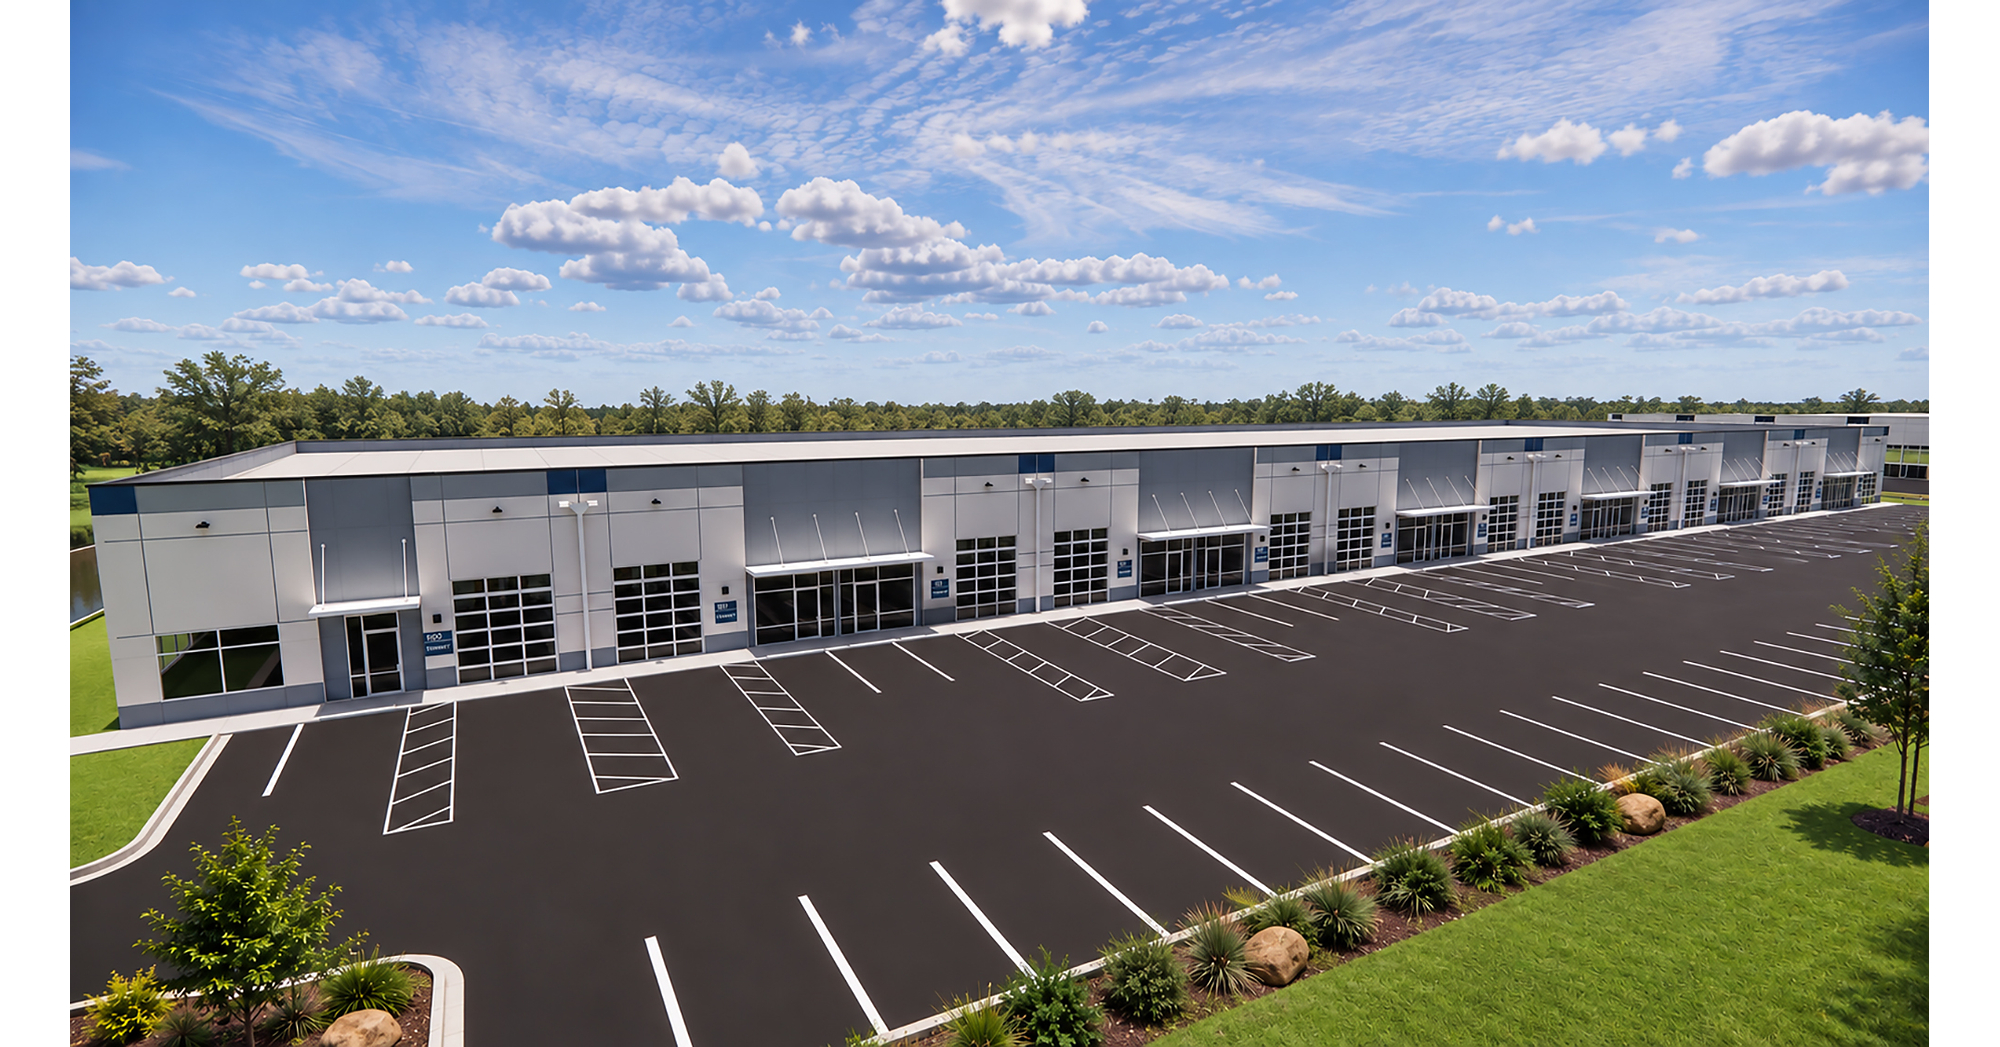
Merritt Properties began phase three of Imeson Landing Business Park in north Jacksonville, adding three light-industrial buildings totaling 126,500 square feet and bringing the park's total footprint to 392,700 square feet. The project, scheduled for Q2 2027 completion, reflects continued demand for flexible industrial space and adds 1,650-square-foot incubator units for smaller businesses. Merritt is also redeveloping two vacant Gate Parkway office buildings into multi-tenant industrial space after the first redevelopment phase became fully leased.
Analysis
This is not a material fundamental catalyst for JLL: any incremental agency commissions are immaterial relative to its global capital-markets and workplace-services earnings base. The more relevant read-through is that developers are still allocating capital to shallow-bay product despite a higher-rate financing environment, implying perceived tenant demand and replacement-cost support for infill flex rents. That favors industrial landlords with meaningful small-tenant exposure, but only if local vacancy remains contained; this developer-sponsored announcement does not independently verify absorption, achieved rents, or development yield.
The second-order risk is supply fragmentation. Small-bay users are less creditworthy and more sensitive to local business formation, freight activity and financing costs than large distribution tenants, so a weakening regional economy can produce faster rollover and concession pressure even while headline industrial vacancy looks stable. Office-to-industrial conversion can also create economically rational competing supply because the basis is often below ground-up replacement cost, limiting rent upside for existing flex owners over the next 12-24 months. Near term, treat this as a local demand watch item rather than a tradable public-equity signal; the key catalyst is Jacksonville submarket vacancy, net absorption and asking-rent data over the next two quarterly reporting cycles.
Contrarianly, investors may over-extrapolate any continued construction activity into broad industrial strength. Smaller-format industrial can remain resilient while bulk warehouse economics deteriorate, meaning PLD and FR should not be assumed to receive the same benefit as local flex-oriented assets. A sustained rise in concessions or vacancy above local historical norms would expose development pipelines to lower stabilized NOI and higher cap-rate assumptions, producing NAV pressure before it is visible in reported same-store results.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone JLL position: maintain neutral exposure through the next earnings report; underwrite JLL on transaction volumes, leasing revenue and fee-margin recovery rather than this isolated assignment. Reassess only if management identifies broad Southeast leasing acceleration or raises guidance.
- Create a 1-3 month watchlist for PLD and FR rather than buying on this news. Add only if quarterly Jacksonville/northern Florida industrial data show positive net absorption with stable-to-lower concessions; a vacancy increase of roughly 150-200 bps or meaningful rent deceleration would invalidate the favorable demand read-through.
- For existing industrial REIT longs, favor balance-sheet quality over development leverage: PLD is the defensive expression versus smaller, higher-development-beta owners. Hedge broad rate risk with a modest short VNQ or IYR only if 10-year Treasury yields break materially higher and industrial REIT implied cap rates fail to adjust.
- Monitor JLL's disclosed leasing pipeline and capital-markets backlog at the next two earnings releases. A guidance raise tied to recurring leasing/workplace services—not one-off transaction revenue—would be the actionable confirmation for a 6-12 month long thesis.
More News
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Latest Oil Market News and Analysis for Sept. 22
- Oil Settles Near $100 as Hormuz Flows Stunt Rally
- +17% in a single session: This AI-picked stock catches a data-center breakout
- Perpetual underdog AMD nips at Nvidia's heels as it joins the $1T club