
ECS Jets Adds a Cirrus Vision Jet G3 in Palm Beach as CEO Earns His Type Rating
Source: PRWeb
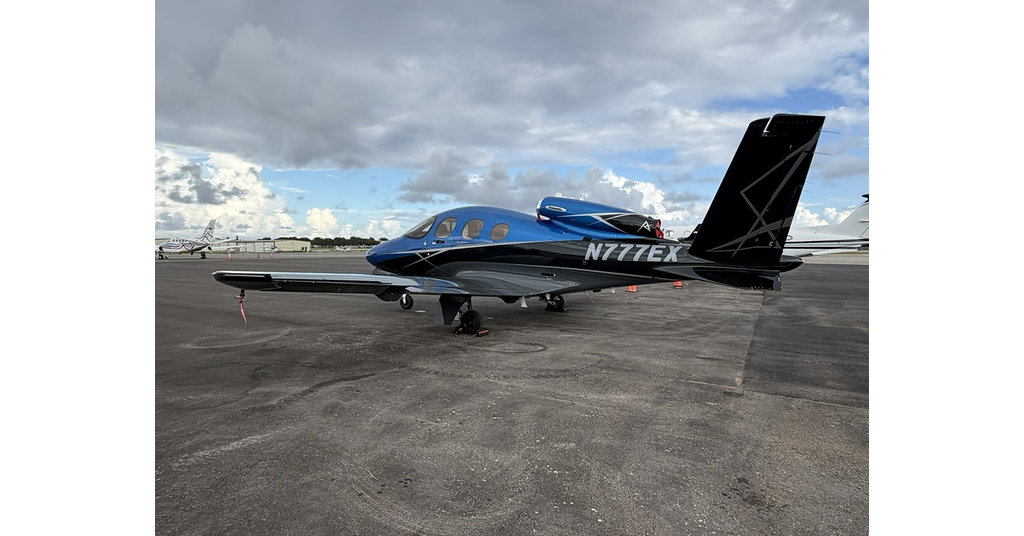
ECS Jets announced it owns one new Cirrus Vision Jet G3, N777EX, based in Palm Beach, and has hired a full-time captain. The aircraft is currently for company use only; ECS aims to add it to a Part 135 certificate, which could enable charter service, but no timeline was stated.
Analysis
This is an operational option, not yet a charter-revenue catalyst. Until N777EX is approved under a Part 135 certificate, its disclosed use is internal; any near-term benefit would need to come indirectly through client acquisition or partner retention, neither of which is quantified. Even after approval, one aircraft offers limited capacity and creates a single-asset failure point: maintenance downtime or crew availability could erase the intended AOG coverage precisely when partners need it. The more important test is whether ECS can convert the aircraft into incremental, repeatable charter demand without displacing higher-return uses of management and capital. Cirrus may gain a reference customer, but this announcement alone is not evidence of meaningful manufacturer demand. There is no obvious public-equity expression: ECS is private, and a position in broad aviation names would dilute the signal. Over the next 1–3 months, verify Part 135 approval, actual charter availability, and whether ECS discloses utilization or partner commitments. Over 6–18 months, sustained utilization and customer conversion would support the strategic case; continued company-only use would leave the aircraft as a cost and client-service tool rather than a new revenue stream. The optimistic framing overstates what can be inferred from ownership and a stated future goal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No direct trade: the announcement concerns a private company and does not establish material, measurable earnings exposure for a listed issuer.
- Treat Part 135 authorization as the first catalyst to monitor, not as proof of attractive economics; confirm the aircraft is actually available for charter after approval.
- Track utilization, charter hours, partner AOG deployments, and incremental client wins. If company-only use persists or deployment is repeatedly constrained by maintenance or crew availability, the revenue-option thesis weakens.
- Avoid extrapolating Cirrus demand from this single aircraft purchase; reassess only if subsequent orders or independently verifiable delivery data indicate broader demand.
More News
- SK Hynix shares slide after chipmaker scraps Solidigm IPO plans
- Apple’s iPhone Duo Hits Stores in Face of Short Supply and High Demand
- OpenAI nears up to $30 billion funding round at $1.25 trillion valuation led by UAE investors
- Moderna shares plunge after leak of partial cancer vaccine data
- SpaceX records $561 million investment gain from stake in Elon Musk's Boring Co.
- Iran reveals ‘offensive’ doctrine, US issues alert: Is war imminent?