
Haier объявляет о глобальном партнерстве с Лигой чемпионов УЕФА
Source: PR Newswire
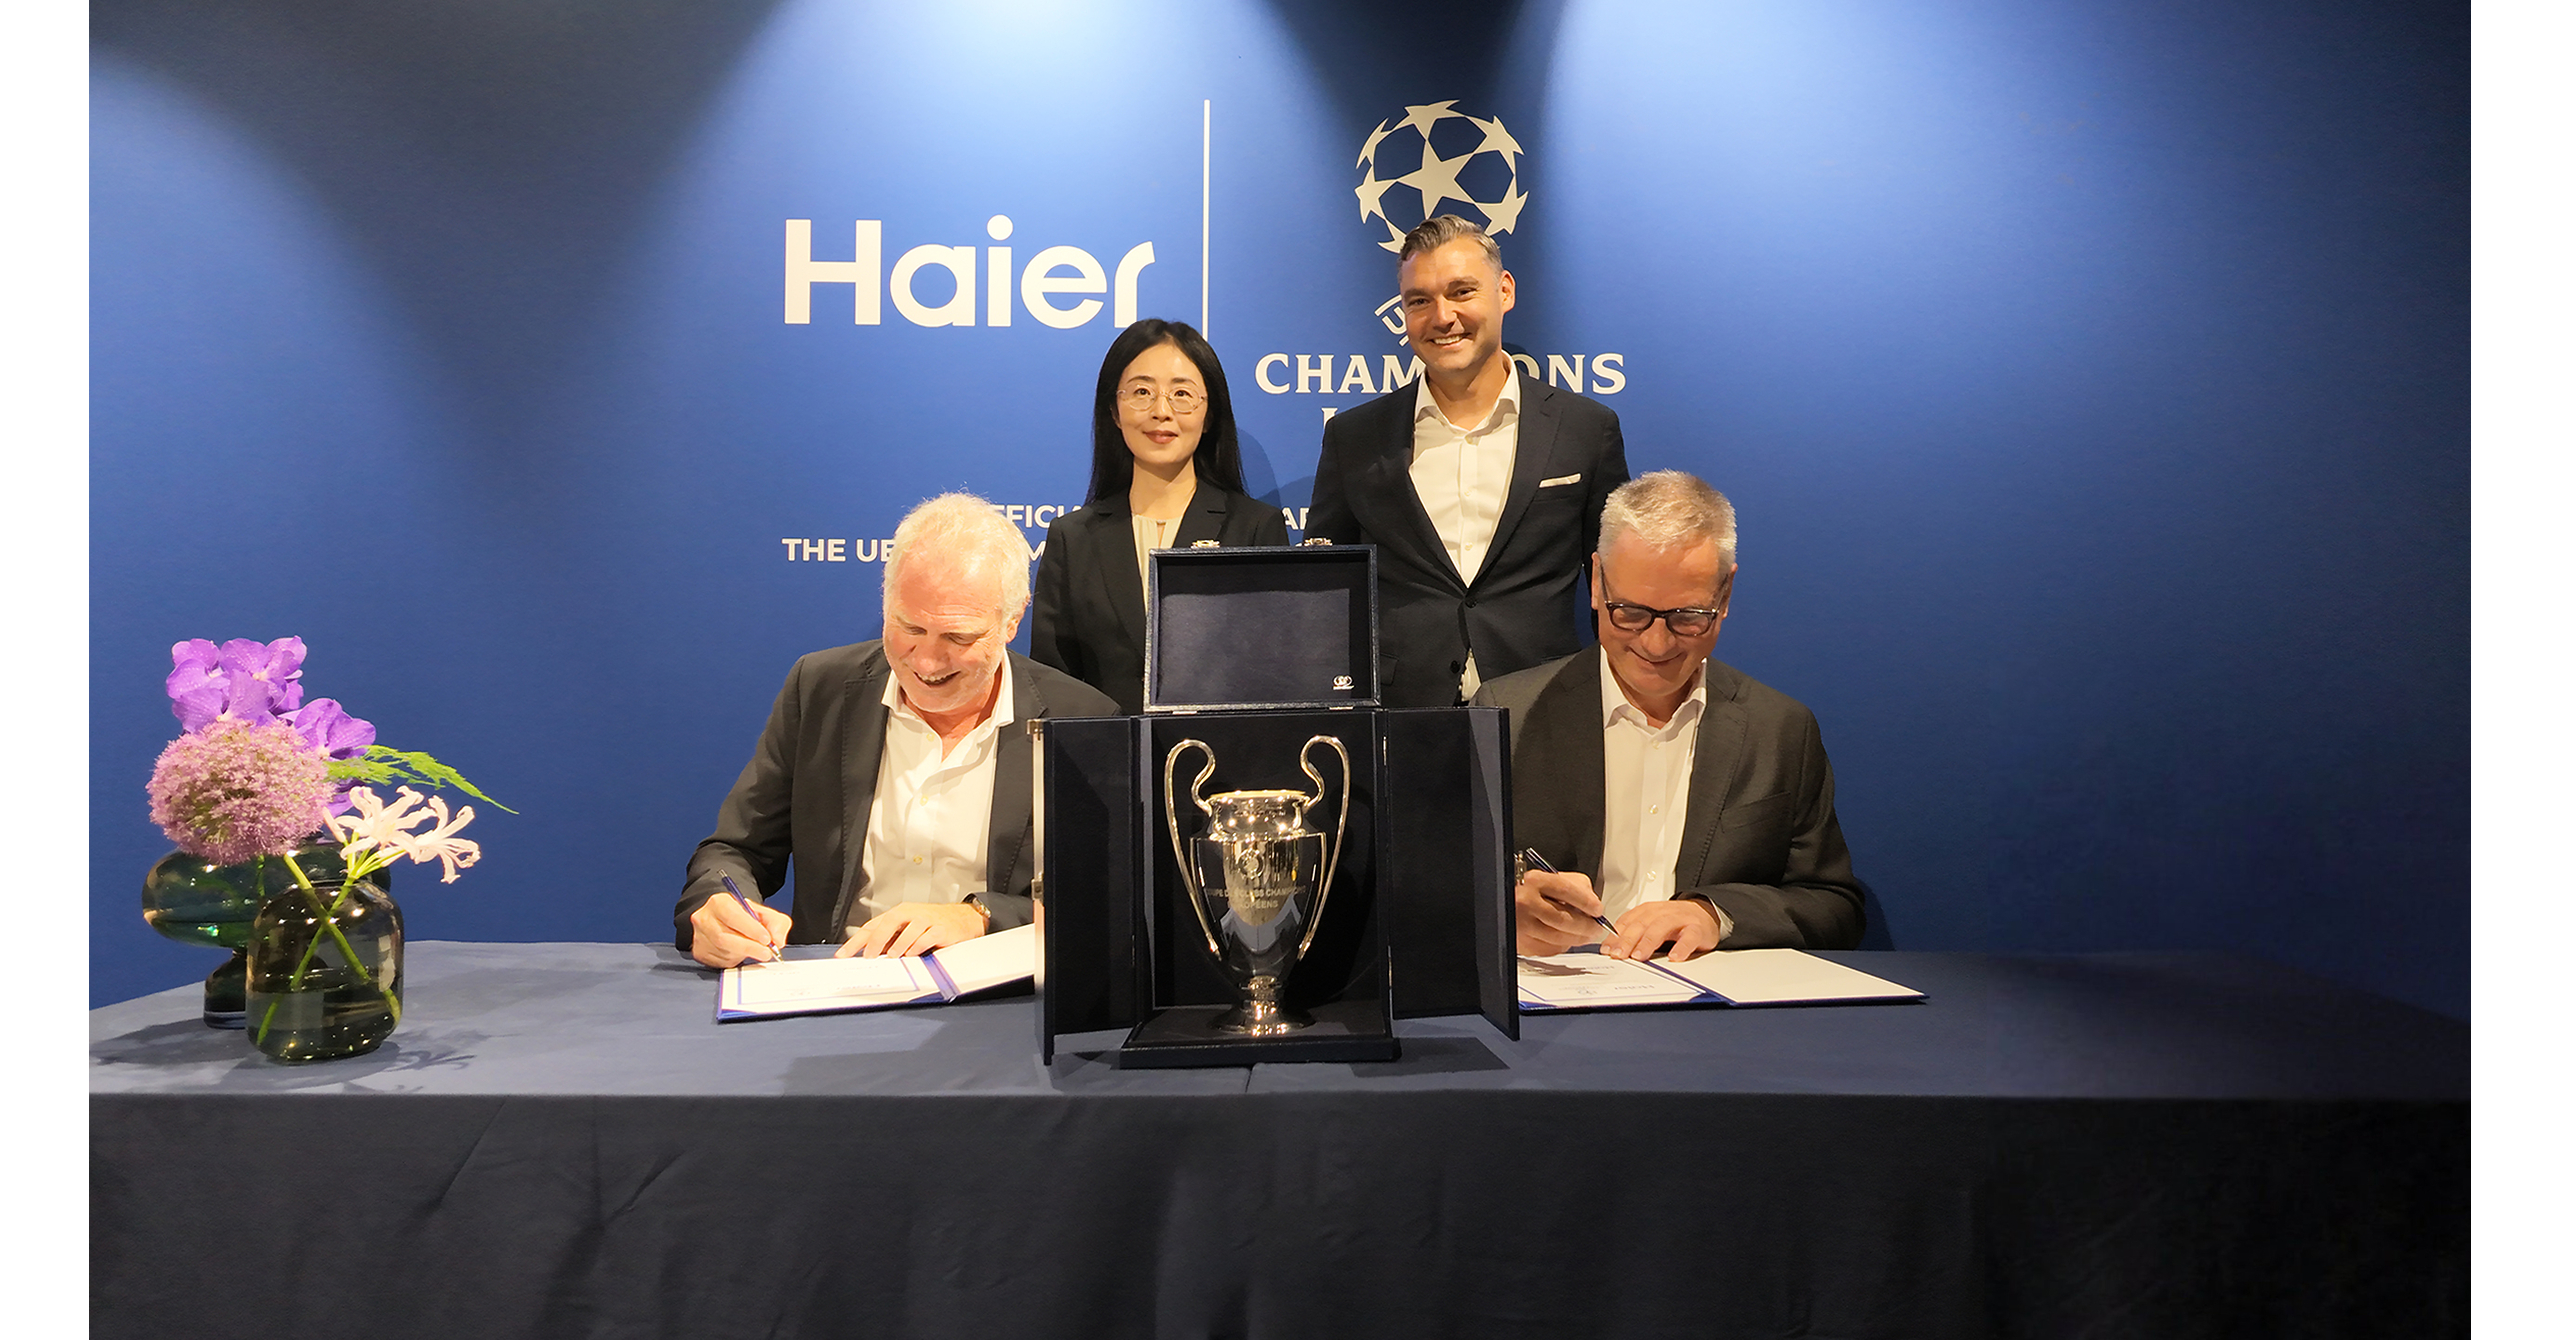
Haier объявила о глобальном партнерстве с UC3: с сезона 2027/28 по 2030/31 компания получит эксклюзивные всемирные права на бытовую технику, телевизоры и коммерческие экраны в ряде клубных соревнований УЕФА, включая Лигу чемпионов. Пресс-релиз подчеркивает смещение фокуса от простого спонсорства к углублению связей с потребителями с опорой на «интеллектуальные технологии». Новость в первую очередь маркетингово-брендовая и, вероятно, окажет ограниченное краткосрочное влияние на рынки.
Analysis
This is more of a brand-capital allocation signal than a near-term revenue catalyst. For HSHCY, the economic value shows up only if the sponsorship lifts premium mix, retailer leverage, and consumer consideration in Europe/LatAm over several refresh cycles; that matters because appliance gross margin is driven more by ASP and channel power than unit growth. The spending itself is likely to be treated as SG&A/marketing, so the first-order P&L impact is negative or neutral before any sales uplift appears.
The competitive read-through is more interesting: Haier is signaling it wants to compete with Samsung, LG, Whirlpool and Electrolux on brand salience, not just cost or distribution. If this works, the second-order effect is pressure on incumbents to maintain sports-marketing budgets, which can quietly compress operating margin across the category without changing industry share immediately. It also fits a broader move from white-goods manufacturing toward an ecosystem pitch, which could help TVs, connected-home and commercial display adjacencies more than core washers and refrigerators.
Timing matters: the rights start far enough out that the stock should not re-rate much on this announcement alone. The main falsifier is if 2026-2027 Europe demand stays weak or if Haier’s premium positioning fails to show up in mix/margin; then the spend reads as vanity rather than competitive investment. Contrarian take: the market may be overestimating the sponsorship halo and underestimating how little sports branding changes a low-consideration purchase unless Haier also improves service, financing and installer relationships.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No immediate event trade in HSHCY; treat this as a watch item and wait for evidence in 2026 guidance that Europe mix or gross margin is inflecting before taking risk.
- If forced into a relative-value expression, favor a small long HSHCY / short WHR pair over a 3-6 month horizon only on confirmation that Haier’s overseas margin is improving; thesis is brand-led ASP support versus Whirlpool’s weaker pricing power.
- Do not buy the headline with options: the catalyst is too far-dated for near-term convexity. If HSHCY rallies into the announcement, fade strength unless management later quantifies incremental EBIT from the sponsorship.
- Set an alert on HSHCY for any disclosed step-up in marketing spend or Europe channel inventory in the next 2-4 quarters; a spend spike without share gains would be a negative signal for ROIC.
- Watch European appliance peers ELUXY and WHR for budget response. If they increase promotional intensity or brand spend into 2026, expect category margin pressure before any measurable share loss.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Indonesia Said to Meet Monday With MSCI Over Shock Index Threat
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance