
La solución NG WAN de Huawei entra en fase de uso comercial a gran escala
Source: PR Newswire
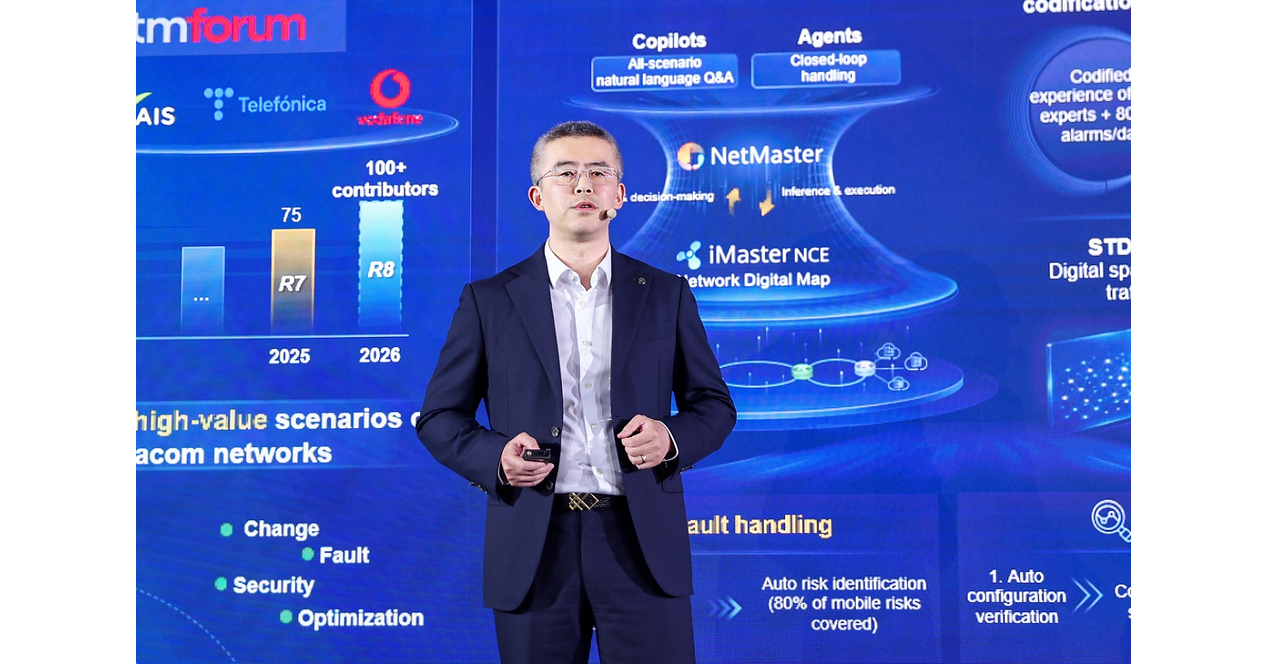
Huawei says its NG WAN solution has entered large-scale commercial use, with more than 60 operators worldwide deploying it. The company cites security and efficiency metrics including detection of over 95% of threats, 90% lower DDoS risk, and more than 7% higher AI training and inference throughput. Huawei also says one Chinese operator cut hospital computing costs by 30% and increased private-line ARPU fivefold; these are company-reported results.
Analysis
The commercial signal matters more as a potential vendor-share and pricing shift than as proof of a new industry-wide spending cycle. If operators can sell differentiated secure, low-latency enterprise connectivity, network upgrades may support higher-value private-line and AI workloads; however, this could be a relabeling or replacement of existing capex rather than incremental demand. Huawei’s bundled hardware, software and automation could pressure Cisco, Nokia and HPE’s networking businesses where it is eligible to compete, while raising the bar for operators’ incumbent vendors. The counterweight is geopolitical procurement risk: restrictions and security reviews can limit addressable markets and make multi-vendor deployments more likely.
Near term, treat the release as vendor marketing, not an earnings catalyst: the performance, cost and revenue figures are company-reported or single-customer examples, without disclosed contract values, deployment economics or independent validation. Over 1–3 months, watch named operator awards, procurement eligibility, and whether competitors respond with pricing or equivalent product claims. Over 6–18 months, the key question is whether AI-network demand produces incremental operator revenue and returns on capex, rather than merely shifting equipment share.
Contrarian read: broad adoption claims may overstate commercial scale if deployments are pilots, limited to Huawei-friendly markets, or not yet monetized. Conversely, the combination of network automation and enterprise AI transport could be underappreciated if operators can demonstrate repeatable revenue uplift. No clean listed-equity exposure is established by the supplied data; avoid inferring an earnings impact for any named competitor. Falsify the bearish competitive-pressure view if competitors retain awards and pricing while Huawei deployments remain geographically constrained; falsify the bullish monetization view if operator disclosures show no incremental enterprise revenue or returns.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No immediate directional trade: Huawei is not mapped to a listed ticker here, and the release provides no independently verified contract values or consolidated financial impact.
- Add Cisco, Nokia and HPE networking to a 1–3 month competitive watchlist; look for procurement awards, pricing commentary and any change in order growth before taking a relative-value position.
- Treat operator AI-network capex as a conditional thesis, not a sector-wide long: require evidence in operator results of incremental enterprise connectivity revenue and capex returns.
- Escalate the risk if Huawei announces material deployments in markets where it can compete and incumbent vendors report weaker pricing or lost awards; downgrade the thesis if deployments remain pilots or restricted to a narrow set of markets.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- Why is Samsung Electronics stock plunging today?
- SK Hynix plunges 8% amid Asia tech rout as Fed rate hike fears, AI funding worries mount
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)