
Carl's Jr.® Is Coming for the King's Crown and Inviting Fans to Trade It for a Better Burger
Source: PR Newswire
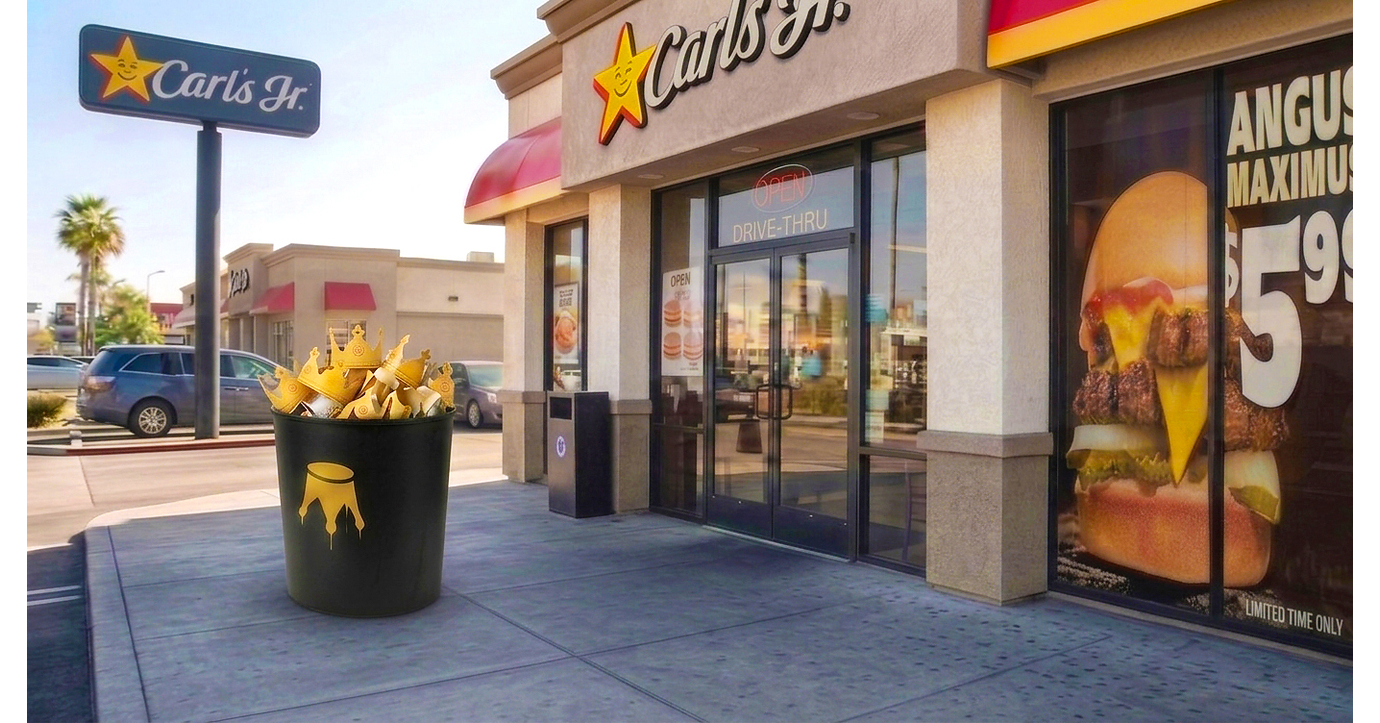
Carl's Jr. launched its limited-time "Stealing the Crown" promotion, offering the first 100 eligible My Rewards members a free Angus Maximus burger for submitting a competitor receipt or crown image through September 25. The $5.99 Angus Maximus, featuring two 100% Angus patties totaling 5.7 ounces, is the first Burger Revolution LTO and supports the chain's cooked-to-order positioning. The campaign is a targeted loyalty and product-marketing initiative with limited near-term financial significance.
Analysis
This is not investable competitive data: the redemption pool is immaterial and the campaign is primarily a low-cost loyalty-acquisition and social-engagement test. The more relevant signal is the operational claim behind it: made-to-order positioning can support ticket and brand differentiation only if franchisees absorb incremental labor, throughput, and food-waste costs without damaging peak-period service times. CKE is private, eliminating a direct equity expression.
The public read-through is modestly negative at the margin for Restaurant Brands International (QSR), specifically Burger King, because the creative explicitly targets its brand iconography and seeks to frame quality as a weakness. But there is no evidence that a one-week, tightly capped promotion can move QSR traffic, franchisee economics, or U.S. same-store sales. McDonald's (MCD), Wendy's (WEN), and Jack in the Box (JACK) face the same premium-value battlefield, yet their valuation drivers remain traffic, value architecture, labor inflation, and digital mix rather than isolated promotional messaging.
Over 1-3 months, watch whether Carl's Jr. extends the offer and reports a broader cooked-to-order rollout; sustained execution would raise the probability of competitors increasing premium-burger discounting, compressing restaurant-level margins across regional QSR. The contrarian view is that made-to-order is a capacity constraint rather than a moat: if drive-thru times deteriorate, the proposition loses its highest-frequency customer and franchisee resistance becomes the binding constraint. No trade is warranted absent independent evidence of traffic share shift or competitor promotional response.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No directional position on this release; CKE is private and the promotion's limited redemption capacity is economically irrelevant to public QSR earnings.
- Set a 1-3 month monitoring alert for QSR U.S. Burger King comparable-sales commentary, app offer intensity, and franchisee margin disclosures. Consider a tactical short only if BK responds with sustained premium-burger discounting and QSR guides to incremental promotional spending; falsify on stable or improving U.S. restaurant margins.
- Monitor WEN and JACK quarterly traffic, drive-thru service metrics, and restaurant-level margins as higher-beta indicators of premium-burger promotional pressure. A long MCD / short JACK relative-value expression becomes more attractive only if industry discounting accelerates, given MCD's scale purchasing, digital reach, and stronger franchisee unit economics.
- Track beef prices and hourly labor inflation over the next 6-12 months. A renewed upswing in either input would make cooked-to-order premium-value offers margin-dilutive and favor scaled operators with superior procurement leverage, particularly MCD and QSR, over smaller burger-focused peers.
More News
- Paramount agrees invest $1.5 billion in domestic movies and create a board for editorial independence at CNN, CBS as part of deal for Warner Bros.
- World Leaders Converge on United Nations General Assembly
- Paramount and state AGs will settle lawsuit, allowing Warner Bros. merger to proceed, reports say
- How a Bangladeshi garment-maker is fighting the Middle East energy crunch
- Paramount Set to Settle Lawsuits, Clearing Way for Warner Bros. Deal
- Paramount settles with US states in step towards merger with Warner Bros