
BUUU Group Limited signe un accord définitif en vue d'acquérir une participation majoritaire dans Brightray Science Inc. et de lever plus de 60 millions de dollars américains par le biais de placements privés, faisant ainsi de la fourniture de centres de données dotés d'une IA industrialisée son principal moteur de croissance
Source: PR Newswire
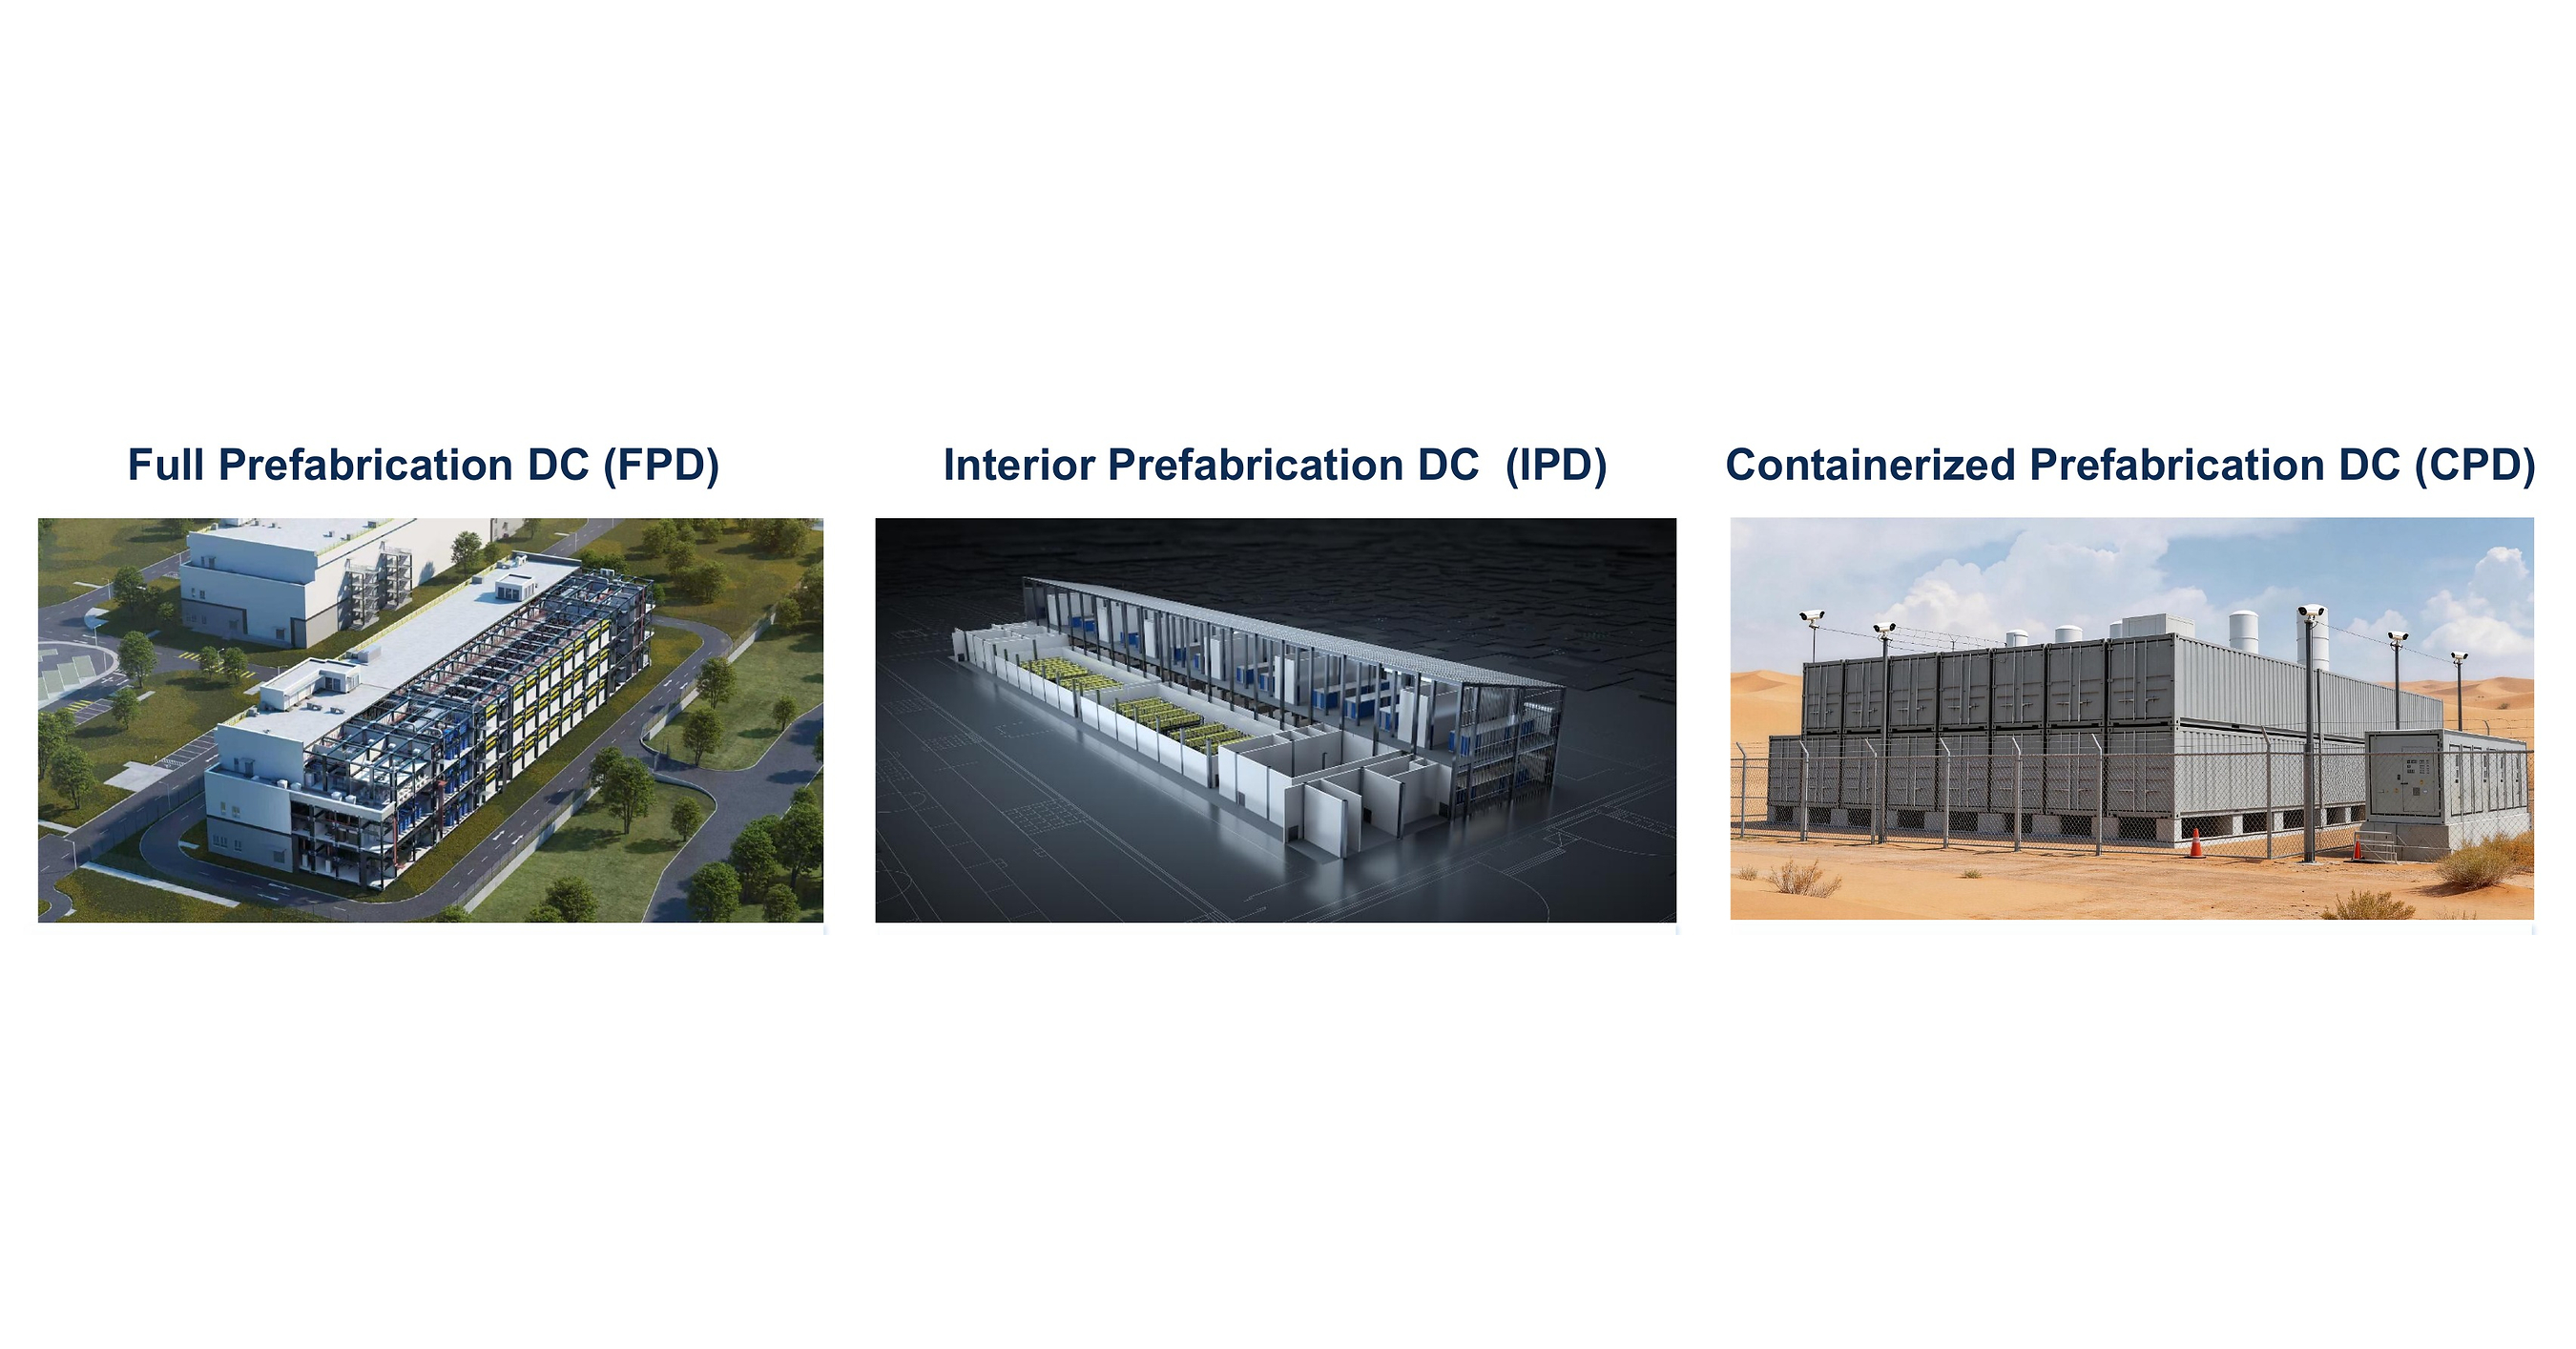
BUUU Group will acquire a 60% stake in Brightray Science for a mix of newly issued BUUU Class A shares priced at $20/share plus a convertible note for up to 10M additional shares, with purchase contingent on Brightray’s audited net income (and an effective ownership cap of 19.99%). Alongside the deal, BUUU is raising gross proceeds of $60M+ via private placements to fund capacity expansion and working capital, targeting ~1 GW of deliveries over the next three fiscal years and a ~2 GW project pipeline (~$9B contract value potential). Delivery timelines are claimed to be cut from 18–36 months to 6–9 months (with 70 MW in service in Johor, Malaysia and a plan to scale further), indicating a material growth lever tied to modular AI data centers.
Analysis
The economic value here is not the press release itself; it is the attempt to reprice a labor- and power-constrained buildout into a capital-light, repeatable manufacturing model. If the modular approach is real, the margin pool shifts away from traditional EPC and bespoke construction toward whoever controls standardized power, cooling, and commissioning workflows. The immediate market issue is dilution: a financing-heavy pivot means existing holders are effectively paying for the option that execution scales.
For the semiconductor names, the read-through is positive but not immediate. Faster deployment improves conversion of AI capex into installed capacity, which is supportive for NVDA and, to a lesser extent, AMD, but it does not automatically create incremental silicon demand unless the end customer has secured power, permits, and financing. The more direct beneficiaries are the supply-chain adjacencies not named here: electrical equipment, liquid-cooling, and module fabricators; the losers are slow-cycle developers whose projects get compared against a six-to-nine-month benchmark.
The contrarian point is that the market may be overestimating the probability-weighted value of the pipeline while underweighting integration risk. The disclosed backlog looks closer to an option book than contracted revenue, and the economics can unravel quickly if third-party certification, project financing, or customer prepayments lag. Falsifiers are straightforward: a delayed close, weaker-than-expected cash conversion in the next 1-2 quarters, or any evidence that the 2 GW pipeline is not translating into signed, financeable orders.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing BUUU after the headline; wait for PIPE close and a first-quarter update showing actual revenue conversion, not just pipeline language. Risk/reward is unfavorable until dilution clears and execution is independently visible.
- If borrow is available, consider a small relative-value short BUUU vs long NVDA over 1-3 months: the market may overpay for the integrator while the higher-quality compounder captures the cleaner AI capex beta. Cover if BUUU demonstrates financing discipline and two consecutive periods of improving cash collection.
- Maintain NVDA as the cleaner expression of AI infrastructure spend rather than BUUU; any pullback tied to this news should be viewed as a better entry than a momentum chase in the small-cap builder. Falsify the thesis if data-center supply constraints ease materially and OEM order growth slows.
- Treat AMD as a watchlist name only: incremental benefit is real but second-order unless third-party qualification wins broaden across modular/liquid-cooled architectures. Prefer to buy only on weakness or after independent confirmation of design wins.
More News
- The next AI race will be won at the credit desk
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- TechCrunch Mobility: Rivian’s next act
- The Bond Market Is Sending a Warning to Nvidia Shareholders
- Taiwan Semiconductor Just Proved Why It's a Top AI Investment
- What to Expect in Markets This Week: Meta, Tesla Report; Airlines, Streaming Giants' Results Due
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Investment Research Platform?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?