
PharmaResearch Officially Launches REJURAN in Hungary, Expanding Its Presence in Europe
Source: PR Newswire
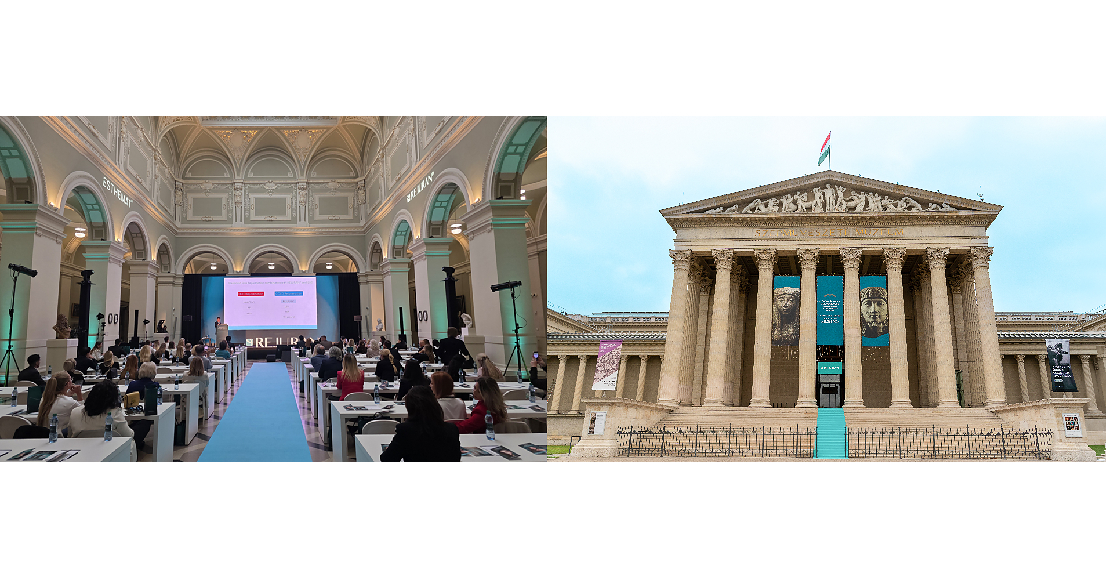
PharmaResearch launched its PN-based REJURAN portfolio in Hungary on September 14, expanding the Korean skin-booster brand's European footprint. The Budapest symposium drew about 100 aesthetic medicine professionals, and the company will distribute REJURAN, REJURAN I and REJURAN S through a local partner while building a network of clinics and trained physicians. The launch targets growing Hungarian demand for natural-looking, low-downtime aesthetic treatments, but no financial contribution or sales outlook was disclosed.
Analysis
This is strategically supportive of PharmaResearch (KOSDAQ: 214450) but not yet an earnings-moving event. Hungary is a small, fragmented aesthetics market, and a physician-education-led rollout implies a slow conversion cycle: initial distributor sell-in may appear within 1-3 months, while recurring clinic ordering and evidence of pricing power should be assessed over 2-4 quarters. The more relevant signal is whether European expansion can diversify REJURAN from Korea without materially raising selling and marketing expense or creating distributor-led inventory volatility.
Competitive pressure should fall primarily on lower-priced skin-booster and mesotherapy suppliers rather than entrenched botulinum toxin or HA filler franchises. The key commercial risk is that PN treatments remain an elective, cash-pay category; weak European consumer demand or insufficient physician ROI could force promotional spending and undermine the premium positioning required for overseas margins to match domestic profitability. A broader European regulatory or reimbursement shift is unlikely to be a near-term catalyst because adoption is driven by clinic economics, training capacity and repeat-treatment rates.
Consensus may overvalue geographic footprint announcements relative to measurable utilization. The stock should only receive a durable multiple premium if management demonstrates overseas revenue growth exceeding incremental SG&A, stable distributor receivables, and repeat order behavior rather than one-time launch stocking. Falsification of the constructive structural view would be overseas growth below company guidance for two consecutive quarters, rising inventory/receivables, or gross-margin compression indicating discounting.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate trade: treat the launch as a monitoring event rather than a catalyst, given the low near-term financial materiality and absence of disclosed Hungarian sales targets, pricing, or distributor minimum-purchase commitments.
- For investors able to trade Korea, place KOSDAQ: 214450 on an earnings-watch list for the next 2-4 quarters; consider a long only if overseas revenue growth accelerates while consolidated gross margin and SG&A-to-sales remain stable or improve. The key risk is that export growth is bought through training and promotional expense.
- Monitor quarterly distributor receivables, inventory growth, and overseas versus domestic revenue mix. A divergence in which export revenue rises but receivables/inventory rise faster would indicate channel fill and argues against adding exposure.
- Use any broad elective-aesthetics demand slowdown in Europe or Korea as a read-through risk for the name; deterioration in repeat-treatment demand would be more consequential than the initial number of contracted clinics.
More News
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Trump Says US Team Met With Iranians at UNGA
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Australia’s IDP shares drop after rejecting $494 mln Blackstone offer
- Meta’s Muse AI is exploding in popularity—and already drawing heated backlash from another tech giant
- Lennar shares pop as Berkshire builds almost a 10% stake in beleaguered homebuilder
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Investment Research Platform?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?