
SANY Renewable Energy сообщает о росте выручки от иностранных операций более чем на 300 % на WindEnergy Hamburg 2026
Source: PR Newswire
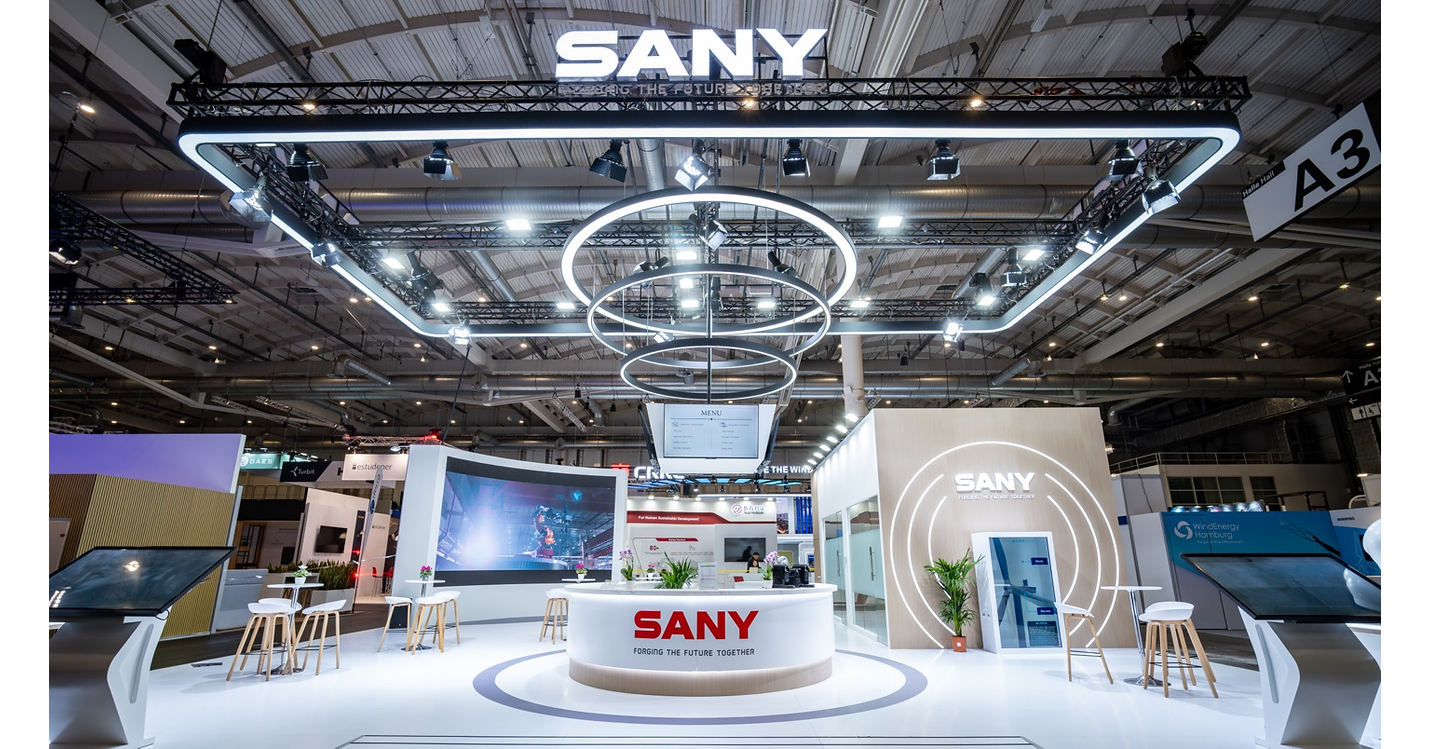
SANY Renewable Energy reported that first-half 2026 overseas revenue rose more than 300%, while signed international orders approached 5 GW. DNV awarded European certification for SANY's SI-17578EU wind turbine, supporting its expansion in Europe, and the company highlighted a 10 MW turbine platform and AI-enabled blade-clearance technology. Overseas installed capacity reached 1,462.35 MW, supported by recent projects in Kazakhstan, Central Asia and Spain.
Analysis
The relevant listed-market read-through is not S&P Global's certification/list inclusion business, but a potential pricing reset in onshore wind equipment if a Chinese OEM converts technical qualification into bankable European order flow. European turbine incumbents VWS.CO and ENR.DE already face a difficult trade-off between restoring gross margins and protecting backlog; a credible lower-cost entrant can force more aggressive bid discipline, particularly in price-sensitive Southern Europe, Central/Eastern Europe and emerging-market tenders. The largest second-order exposure is likely component suppliers with concentrated European OEM revenue—blade, drivetrain and power-electronics vendors could face localization demands and lower component pricing before turbine-market-share data visibly deteriorate.
The near-term signal remains weak: press-release order figures are not equivalent to revenue, and certification removes only one procurement hurdle. Over the next 1-3 months, watch for named European EPC/developer awards, project-financing acceptance, warranty terms, local-service commitments and evidence that orders are firm rather than framework agreements. In the 6-18 month window, sustained entry could cap Vestas/Siemens Gamesa margin recovery and pressure their multiples; conversely, EU trade defenses, permitting/local-content rules, or difficulty obtaining non-Chinese financing would sharply limit conversion and leave incumbents' pricing intact.
Contrarian view: the market may overstate immediate competitive damage because European wind buyers optimize lifetime availability, financing and service-network risk—not turbine capex alone. SANY's installed overseas base is still likely too small to alter incumbent utilization or pricing without repeat orders in core EU markets. SPGI has no material direct earnings sensitivity; any benefit is indirect and immaterial through renewable-project ratings, ESG data or index activity, so this is not a standalone SPGI catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- No directional SPGI trade: require evidence of incremental ratings/data revenue or an index-product linkage; the current development is operationally immaterial to the equity.
- Place VWS.CO and ENR.DE on a 1-3 month competitive-risk watch: reduce/hedge European wind OEM exposure if SANY announces two or more financed EU project awards or >500 MW of binding European deliveries with local O&M commitments. That would challenge assumptions behind margin-recovery estimates.
- Conditional pair trade only after verifiable EU awards: short VWS.CO versus long XLE (or a broad industrial hedge) for 6-12 months, targeting 10-15% relative downside if order pricing weakens; stop if Vestas raises FY gross-margin guidance or reports stable/improving average selling prices despite Chinese competition.
- Prefer EU wind developers and EPCs with diversified procurement—EDPR.LS and ORSTED.CO—over turbine OEMs only where tender savings are contractually captured by the developer. Validate through project IRR guidance and supplier-selection disclosures before positioning; lower turbine costs otherwise accrue to auction customers rather than equity holders.
More News
- AMC Entertainment stockholders approve equity plan amendment, reject board changes
- Treasury yields continue to rise after 10-year hit 19-year high as investors ramp-up rate hike bets
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI
- Trump Hosts China’s Xi With Trade, AI, Taiwan in Focus