
XCMG представляет новое поколение тяжелого грузовика на новой энергии для дальнемагистральных грузоперевозок
Source: PR Newswire
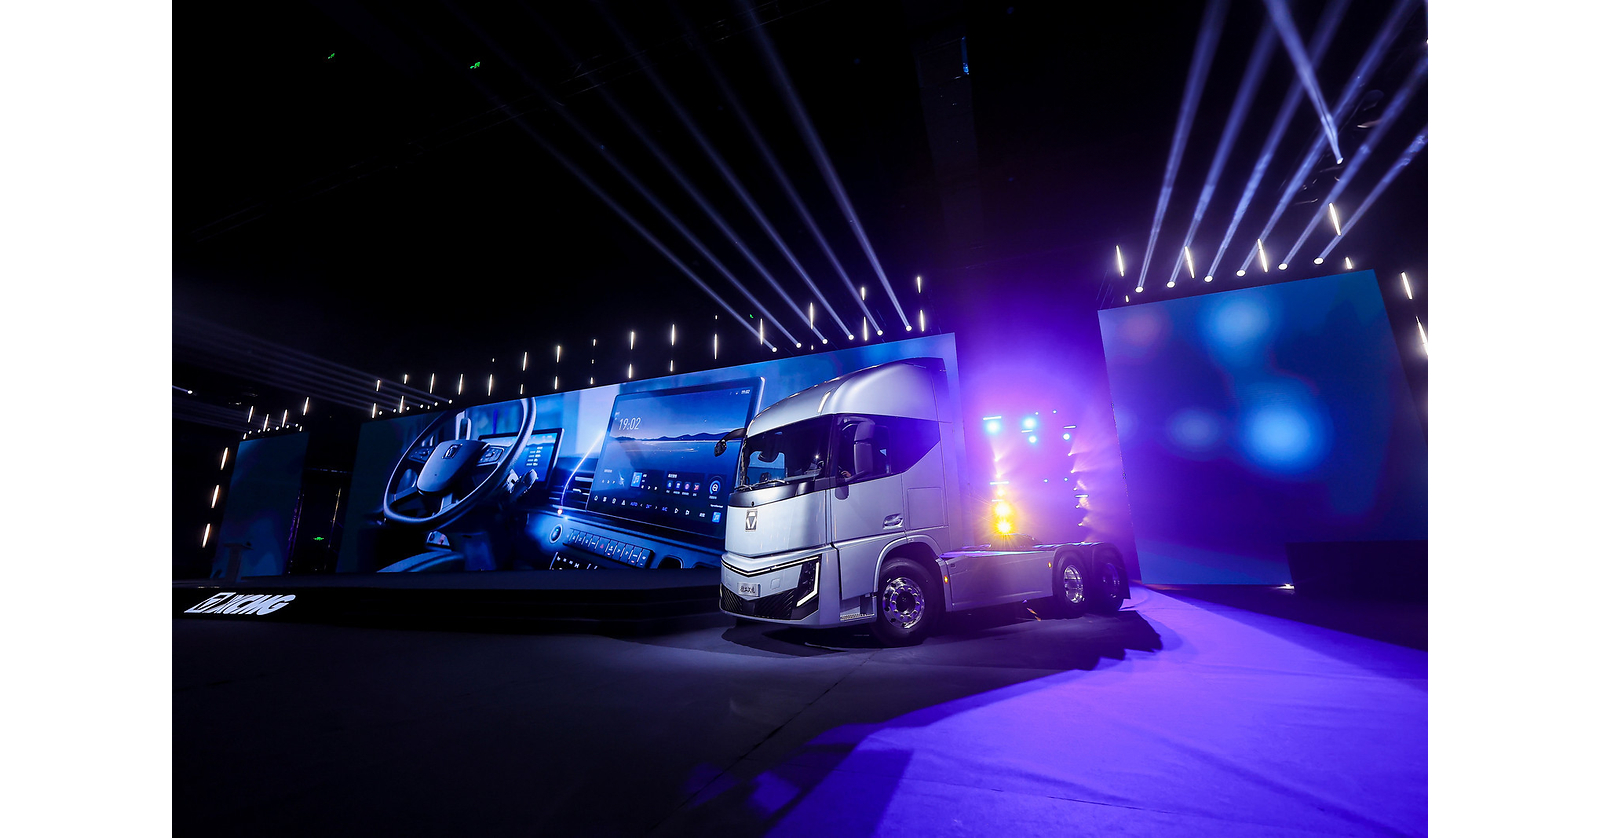
XCMG launched its Hanjing next-generation new-energy heavy truck for long-haul freight, featuring an 800V platform that can charge from 20% to 80% in under 20 minutes. The vehicle completed a 24-hour, 2,198-km endurance test at a 49-ton gross vehicle weight and combines a patented electric-drive axle, energy-management controls and battery thermal-protection systems. XCMG said it ranked No. 1 in China for new-energy heavy-truck and tractor sales from January through July 2026, while expanding sales across Southeast Asia and Africa; an Indonesian mining customer ordered an additional 100 vehicles.
Analysis
The investable signal is not the vehicle specification but the attempt to bundle truck, charging, fleet software and lifecycle service. If adopted, this shifts competition from upfront vehicle price toward route-level uptime and energy-cost guarantees, creating recurring service revenue and higher switching costs. That model favors vertically integrated Chinese OEMs and CATL (300750) over component-only suppliers, but only where depot or corridor charging utilization is high enough to absorb infrastructure capex.
Near-term equity impact is limited: this is a company press release without disclosed selling price, binding fleet orders, battery sourcing, gross-margin profile or charging-network economics. XCMG's listed vehicle exposure must also be verified before treating 000425 as a direct proxy; product leadership at an affiliate does not necessarily translate into listed-company earnings. Over the next 1-3 months, the relevant catalyst is independently reported fleet deployments on true long-haul routes, accompanied by utilization and residual-value data rather than demonstration mileage.
The second-order risk is that faster charging increases peak-power demand materially; grid connection delays and demand charges can erase the operator's fuel-cost savings even if vehicle energy consumption improves. This makes standardized megawatt-charging corridors the gating asset, not truck availability. European OEMs Daimler Truck (DTG) and Traton (8TRA) face a longer-dated competitive threat in export markets if Chinese suppliers can package financing, charging and service, but local homologation, tariffs and service coverage should prevent an immediate share-price read-through.
Consensus may overvalue the headline claim of long-haul electrification. The addressable market expands only after charging uptime, battery degradation under high-C-rate operation, and loaded-route economics are independently demonstrated for several quarters; early deployments may remain concentrated in predictable, high-utilization corridors. Conversely, confirmation of repeat orders tied to contracted total-cost-of-ownership savings would be more consequential than initial unit sales because it validates the integrated-service model.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional position on the launch alone. Create a 1-3 month alert for disclosed Hanjing order backlog, delivered units, average selling price, charging-site utilization and service attach rate; absent these data, the financial impact is not underwritable.
- Verify whether Shenzhen-listed XCMG Construction Machinery (000425) consolidates the commercial-vehicle economics before using it as a proxy. If consolidation and material revenue exposure are confirmed, consider a small tactical long only after repeat-order disclosure; exit on evidence of discount-led sales or a failure to convert pilots into paid deployments.
- Watch CATL (300750) for evidence that the platform uses its cells or megawatt-charging ecosystem. A disclosed supply or infrastructure agreement would support a 6-18 month long thesis through higher commercial-vehicle battery mix; lack of supplier disclosure is a reason not to pre-position.
- For European truck exposure, maintain DTG and 8TRA on a 6-18 month competitive-risk watch rather than shorting now. Consider a China-commercial-EV basket versus DTG/8TRA only if Chinese export registrations and local service/financing partnerships accelerate for two consecutive quarters; tariff changes or weak charging buildout would falsify the trade.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Latest Oil Market News and Analysis for Sept. 23
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard