
Tony Lama Debuts Men's Apparel: Taking the Brand Beyond the Boot
Source: PR Newswire
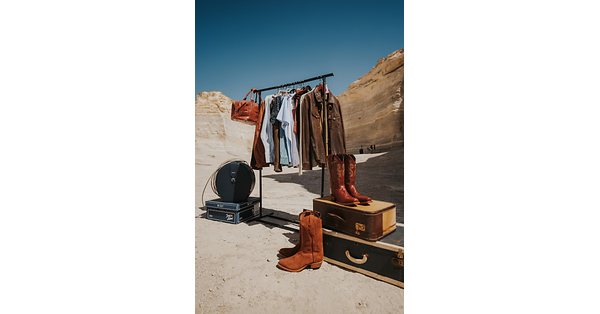
Tony Lama launched a new men's apparel collection, extending its 100-plus-year Western footwear brand into lifestyle apparel. The assortment is available on TonyLama.com and through select U.S. retailers, positioning the company to broaden its product offering beyond boots. No financial projections, sales targets, or earnings impact were disclosed.
Analysis
This is strategically sensible brand-extension activity but immaterial to Berkshire Hathaway (BRK.B), the indirect parent through Fruit of the Loom/Justin Brands. The investable read-through is not revenue scale but shelf-space competition: a vertically branded apparel offer gives Western-footwear labels a higher-ticket basket and potentially better customer-retention economics, while taking selective share from independent Western retailers' private-label assortments and national denim/workwear brands such as Kontoor (KTB). Execution risk is high because apparel carries materially greater SKU, size-curve, markdown, and inventory-obsolescence risk than core boot categories; wholesale placement alone is not evidence of sell-through.
For BOOT, the relevant second-order issue is whether vendor-led apparel extensions improve store productivity or crowd out BOOT's higher-margin exclusive/private-label mix. A successful Western lifestyle cycle would be incrementally supportive of BOOT's traffic and attachment rates over 6-18 months, but this announcement by itself provides no basis to revise estimates. The near-term catalyst is independently observable: retailer breadth, online assortment depth, price points, replenishment cadence, and evidence that the offering expands basket size rather than cannibalizes footwear spend. Consensus may overvalue heritage-brand adjacency; apparel launches frequently require promotional investment before they generate durable gross-margin benefits.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No standalone trade: the financial impact is too small and the operating claims are not independently verifiable. Do not use BRK.B as an expression; the exposure is immaterial to consolidated earnings.
- Maintain BOOT as a watch item for the next 1-3 months: monitor Western-apparel penetration, private-label gross margin, and inventory turns in the next earnings release. A sustained decline in exclusive-brand mix or a >100 bp gross-margin shortfall attributable to promotions would be a negative read-through.
- If sector data show broad Western-apparel sell-through rather than isolated distribution, consider a 6-12 month long BOOT versus short KTB pair. The thesis is that specialty retail captures basket expansion while branded denim faces incremental shelf competition; exit if BOOT comparable sales weaken or inventory growth exceeds sales growth for two reporting periods.
- Avoid extrapolating a lifestyle-brand multiple to private operators until there is evidence of repeat orders and full-price conversion. The falsifier for the skeptical view is rapid replenishment at multiple national accounts coupled with measurable apparel-driven average-unit-retail growth.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- What to know about US Federal Reserve’s first interest rate hike in 3 years
- Fed Rate Hike Looms as Retail Sales Surge
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper
- Run Cost-Controlled Financial Research in AllMind Agent Studio