
Participation in the Dos Amigos Copper-Gold Project in Chile through an Investment in Canada's Tintina Mines
Source: PR Newswire
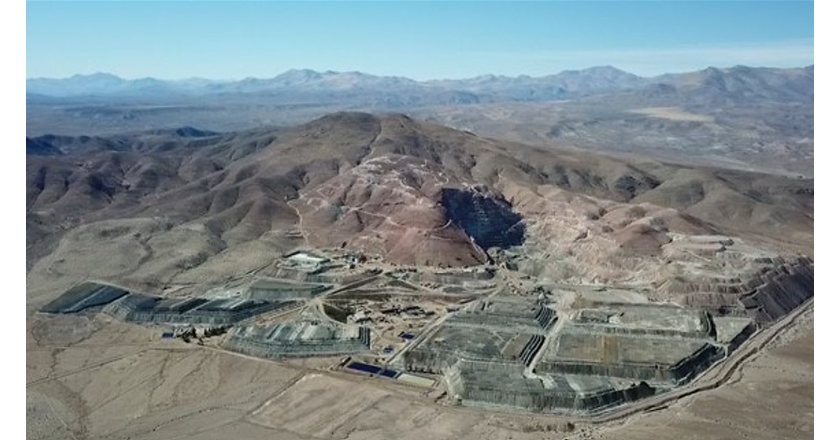
Sumitomo Corporation will invest alongside G Mining Group in Chile’s Dos Amigos copper-gold project, with a 50:50 SPV funding a C$48 million subscription into Tintina’s C$91 million private placement. The SPV will hold ~25% equity in Tintina, translating to an effective ~12.5% economic interest in the Project, which targets ~37,000 metric tons of copper and ~57,000 ounces of gold annually over an expected ~25-year mine life. Proceeds will also fund Tintina’s step-up to 100% ownership and support advancement toward a final investment decision, using the 2026 PEA resource base of ~101 Mt measured & indicated and ~256 Mt inferred.
Analysis
This is more important for GMIN.TO than for the end investor’s first-order economics. The value transfer is not the 12.5% look-through stake; it is proof that G Mining can source, structure, and de-risk greenfield copper in a market where capital is scarce and sponsors are demanding execution credibility. If that reputation compounds, the market should start valuing G Mining less like a one-off project services name and more like a repeatable project origination platform, which can support a higher multiple even before production cash flow arrives.
The second-order effect is tighter financing conditions for the rest of the TSXV copper developer universe: projects without a credible technical/financial sponsor will likely face more dilution, slower timelines, or forced asset sales. That should be a relative positive for companies with proven execution partners and a negative for serial early-stage developers competing for the same capital. SSUMY gets strategic optionality, but the equity economics are too small to move near-term earnings; the market should treat this as a portfolio-quality signal, not a P&L driver.
The main risk is that this gets re-rated as if it were a near-term production catalyst, when the real cash conversion is years away and highly sensitive to Chilean permitting, capex inflation, and copper price discipline. If copper softens materially or the next technical study shows rising sustaining/initial capex, the story becomes another long-dated optionality project rather than a value creator. The contrarian read: the market may underappreciate how rare it is for a development platform to win sponsor capital at this stage, but it may also be overestimating how much economic value a 25% stake in a PEA-stage asset can actually contribute before FID.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Long GMIN.TO on weakness over the next 1-2 weeks as a platform/multiple story, with a 6-12 month horizon into additional copper-originations; risk/reward is attractive if the market starts paying for recurring project wins rather than just fee income.
- Treat SSUMY as a watch item, not a trade: the announcement is strategically positive but financially immaterial near term; use it only to confirm management’s willingness to allocate balance-sheet capital to copper optionality.
- If you want to express the thesis with lower beta, buy GMIN.TO against a short basket of junior copper developers with no sponsor support; the relative outperformance should show up over 1-3 months as capital concentrates in better-backed projects.
- Set a downside alert on GMIN.TO if the next project update implies capex inflation or FID slippage; that would puncture the 'execution premium' thesis and justify de-risking.
- Falsifier for the long GMIN.TO thesis: a materially weaker copper tape or a PEA-to-PFS revision that cuts project economics enough to require heavy dilution.
More News
- Which Precious Metals ETF Is the Better Buy: abrdn’s Silver SIVR or VanEck’s Gold Miners GDX?
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Hormuz attacks intensify as efforts to end war on Iran stall
- What the Iran war has done to the world’s energy supply, in charts