
Spoločnosť TCL na veľtrhu IFA 2026 demonštruje svoje rastúce ambície a predstavuje nový rad smartfónov P80
Source: PR Newswire
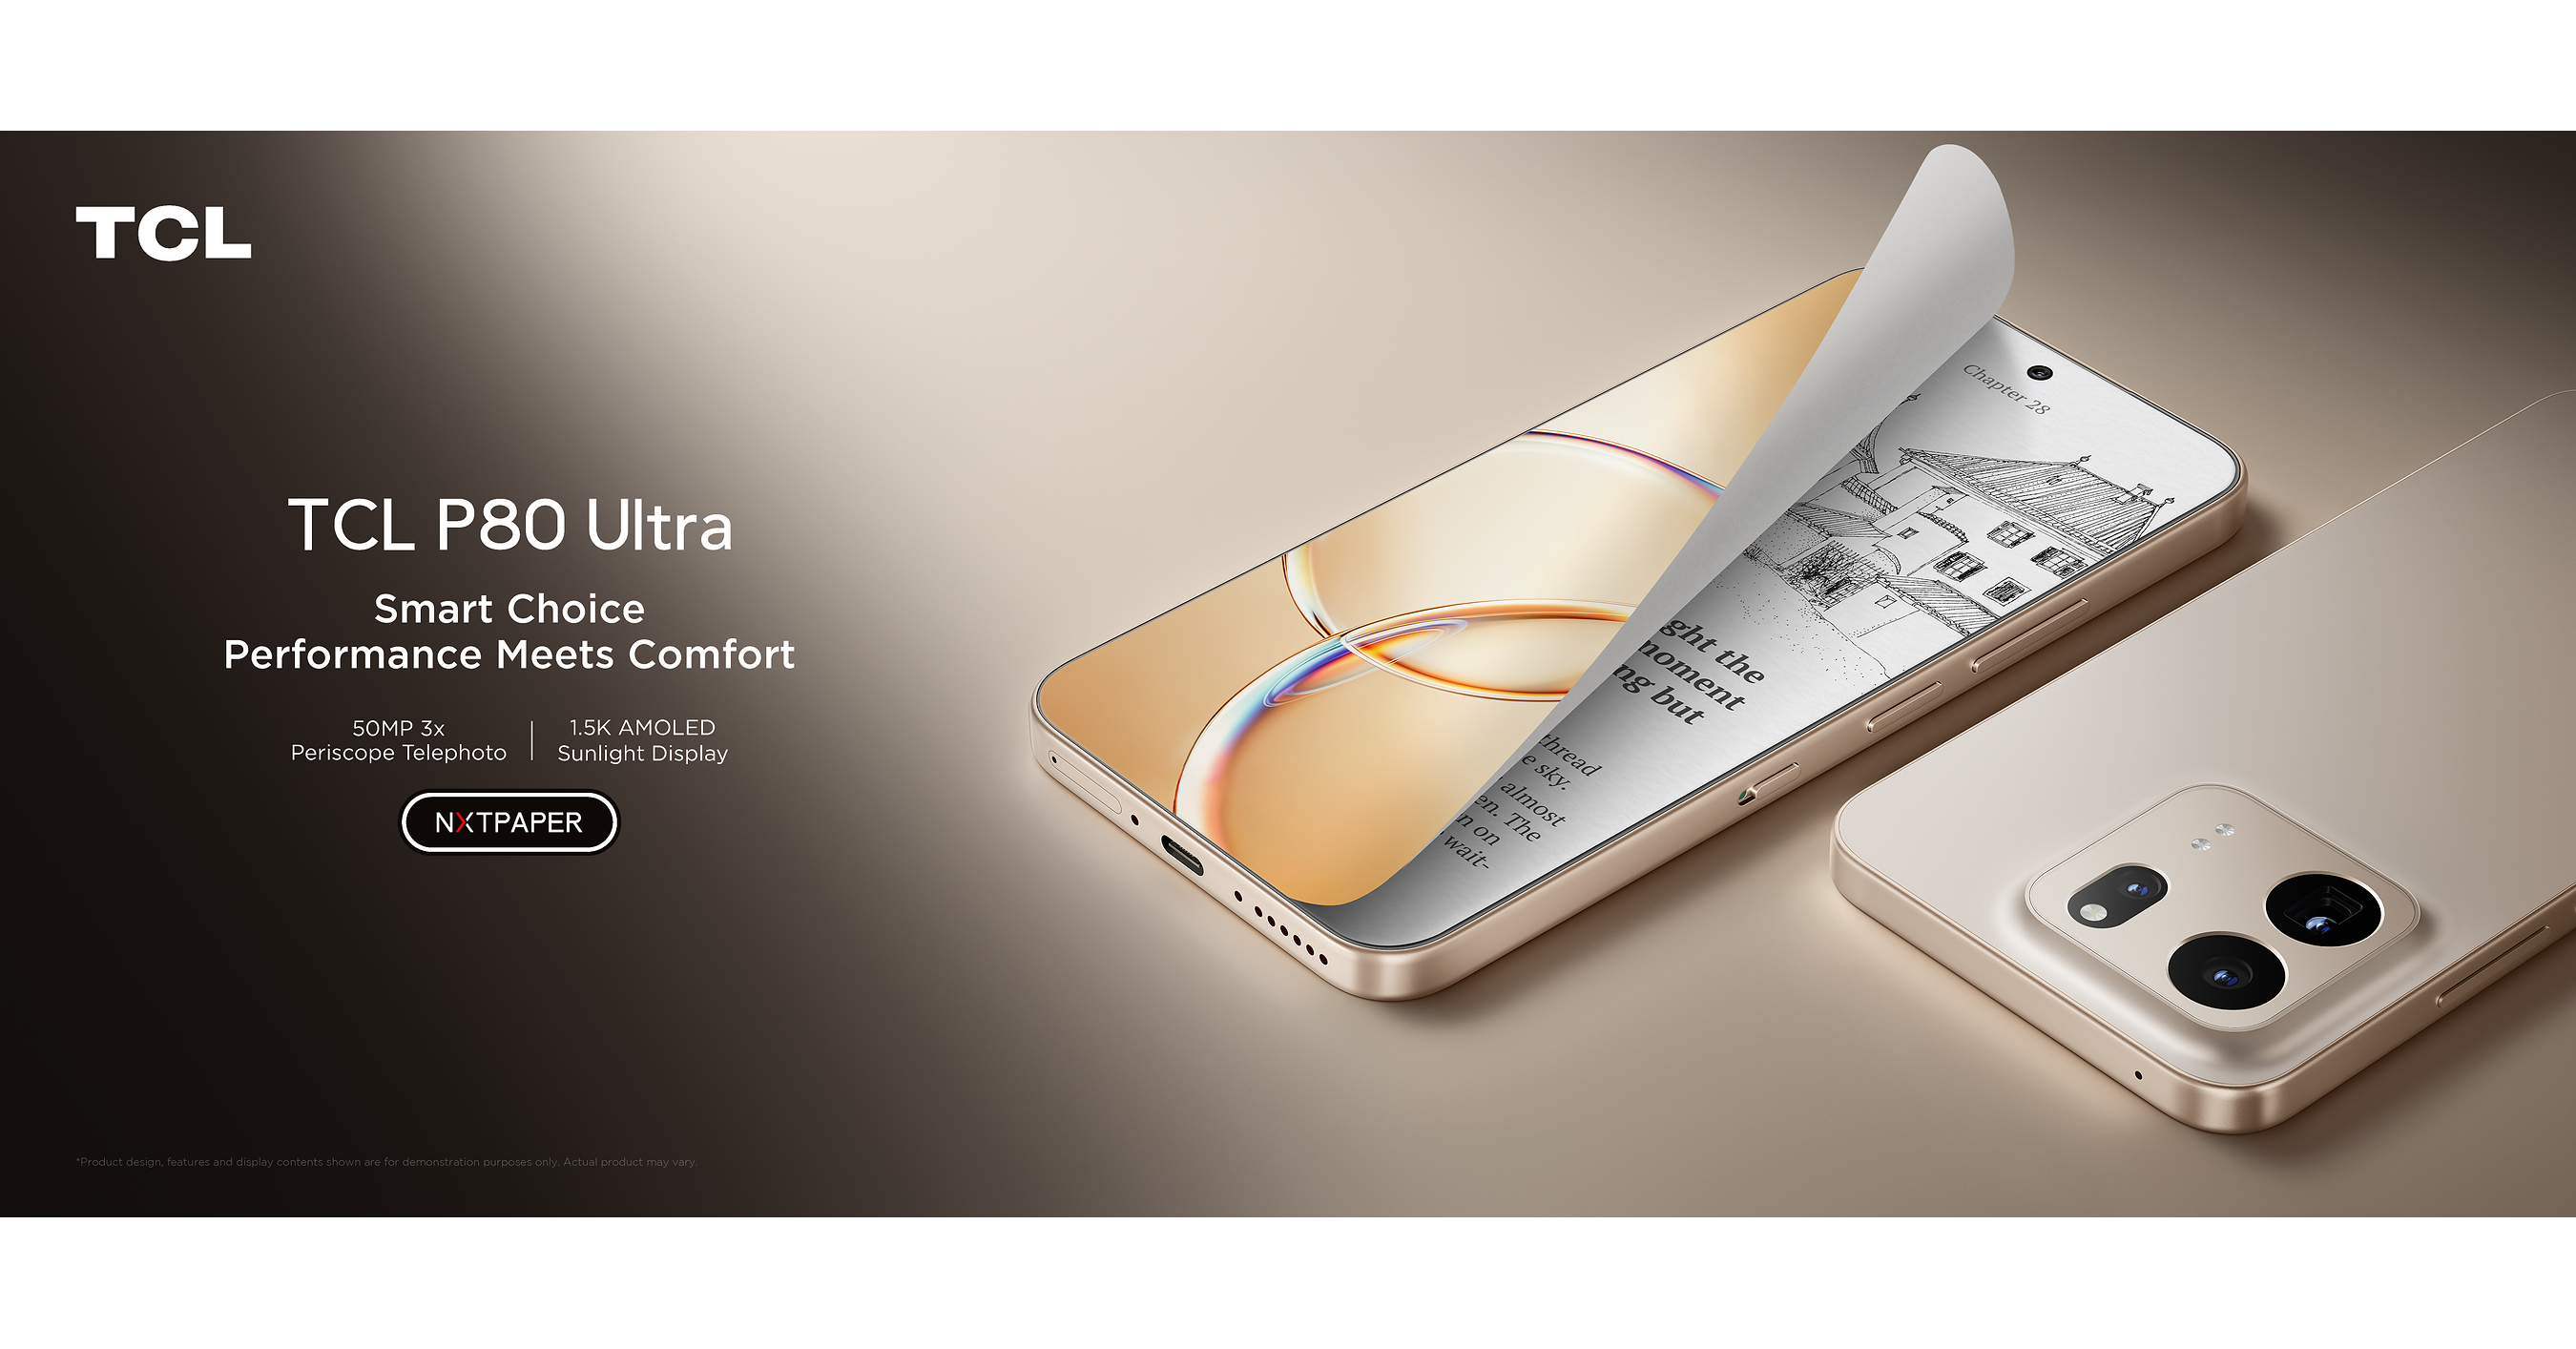
TCL na veľtrhu IFA 2026 predstavilo nový rad smartfónov TCL P80 (P80 Ultra, P80 Pro a P80), pričom P80 Ultra je vlajková loď s 50 MP periskopickým teleobjektívom s 3× priblížením a OIS+EIS. TCL do P80 Ultra a P80 Pro prináša displej NXTPAPER AMOLED s cieľom znížiť odlesky a vystavenie modrému svetlu; P80 Pro kombinuje 1,5K NXTPAPER AMOLED, batériu 5 800 mAh a úložisko až 512 GB. Ide o produktový/technologický update bez uvedenia finančných čísel, preto je dopad na trh pravdepodobne skôr obmedzený.
Analysis
This reads as a branding and mix-management attempt, not an earnings inflection. In smartphones, feature-led launches only matter if they come with carrier distribution, software cadence, and channel support; otherwise they mostly shift marketing expense forward and create inventory risk later. The likely market mechanism is margin pressure from trying to buy premium credibility before TCL has the ecosystem to defend it.
Relative winners are the component vendors that get incremental content per phone if TCL truly moves up the stack, especially camera-module, display, and premium chipset suppliers. But the launch is too small to move public financials today, so the more relevant second-order effect is competitive: TCL is trying to nibble at the same mid-tier Android shelf space occupied by Xiaomi, Motorola/Lenovo, and Samsung A-series, where differentiation is quickly copied and ASPs tend to get compressed rather than expanded.
The key risk/catalyst window is 1-3 months: carrier announcements, retail availability, review scores, and any sign of subsidy support. If those do not materialize, the move fades into a marketing cycle with little tradable impact; if they do, the real tell will be sell-through versus promotional intensity, not launch-day buzz. Over 6-18 months, the thesis only strengthens if TCL can sustain premium mix without rising return rates or discounting.
Contrarian view: consensus may underappreciate the value of TCL's display IP as a genuine point of differentiation in "comfort" and low-fatigue use cases, which could resonate in Europe and older demographics. But the market should not pay for that optionality until there is evidence of repeat purchase behavior and channel traction, because spec-sheet parity is easy to copy and hard to monetize.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate trade in handset equities or the broader consumer electronics complex; treat this as a marketing event until carrier/channel data confirms volume.
- Set a 30-60 day watchlist on EU Android channel checks: if TCL gains shelf space without heavy discounting, revisit a long QCOM / short Xiaomi-or-Android-competitor relative-value idea.
- Monitor review and teardown data for premium BOM signals; only if the P80 line shows sustained high-end component content should we consider indirect longs in GLW or QCOM over a 1-3 month horizon.
- Fade any short-term relative strength in mid-tier Android OEMs if sell-through data disappoints; the most likely outcome is promotional pressure rather than durable share gains.
- Falsifier to watch: if TCL secures carrier distribution and premium pricing holds through the next quarter, the 'no trade' stance should be reconsidered quickly.
More News
- Bending Spoons wants to revive software castoffs. Berkshire is backing the plan
- AI rapidly improving, could vastly boost U.S. GDP, Anthropic's Clark tells policymakers
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- Semiconductor market to remain solid ‘at least through next year,’ South Korea finance minister says
- Nasdaq Index: AI Selloff Deepens as Chips and CoreWeave Break
- Alphabet’s chief investment officer responds to Jefferies warning that the most likely outcome of the AI boom is massive U.S. capital destruction
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- Alternative Data Due Diligence for Institutional Investors