
U.S. Property Development Announces Grand Opening of Hamburg, New York Self-Storage Facility Managed by CubeSmart
Source: PR Newswire
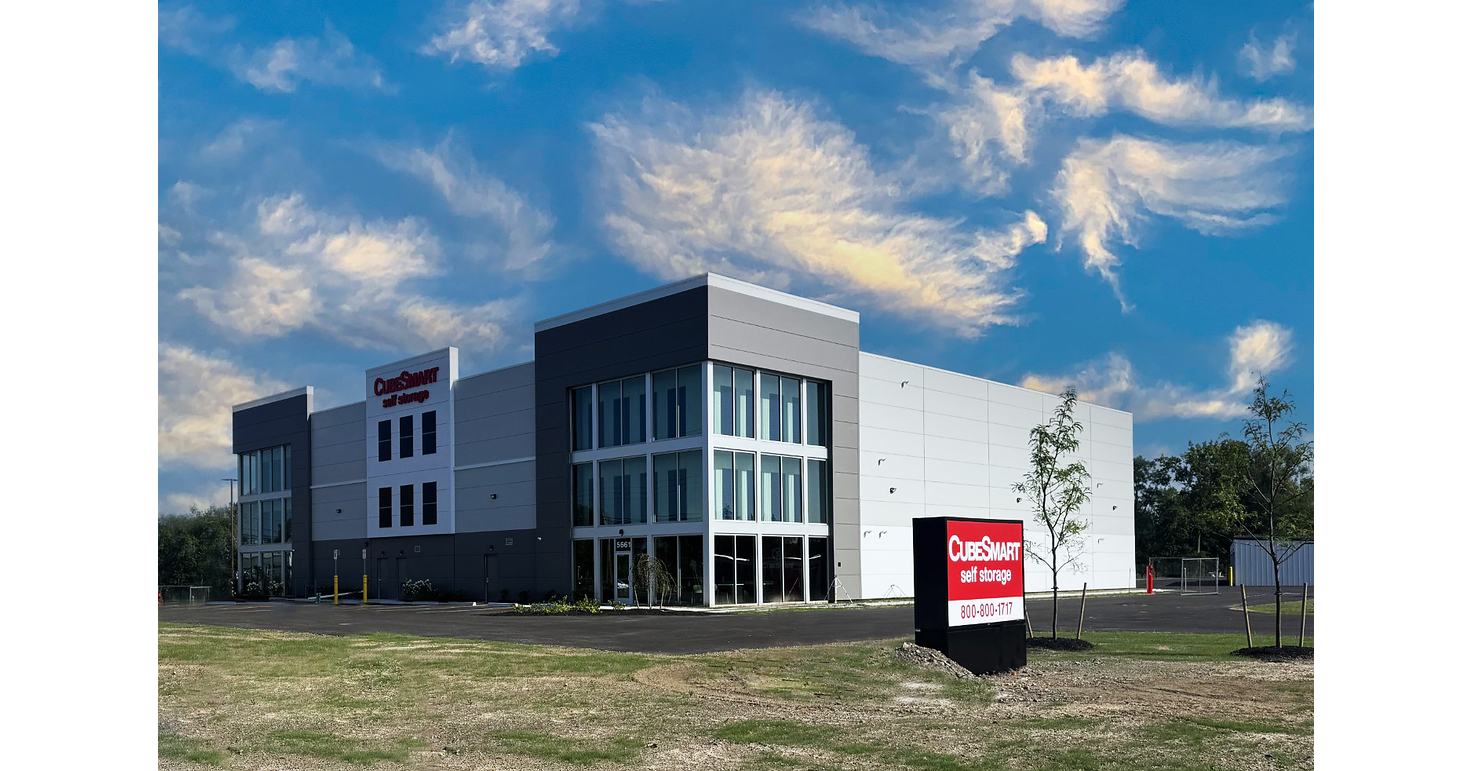
U.S. Property Development opened a 77,000-square-foot, 544-unit Class-A self-storage facility on 12 acres in Hamburg, New York. CubeSmart will manage daily operations at the site, which targets demand in the growing suburban market. The private developer said the opening supports its strategy to scale its self-storage and other real estate holdings, but the announcement provides no financial investment, revenue, or occupancy figures.
Analysis
The asset itself is immaterial to CubeSmart’s consolidated NOI, but the management contract is directionally constructive because third-party management expands fee revenue and local operating intelligence without requiring balance-sheet capital. The more relevant signal is whether private developers are again willing to deliver Class-A suburban supply: that raises the probability that new supply remains a 2027-28 headwind even as public REIT development pipelines have been restrained.
For CUBE, the immediate equity implication is negligible; investors should not extrapolate one contract into an occupancy or same-store revenue inflection. In the next 1-3 months, the useful read-through is competitive: a new, climate-controlled facility can pressure street rates and lease-up incentives at nearby incumbent stores, particularly if the market has weak household mobility or apartment turnover. Public peers EXR and PSA are exposed to the same broader risk that private capital re-enters self-storage development as construction financing normalizes.
The contrarian point is that incremental private supply is not uniformly bearish for CUBE. A fragmented-owner pipeline can enlarge CUBE’s third-party management funnel, while CUBE’s centralized pricing, digital marketing and customer-acquisition capabilities may make it the preferred operator for developers lacking scale. That benefit becomes material only if management contracts scale faster than local same-store rate dilution; quarterly net management-store additions and Buffalo-area occupancy/rent trends are the falsification metrics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this announcement; estimated financial contribution is too small to alter CUBE NAV or near-term FFO expectations.
- Maintain a 1-3 month watch on CUBE versus EXR and PSA: favor long CUBE / short EXR only if CUBE reports accelerating third-party management-store additions while same-store occupancy remains stable. Exit if CUBE guides to negative same-store revenue or Buffalo-area rate discounts broaden materially.
- For self-storage exposure over 6-18 months, require evidence that private development starts are contained before adding sector beta through PSA or EXR. A sustained rise in construction lending and announced Class-A projects would warrant a more defensive stance on the group.
- Monitor CUBE’s next earnings for net management-store growth, fee-income disclosure and same-store revenue guidance; a management-platform expansion without incremental G&A would support modest multiple expansion, while lease-up concessions at managed locations would undermine the thesis.
More News
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Americans' incomes rose and poverty fell in 2025, Census Bureau says
- Factbox-Private equity, foreign investors fuel Aussie M&A activity in 2026
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Reliance Worldwide shares hit 1-year high on Brookfield’s $2.9 bln deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper
- Run Cost-Controlled Financial Research in AllMind Agent Studio