
JONES SODA ANNOUNCES PRELIMINARY THIRD QUARTER NET REVENUE OF $13.3 MILLION, UP APPROXIMATELY 196% YEAR-OVER-YEAR
Source: PR Newswire
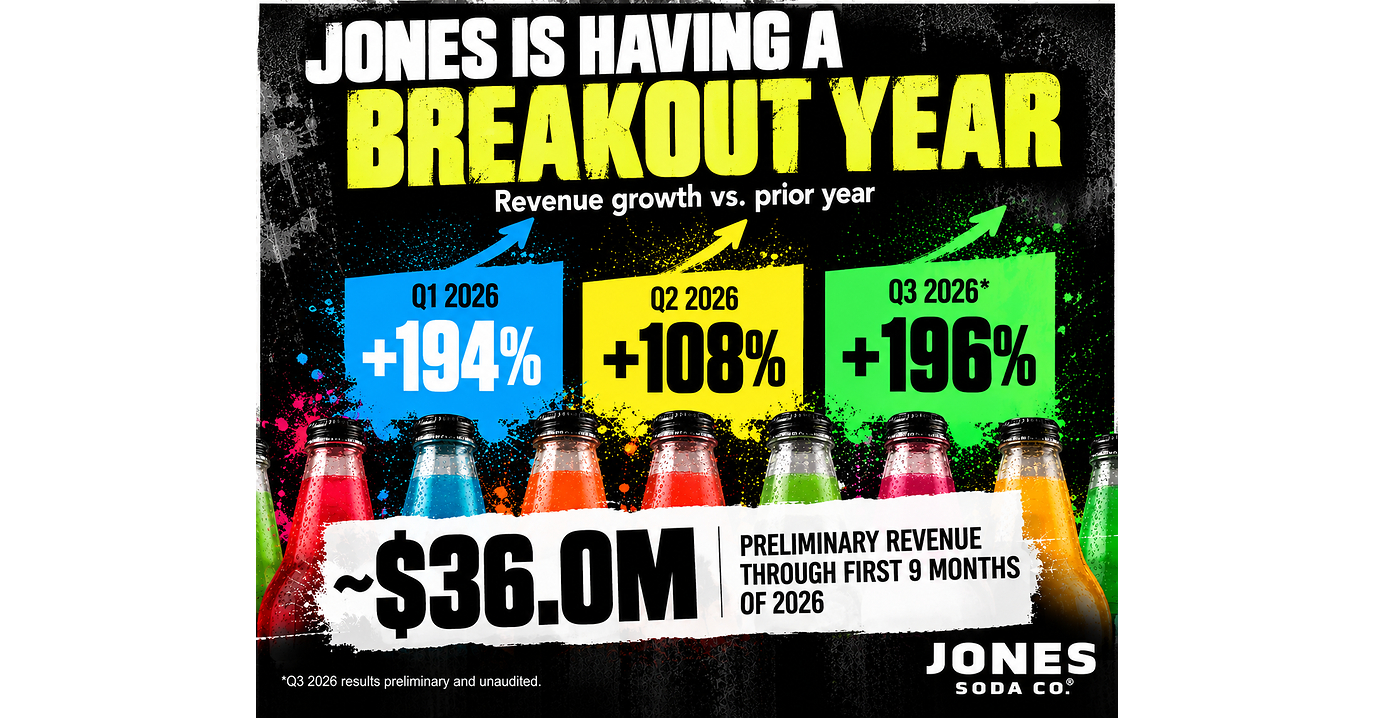
Jones Soda expects preliminary Q3 2026 net revenue of approximately $13.3 million, up about 196% year over year from $4.5 million; preliminary nine-month revenue is approximately $36.0 million, up about 164% from $13.6 million. The CEO said the company is on track to achieve its 2026 sales and EBITDA guidance, citing strong club and direct-to-consumer sales, with further retailer launches and partnerships anticipated. Results are preliminary and unaudited, and actual figures may differ.
Analysis
The key question is whether this revenue growth converts into profitable, repeatable sell-through—not whether brand attention is rising. Club and DTC growth can widen reach, but may carry different unit economics: club volume can come with pricing pressure and customer concentration, while DTC can absorb fulfillment and customer-acquisition costs. Without channel mix, gross margin, and EBITDA detail, the top-line surprise does not establish earnings leverage. Social impressions are a weak proxy for purchase conversion.
Near term, preliminary unaudited figures and the CEO’s reaffirmation of 2026 EBITDA guidance may support sentiment, but leave room for a reversal when the full close reports. Over the next 1–3 months, retailer launches and partnership announcements are catalysts only if followed by replenishment and profitable revenue; initial shipments could instead reflect channel fill. Over 6–18 months, sustained distribution and repeat demand matter more than launch count. The contrarian risk is treating growth off a small prior-period base as proof of a durable step-change. Verify comparable channel growth, gross margin, EBITDA, inventory and receivables before underwriting the trajectory.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Do not chase the preliminary revenue headline alone; wait for the completed quarter and assess gross margin and EBITDA against guidance before adding exposure.
- Treat new retail launches and partnerships as watch items, not earnings catalysts, until Jones Soda shows follow-on orders or other evidence of sell-through and repeat purchasing.
- For an existing position, keep risk bounded around the full results: weaker-than-expected margins, rising inventory or receivables, or an EBITDA guidance shortfall would falsify the profitable-growth thesis.
- Revisit a constructive view if subsequent reporting confirms growth across channels alongside stable or improving gross margin and cash conversion; the release does not provide enough information to justify a directional trade on its own.
More News
- Asia shares subdued, bonds swamped by AI debt wave
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
- Weston Family, Fairfax Financial’s Watsa Acquire Boots in $8.9 Billion Deal
- Samsung Q3 profit surges to record high, but misses lofty expectations