
Kibar Americas feiert die feierliche Eröffnung des Fairmont-Aluminiumwerks
Source: PR Newswire
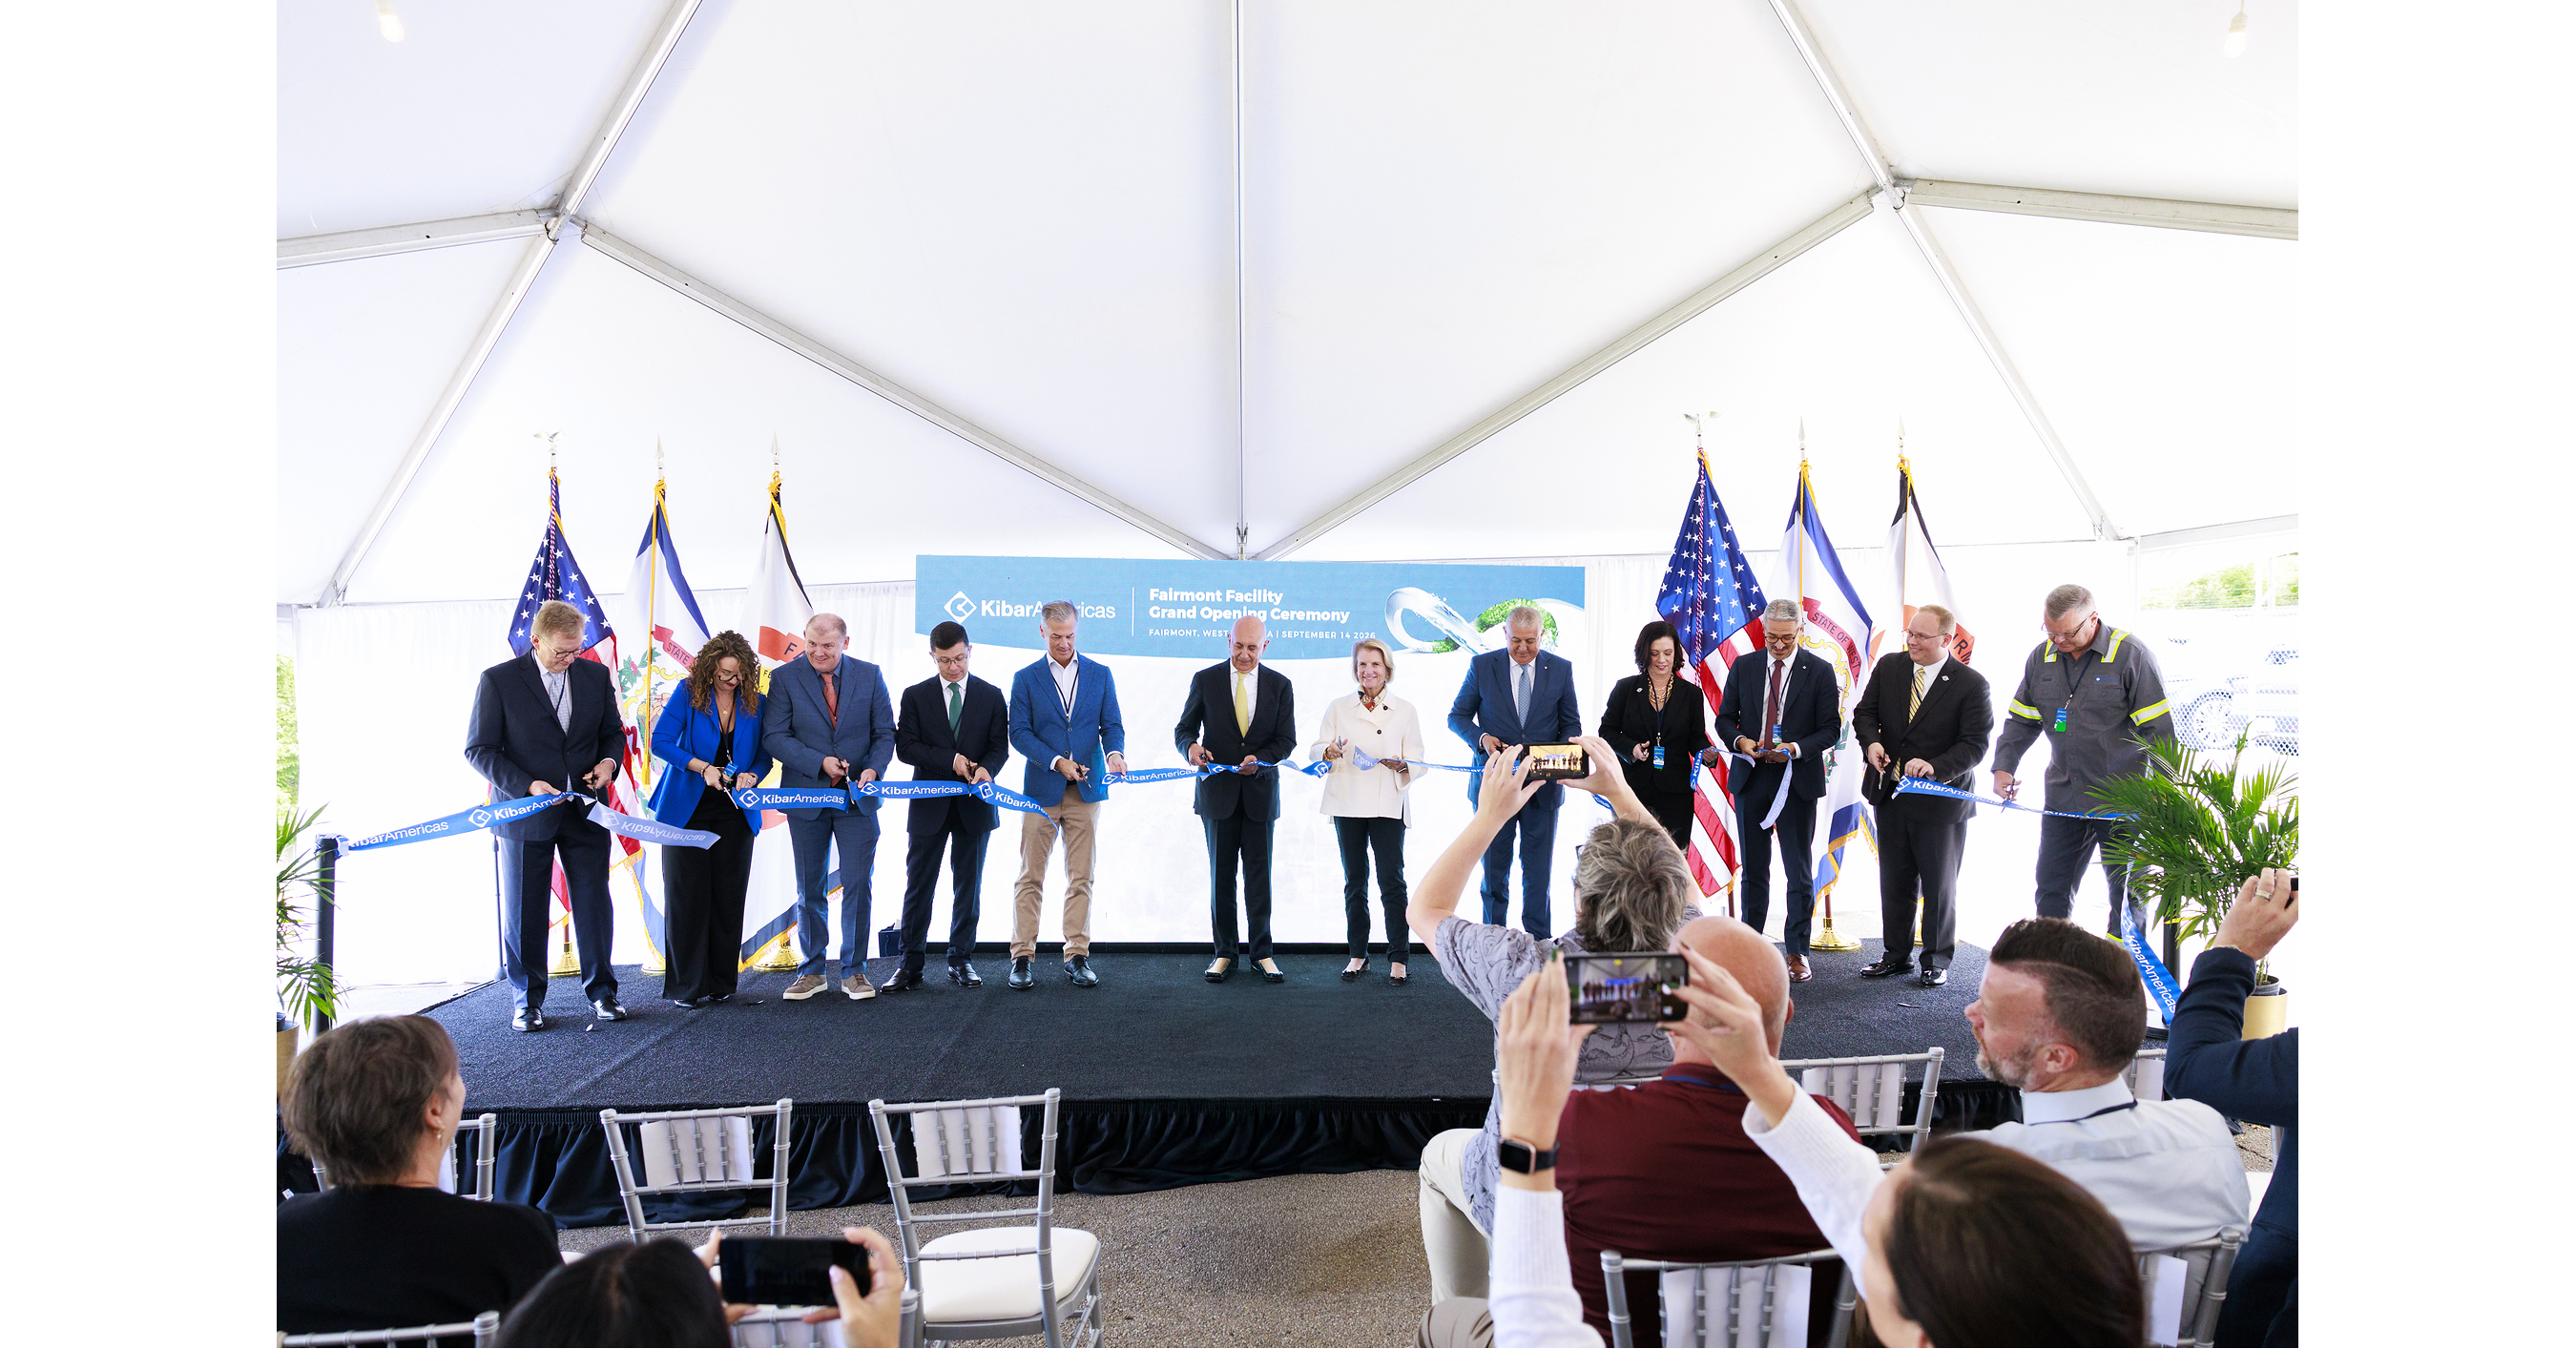
Kibar Americas inaugurated its Fairmont, West Virginia aluminum plant after acquiring the facility earlier in 2026, establishing local U.S. manufacturing capacity alongside its Chicago-based trading and distribution operations. The plant has begun producing aluminum products for HVAC, packaging, automotive and industrial markets. Management characterized the investment as a cornerstone of its North American growth strategy, with plans for further expansion and localized customer service.
Analysis
This is not yet a listed-equity catalyst: the announcement provides no capacity, commissioning curve, customer commitments, capex, or funding details. The relevant mechanism is incremental domestic rolled/foil supply into HVAC, packaging and auto, where local conversion can reduce lead times and trade-friction exposure; until volume is quantified, it is more a competitive watch item than a directional aluminum signal.
If the asset reaches meaningful scale, the most exposed incumbents are downstream North American flat-rolled suppliers rather than primary aluminum producers. Kaiser Aluminum (KALU) has greater automotive/aerospace mix insulation, while Arconic (ARNC) could face localized price competition in industrial and packaging-adjacent products; Novelis remains private, limiting direct expression. Conversely, additional domestic conversion capacity could marginally support U.S. scrap collection and secondary-aluminum demand, but it does not materially alter the LME aluminum balance.
The second-order risk is that new supply arrives into a weak packaging/HVAC demand environment, forcing utilization and conversion-margin competition rather than generating new end-market demand. A successful ramp would matter over 6-18 months only if Kibar wins contracted volumes from import substitution or gains qualification with automotive and HVAC OEM supply chains; the press release alone does not establish either. Near-term price reaction should be negligible, and no trade is warranted absent capacity and customer data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No immediate position: treat as an alert, not a catalyst. Require disclosure of annual rolling/foil capacity, product gauge mix, capex remaining, and named offtake before underwriting a competitive impact.
- Monitor ARNC and KALU quarterly commentary over the next 1-3 quarters for Midwest conversion-margin pressure, packaging/HVAC share losses, or utilization declines; a guidance cut tied to domestic competition would support a tactical short or ARNC/KALU underweight.
- Watch Midwest aluminum premium and U.S. foil/rolled-product import data over 6-12 months. Rising domestic supply with falling imports would validate import substitution; rising supply without import displacement would imply margin dilution and a more negative read for downstream producers.
- Do not use AA or aluminum ETFs as a direct expression: the facility affects fabricated-product conversion economics far more than primary-metal supply. Reassess only if multiple similar U.S. capacity additions emerge or regional scrap spreads tighten materially.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Karin Rådström is steering Daimler Truck in a new direction as the world’s biggest truckmaker faces a growing challenge from China