
Hainan Airlines Retains SKYTRAX Five-Star Rating for 15th Consecutive Year, and Ranks among the Skytrax World's Best Airlines Top 10 List
Source: PR Newswire
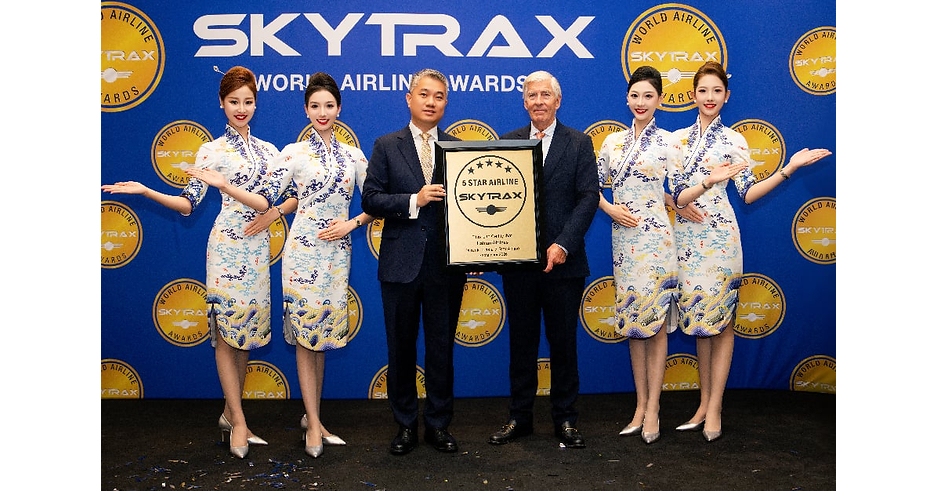
Hainan Airlines retained its Skytrax Five-Star Airline rating for a 15th consecutive year, ranked in the global top 10, and placed fourth for World's Best Cabin Crew in 2026. The carrier also won Best Airline in China, Best Airline Staff Service in China and Best Business Class Airline Comfort Amenities. It is expanding its international and regional network to more than 70 resumed, launched or planned routes, while domestic connection-service coverage increased from 19 to 36 departure points.
Analysis
The IHG linkage is commercially immaterial absent evidence of incremental room-night bookings, loyalty-member acquisition, or a broader airport-lounge rollout. Airline co-branding can improve premium traveler awareness in China, but the economics are likely marketing spend rather than a high-margin recurring revenue stream; it should not alter IHG’s earnings estimates or valuation. The more relevant read-through is directional: restoration of international connectivity can support China outbound and inbound premium travel, benefiting global hotel operators with established Greater China distribution, but this is a multi-quarter demand trend rather than a catalyst from the announcement itself.
Competitive risk sits with Marriott (MAR), Hilton (HLT), and Accor, all competing for affluent Chinese travelers and corporate accounts. If Hainan’s international capacity growth proves sustained, hotel beneficiaries will be determined by destination-market exposure and loyalty conversion rather than airline-service prestige; IHG needs disclosed booking or member-growth data to demonstrate capture. Over the next 1-3 months, this is unlikely to move IHG; over 6-18 months, a weaker Chinese consumer, renewed cross-border travel restrictions, or discounting by regional hotel peers would offset any connectivity-driven benefit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in IHG on this development; the indicated impact is too small and no measurable revenue-sharing, minimum-guarantee, or loyalty-data disclosure is available.
- Maintain a watch item on IHG China and Asia-Pacific RevPAR, net unit growth, and IHG One Rewards enrollment at the next earnings release. A clear acceleration versus MAR and HLT would support a relative-long IHG / short MAR or HLT position over 6-12 months.
- For travel-demand exposure, wait for corroboration from China international passenger-volume data and premium-hotel RevPAR. If both improve for two consecutive monthly readings, consider a modest long IHG position with a 6-12 month horizon; exit if Asia-Pacific RevPAR guidance is cut or China net system growth decelerates.
More News
- Flames, smoke seen near Riyadh airport; Houthis claim attacks on Saudi capital
- Polish prime minister warns Russia is planning drone or rocket strikes on European countries supporting Ukraine as ‘Carpathian Eight’ meet
- JPMorgan Sees No Clear Endgame for Oil Markets
- Central Command says U.S. military has aided the transit of 1 billion barrels of oil through Hormuz in past two months while Iran has ‘exported zero’
- Smoke visible near Riyadh airport after Saudi Arabia issues all-clear
- Mark Ruffalo leads Hollywood revolt against Paramount-Warner merger deal