
Shanghai Electric présente trois solutions pour la transition énergétique au salon Enlit Asia 2026
Source: PR Newswire
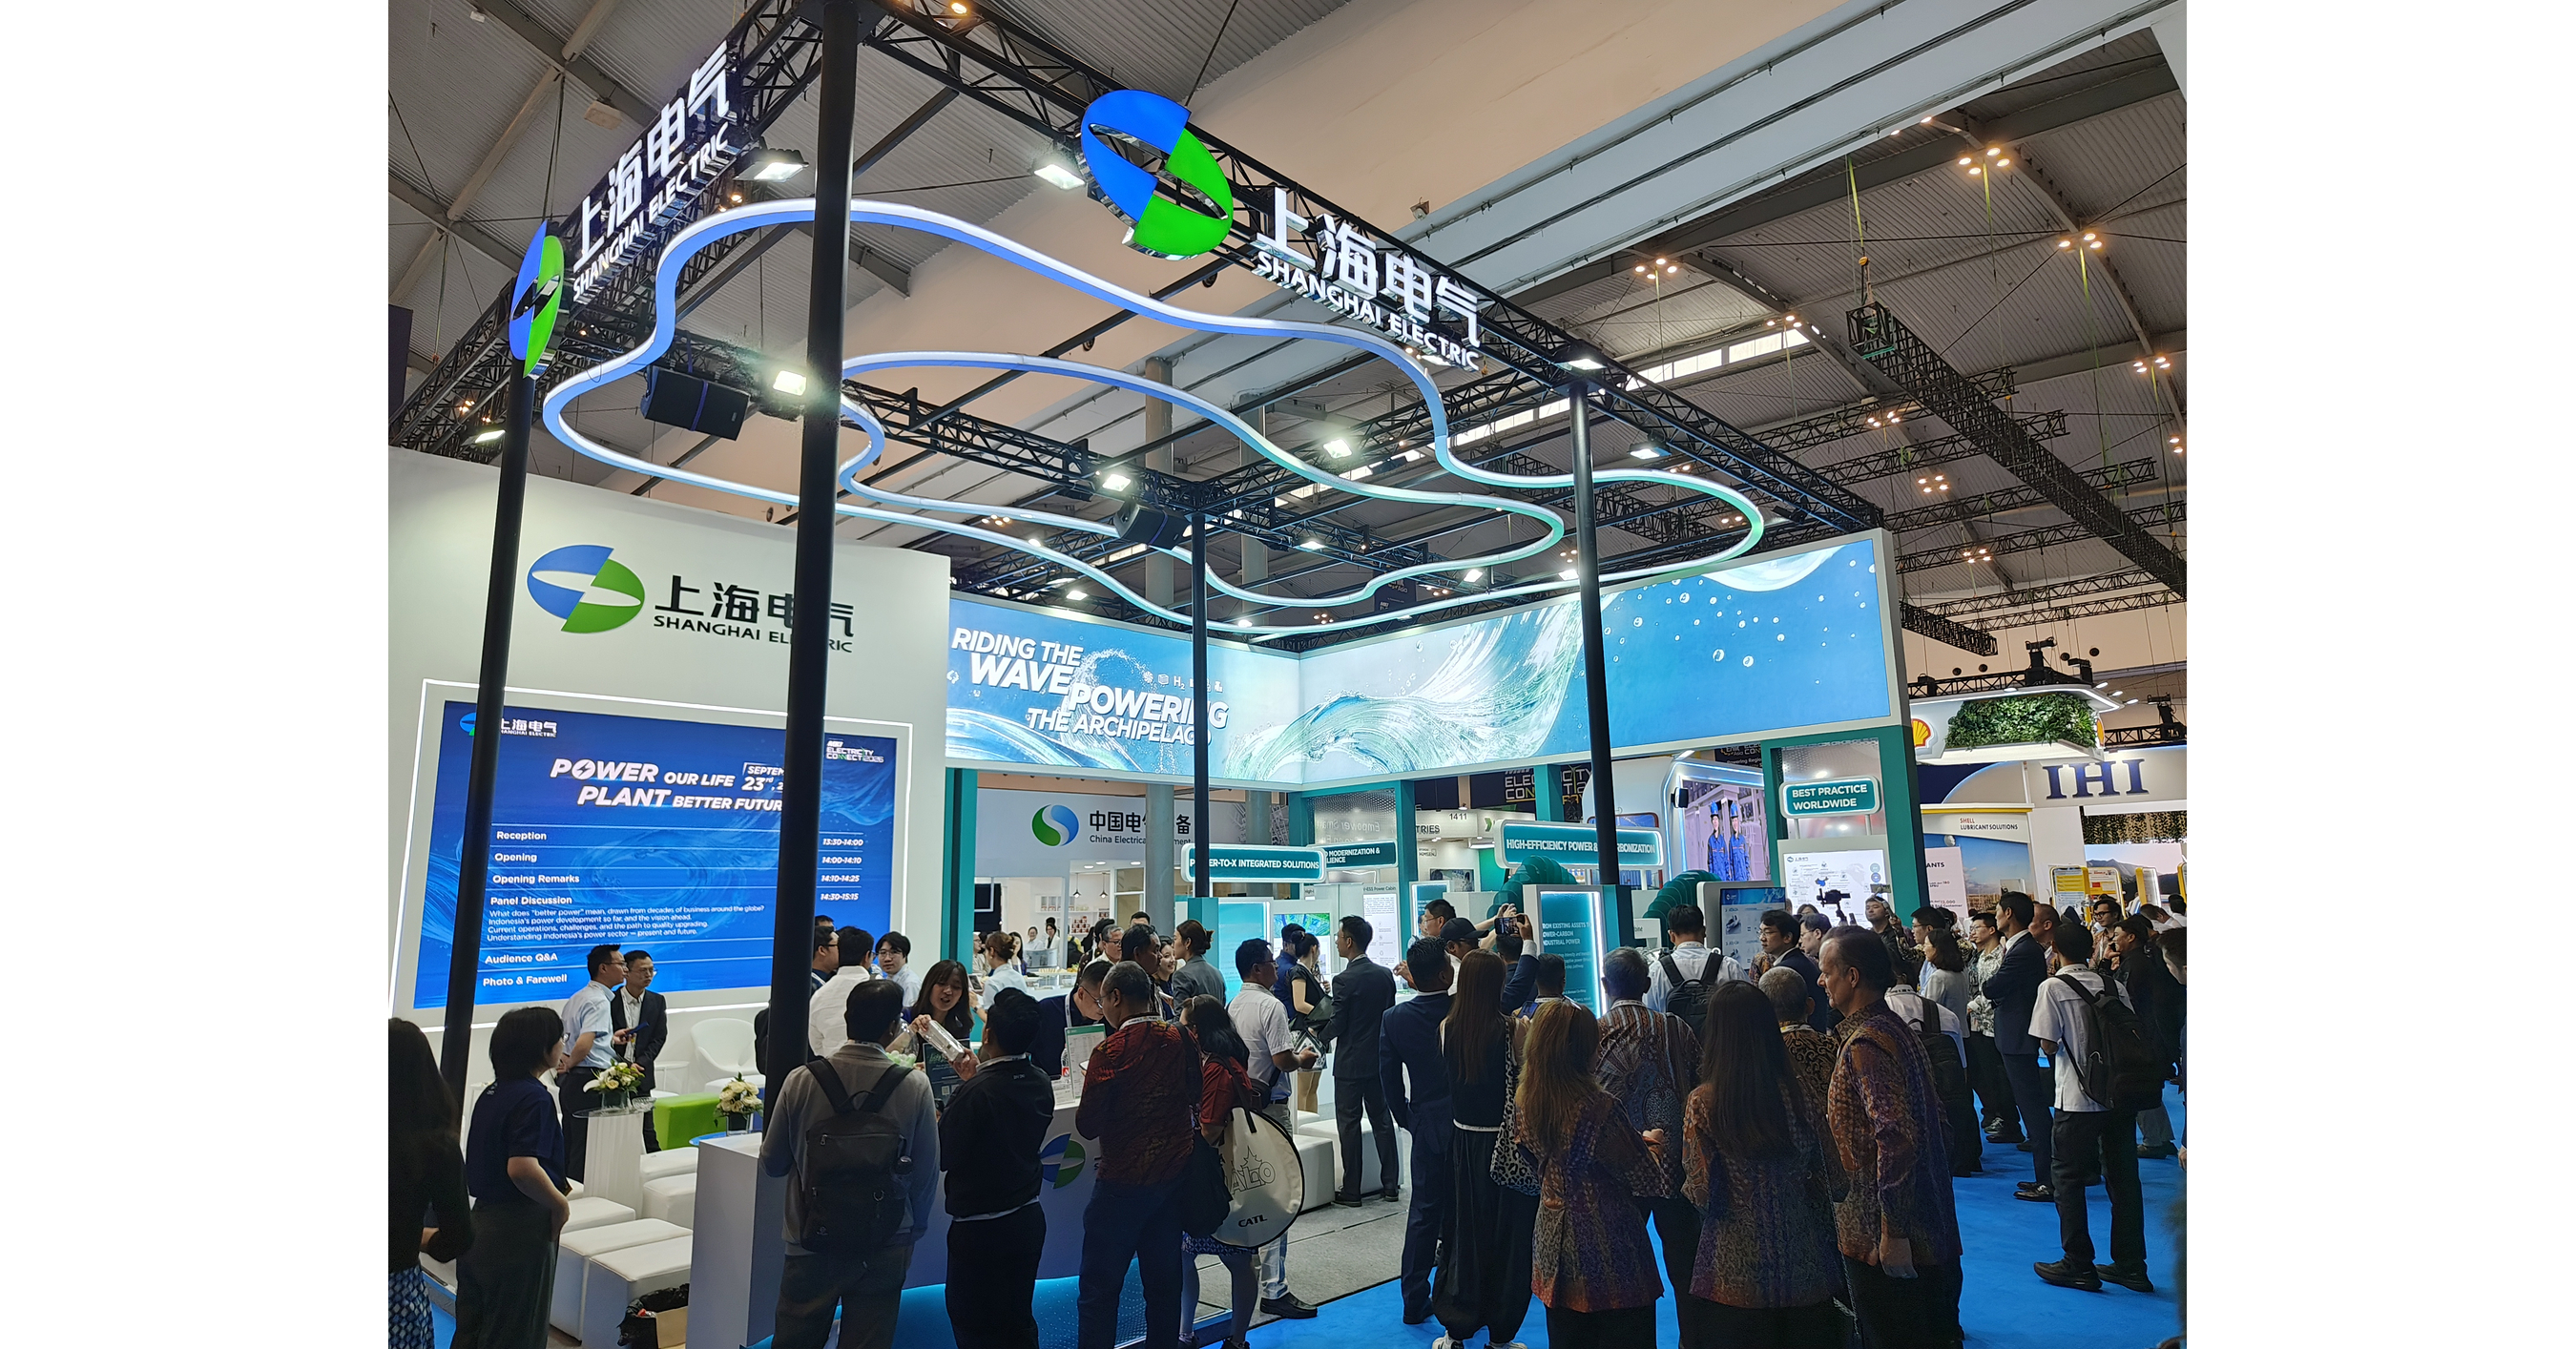
Shanghai Electric presented three ASEAN-focused energy-transition solutions at Enlit Asia 2026, spanning thermal-plant decarbonization, grid resilience and low-carbon fuels. Its gas turbines can use blends containing up to 30% hydrogen, while its Taonan Phase II project targets annual output of 200,000 tonnes of green methanol and 10,000 tonnes of sustainable aviation fuel. The announcement underscores the company's regional expansion in renewable integration, gas generation and green-fuel infrastructure, but contains no new financial guidance or contract award.
Analysis
This is promotional pipeline-building rather than an order, funding award, or utility procurement disclosure; it should not change near-term earnings expectations for Shanghai Electric. The investable signal is instead that ASEAN grid bottlenecks are widening the addressable market for inertia, reactive-power equipment, storage integration, and flexible gas generation—categories that monetize renewable penetration before green-fuel economics become viable. Demand should be strongest over 12-36 months in islanded systems, where reliability mandates can override the lower-cost but intermittent renewable buildout.
Shanghai Electric's broad offering may improve its bid positioning with state-linked utilities, but bundled EPC exposure can dilute the value of equipment wins through working-capital demands, fixed-price execution risk, and receivable concentration. Chinese peers such as Harbin Electric and Dongfang Electric face the same opportunity, while global suppliers Siemens Energy (ENR), GE Vernova (GEV), and Mitsubishi Heavy (7011 JP) retain advantages in bankability, service networks, and high-end gas-turbine references. The likely competitive outcome is price pressure in standard equipment but better margins for grid-forming controls, long-duration storage integration, and multi-year service agreements.
Green methanol and sustainable aviation fuel remain a 3-7 year optionality, not a near-term earnings driver: project economics depend on low-cost renewable power, electrolyzer utilization, feedstock availability, and enforceable maritime/aviation fuel standards. Consensus may overvalue announced capacity as contracted demand; the more immediate beneficiary is the grid capex required to connect renewable projects. Thesis falsifiers are weak utility tender activity, delayed renewable interconnection spending, declining gas-power utilization, or project-payment terms that push EPC cash conversion negative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.34
Key Decisions for Investors
- No directional trade in Shanghai Electric (02727 HK / 601727 CH) on this release alone; require disclosed ASEAN order value, advance-payment terms, and margin/accretive service content before upgrading. Treat a material backlog conversion or PLN-linked award as a 1-3 month alert catalyst.
- Establish a 6-18 month quality pair: long GE Vernova (GEV) versus short a broad China industrial proxy (FXI) or Shanghai Electric only where borrow/liquidity permits. GEV offers higher-confidence exposure to grid equipment and gas-power service revenue; reassess if ASEAN tenders favor low-cost Chinese EPC packages or GEV's order/service backlog decelerates.
- For thematic exposure, accumulate Global X Lithium & Battery Tech ETF (LIT) or a diversified grid/storage basket only on evidence of funded Indonesian/Malaysian storage procurements; avoid underwriting green-methanol capacity announcements before offtake contracts and delivered-power costs are disclosed.
- Monitor Siemens Energy (ENR) and Mitsubishi Heavy (7011 JP) for a relative-long entry after any ASEAN grid or combined-cycle tender award. Risk/reward improves if awards specify long-term maintenance agreements; exit the relative thesis on aggressive Chinese underbidding or evidence that utility financing constraints defer projects beyond 2027.
More News
- China's AI chip blitz arms Xi with a message for Trump: 'You can't choke us off'
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- Japan's 10-year bond yield hits 30-year high following sell-off in Treasurys
- America’s Asian allies want a Trump-Xi truce — but not at their expense
- US Debt Selloff Spans Most Maturities: Evening Briefing Americas
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro