
The Dyrt Named to Inc. 5000 List of Fastest-Growing Companies for Fifth Consecutive Year
Source: PR Newswire
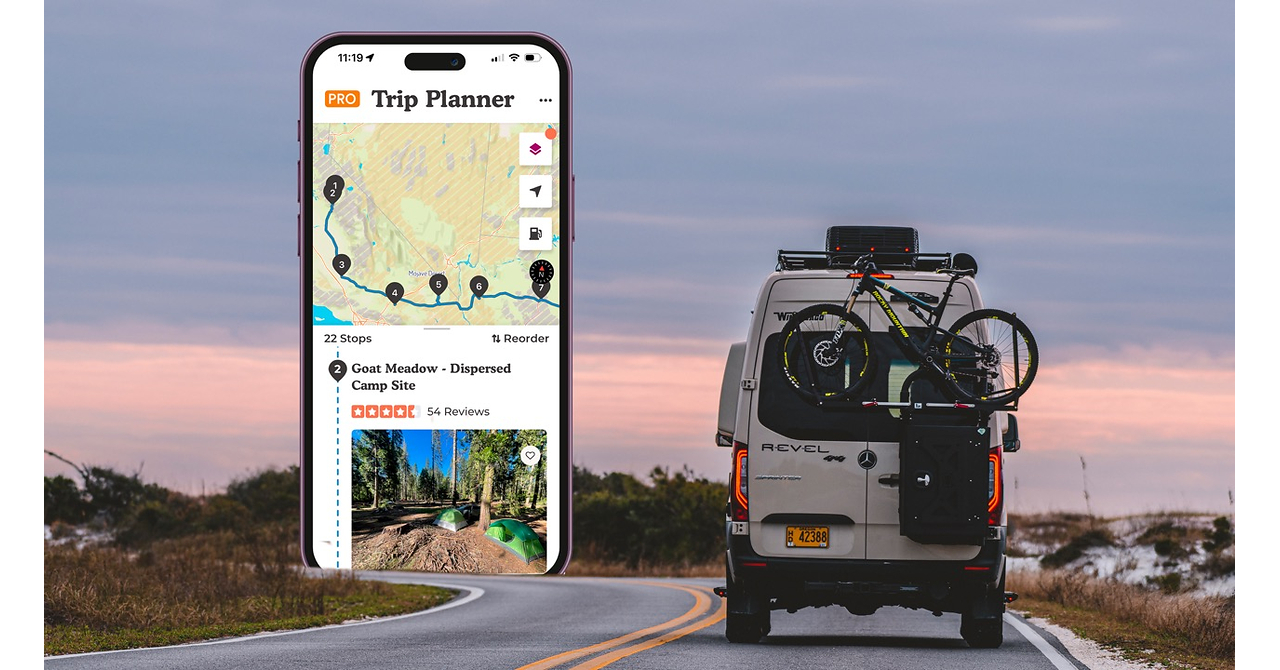
The Dyrt ranked on the Inc. 5000 for the fifth consecutive year, entering the Honor Roll and reporting its highest ranking to date with 155% three-year growth from 2023-25. Its updated PRO Trip Planner has supported more than 300 million miles of planned trips, while 52.2% of campers used an RV or trailer at least once last year. The announcement indicates sustained user engagement and favorable RV-camping demand, but is unlikely to have broad public-market impact.
Analysis
This is a weak, indirect read-through for TM rather than a company-specific catalyst. The relevant signal is that RV-oriented trip planning remains sticky enough to support continued ecosystem investment, which marginally favors pickup/SUV demand and dealer accessory attachment over discretionary passenger-car demand. However, camping-platform engagement is not a reliable proxy for vehicle purchase intent: the installed RV fleet can generate trip growth without incremental vehicle sales, and the cited data are promotional rather than independently auditable.
The more investable second-order exposure is among RV and towable supply-chain names: THO, WGO, PATK and LCII benefit only if campground usage converts into new-unit orders or higher replacement/upgrade rates. Near term, increased RV utilization is more likely to support parts, service and aftermarket spending than OEM RV production, favoring PATK/LCII relative to THO/WGO if retail financing remains restrictive. CWH could see traffic and service demand support, but its earnings remain more sensitive to unit margins, used-RV values and promotional intensity than to campsite discovery activity.
Consensus risk is extrapolating leisure usage into a cyclical RV recovery too early. Over the next 1-3 months, monitor RVIA wholesale shipments, CWH same-store sales, used-RV depreciation and 48-84 month consumer loan rates; a sustained improvement across those indicators would validate a demand upcycle. Over 6-18 months, lower financing costs could turn high utilization into replacement demand, but fuel-price spikes, weaker consumer confidence, or campground capacity constraints would break that conversion mechanism.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No directional TM trade on this item; its implied revenue sensitivity is immaterial. Maintain an alert for North American pickup/SUV incentive trends and dealer inventory days, which would provide a cleaner read on whether outdoor-travel demand is translating into vehicle demand.
- Watch-list pair for a confirmed RV recovery: long PATK / short THO over 3-6 months if RVIA shipments inflect positive year-over-year and retail loan rates decline at least 100bp. PATK should capture aftermarket/content resilience with less exposure to OEM unit-production volatility; exit if wholesale shipments remain negative for two consecutive monthly releases.
- Avoid adding to THO or WGO solely on recreational-travel engagement. Upgrade only after dealers report sustained order-book improvement and used-RV pricing stabilizes; absent those confirmations, continued discounting can compress gross margins despite higher campground activity.
- For CWH, monitor quarterly same-store sales and gross-margin guidance rather than trip-planning metrics. A positive same-store-sales inflection with stable used-RV values would be the actionable catalyst; renewed used-unit depreciation or margin guidance cuts would invalidate a bullish setup.
More News
- Rivian Shines as a Bright Spot in a Down U.S. EV Market, and Surprisingly, It's Not All R2 Driven
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data
- Best AI Stock Research Tools for Professional Investors