
Hyundai Motor Unveils The all-new TUCSON, Its Boldest SUV
Source: PR Newswire
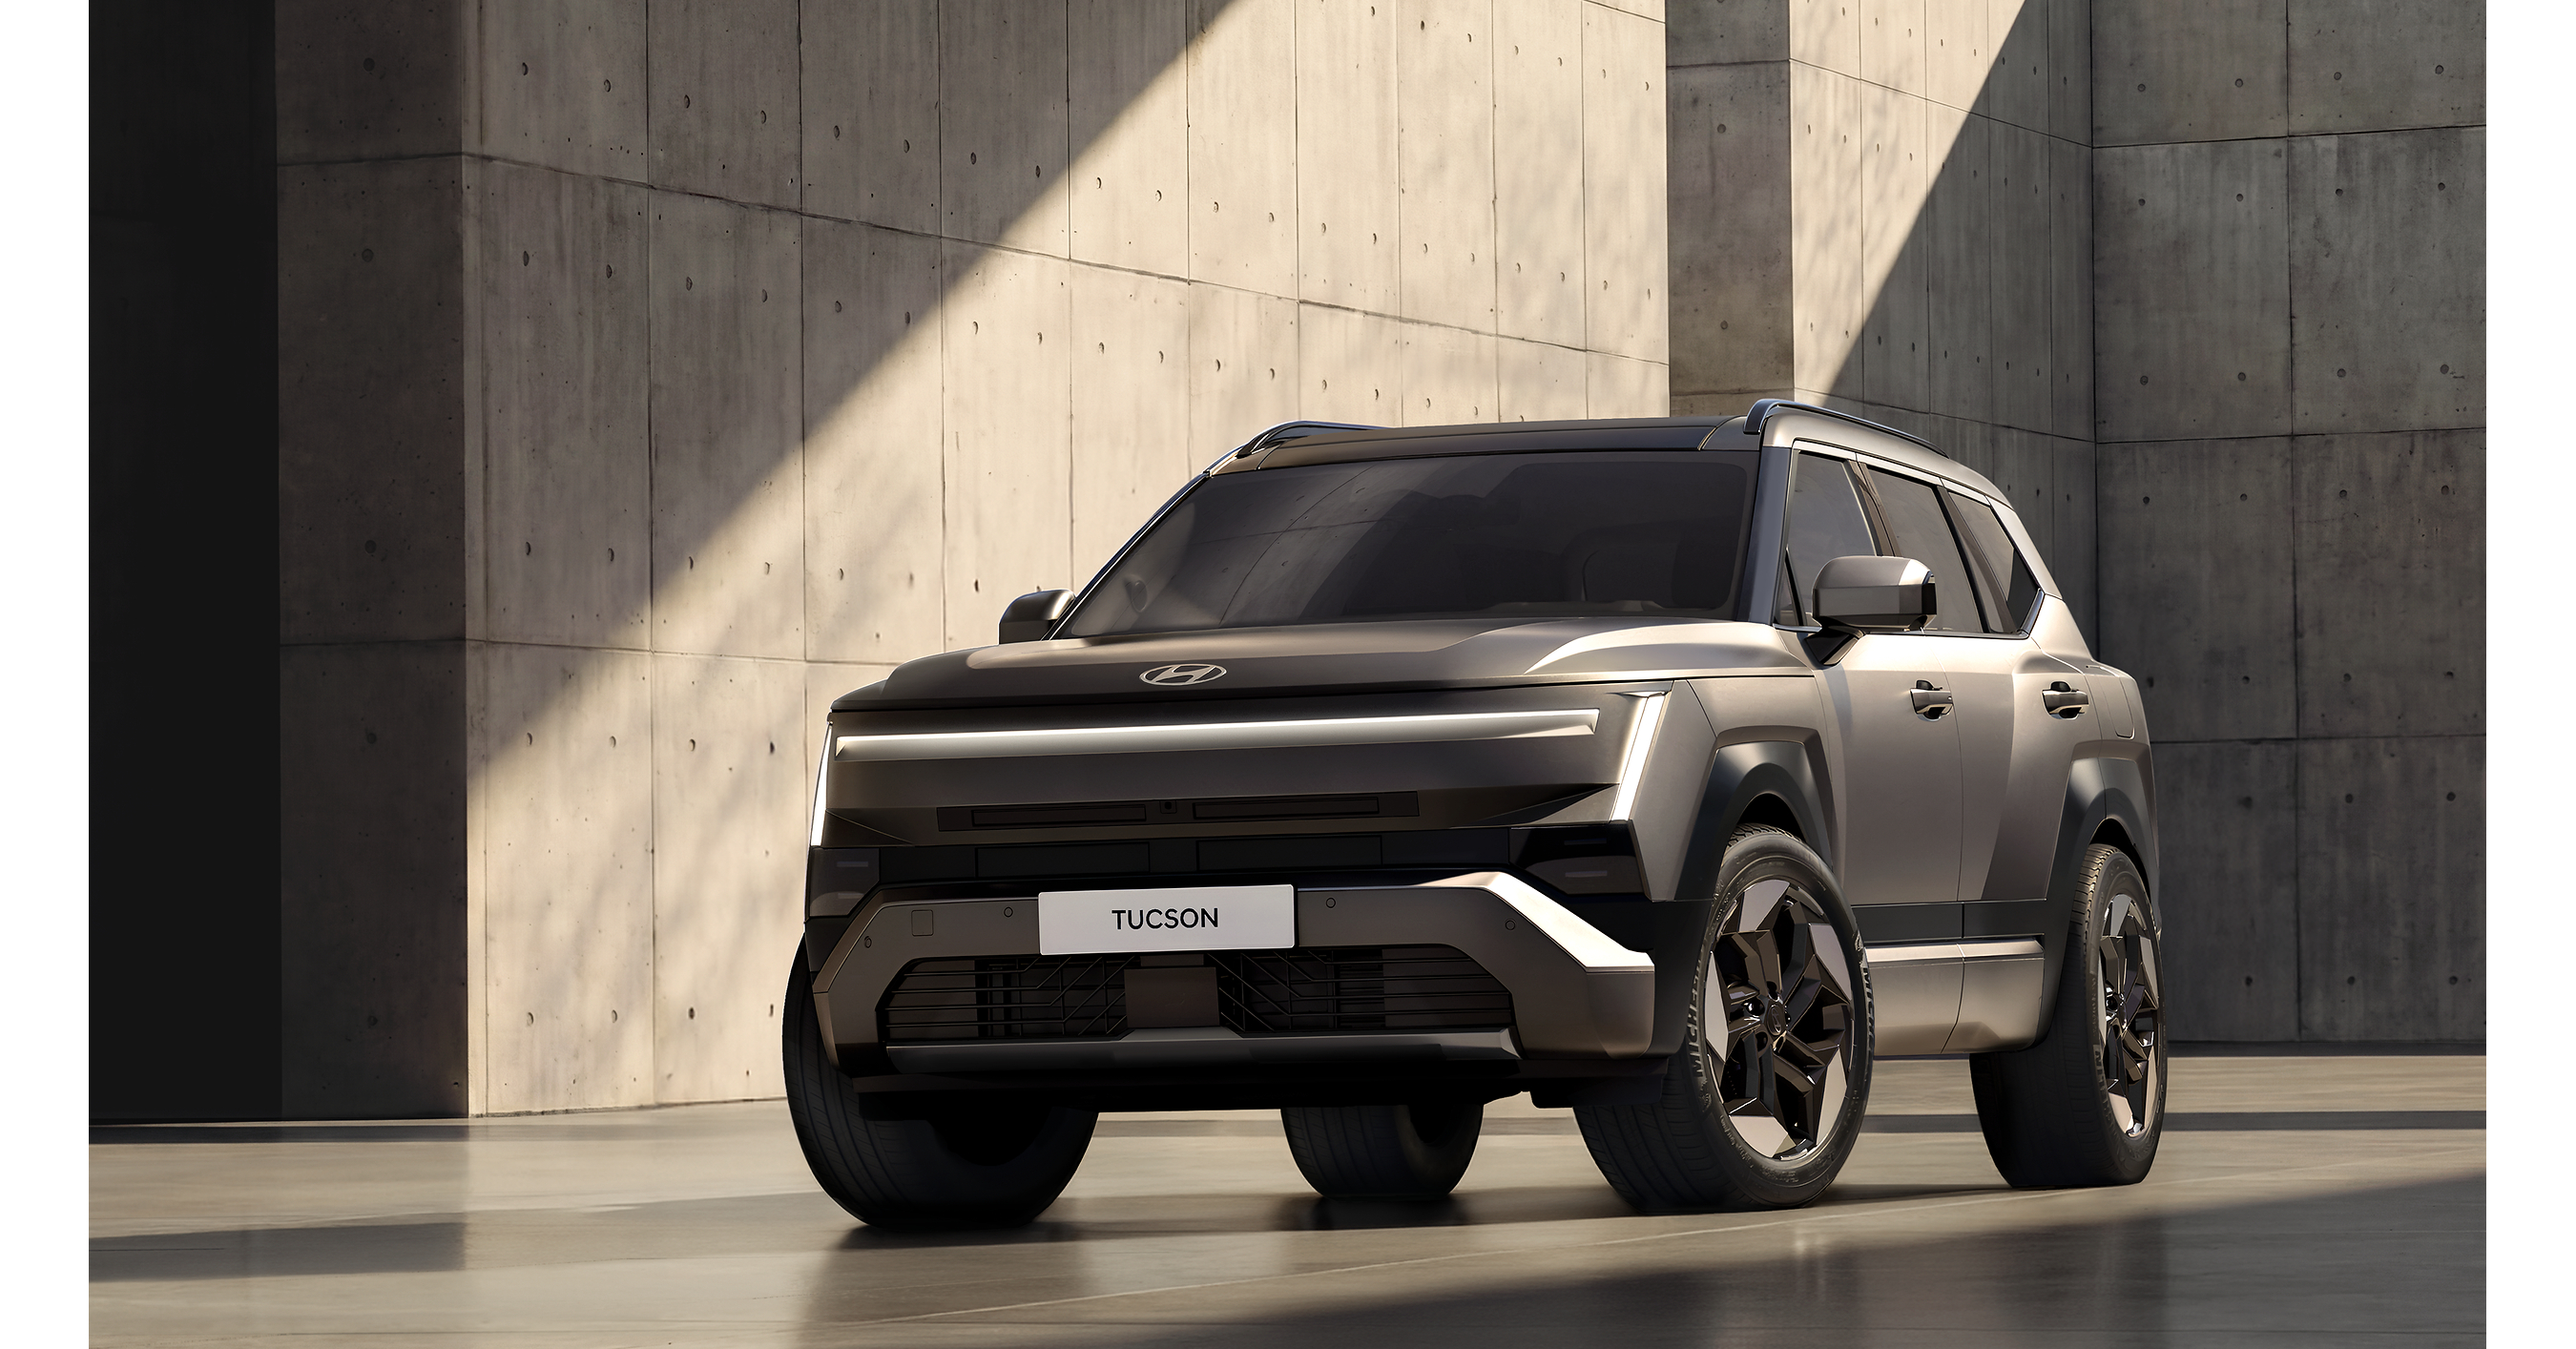
Hyundai unveiled the all-new Tucson, its best-selling global SUV with cumulative sales above 11.1 million units, ahead of launches in Korea later in 2026 and other global markets in 2027. The next-generation hybrid targets up to 42 mpg and 0-60 mph in 8.5 seconds, while the plug-in hybrid offers an estimated 81 km of electric range and 292 ps. The model adds Pleos Connect infotainment with Gleo AI, over-the-air updates and an app ecosystem, while the North American HEV towing rating rises 1,000 pounds to 3,000 pounds.
Analysis
This is strategically more meaningful as a hybrid-mix and software-stack signal than as a near-term unit-volume catalyst. Hyundai’s ability to offer credible HEV, PHEV and ICE variants in a high-volume crossover segment lowers its exposure to volatile EV incentives and gives it a potential share-gain wedge against BEV-heavy offerings from Ford (F), GM (GM) and Volkswagen (VOW3.DE) if consumers remain value-sensitive. The economics hinge on transaction-price realization: feature-content additions can support mix, but larger dimensions, advanced lighting, battery content and computing hardware raise BOM risk if incentives or pricing fail to offset them.
The 2027 North American timing means any earnings benefit is at least 1-3 quarters away and is unlikely to change current estimates absent pricing, production allocation, or order-intake disclosures. Near-term, watch U.S. compact-SUV hybrid inventory days, incentive spending and Hyundai/Kia hybrid production constraints; a constrained supply environment would make this a margin-positive mix upgrade, while broad industry discounting would turn the launch into a content-cost headwind. The AI/OTA narrative should receive little standalone valuation credit until Hyundai discloses attach rates, subscription pricing, data economics, and recurring revenue retention.
Second-order beneficiary potential lies with Korean component suppliers exposed to hybrid power electronics, batteries and ADAS/display content, but the supplied ticker WPTG.B does not appear to be a directly identifiable Hyundai manufacturer, supplier, or dealer exposure. The appropriate market conclusion is therefore no actionable single-name trade from this release alone. Consensus may overread the premium technology claims: compact-SUV buyers remain payment-driven, and the relevant test is residual values and incentive intensity versus Toyota RAV4 Hybrid and Honda CR-V Hybrid, not feature parity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No position in WPTG.B on this release; establish an alert only after confirming its legal entity and direct Hyundai revenue exposure. Do not infer a supplier benefit from thematic classification alone.
- Monitor Hyundai Motor (005380.KS) versus Toyota (7203.T) over the next 1-3 months for U.S. hybrid inventory and incentive data. Consider a long Hyundai/short Toyota relative-value trade only if Hyundai demonstrates incremental hybrid supply without incentive escalation; falsify if Hyundai U.S. incentives rise materially or hybrid mix fails to improve.
- Ahead of 2027 launch, track compact hybrid crossover transaction prices and residual values against RAV4 Hybrid and CR-V Hybrid. A sustained discounting cycle would argue for avoiding Hyundai-margin optimism despite stronger product content.
- Treat Pleos Connect/Gleo AI as a diligence watch item, not a software-revenue trade: require disclosed take rate, ARPU, gross margin and OTA/service attach metrics before assigning recurring-revenue multiple expansion.
More News
- Trump launches midterms campaign blitz amid record low approval ratings
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- Fed’s Cook sees AI buildup as top inflation risk for 2027
- The September jobs report will be released Friday. Here's what to expect
- U.S. stock futures drift higher with nonfarm payrolls in focus
- $8.2B acquisition validates AI-picked chip stock: +20% since June