
Griffis Residential Announces Commencement Closing of Griffis Premium Apartment Fund VII
Source: PR Newswire
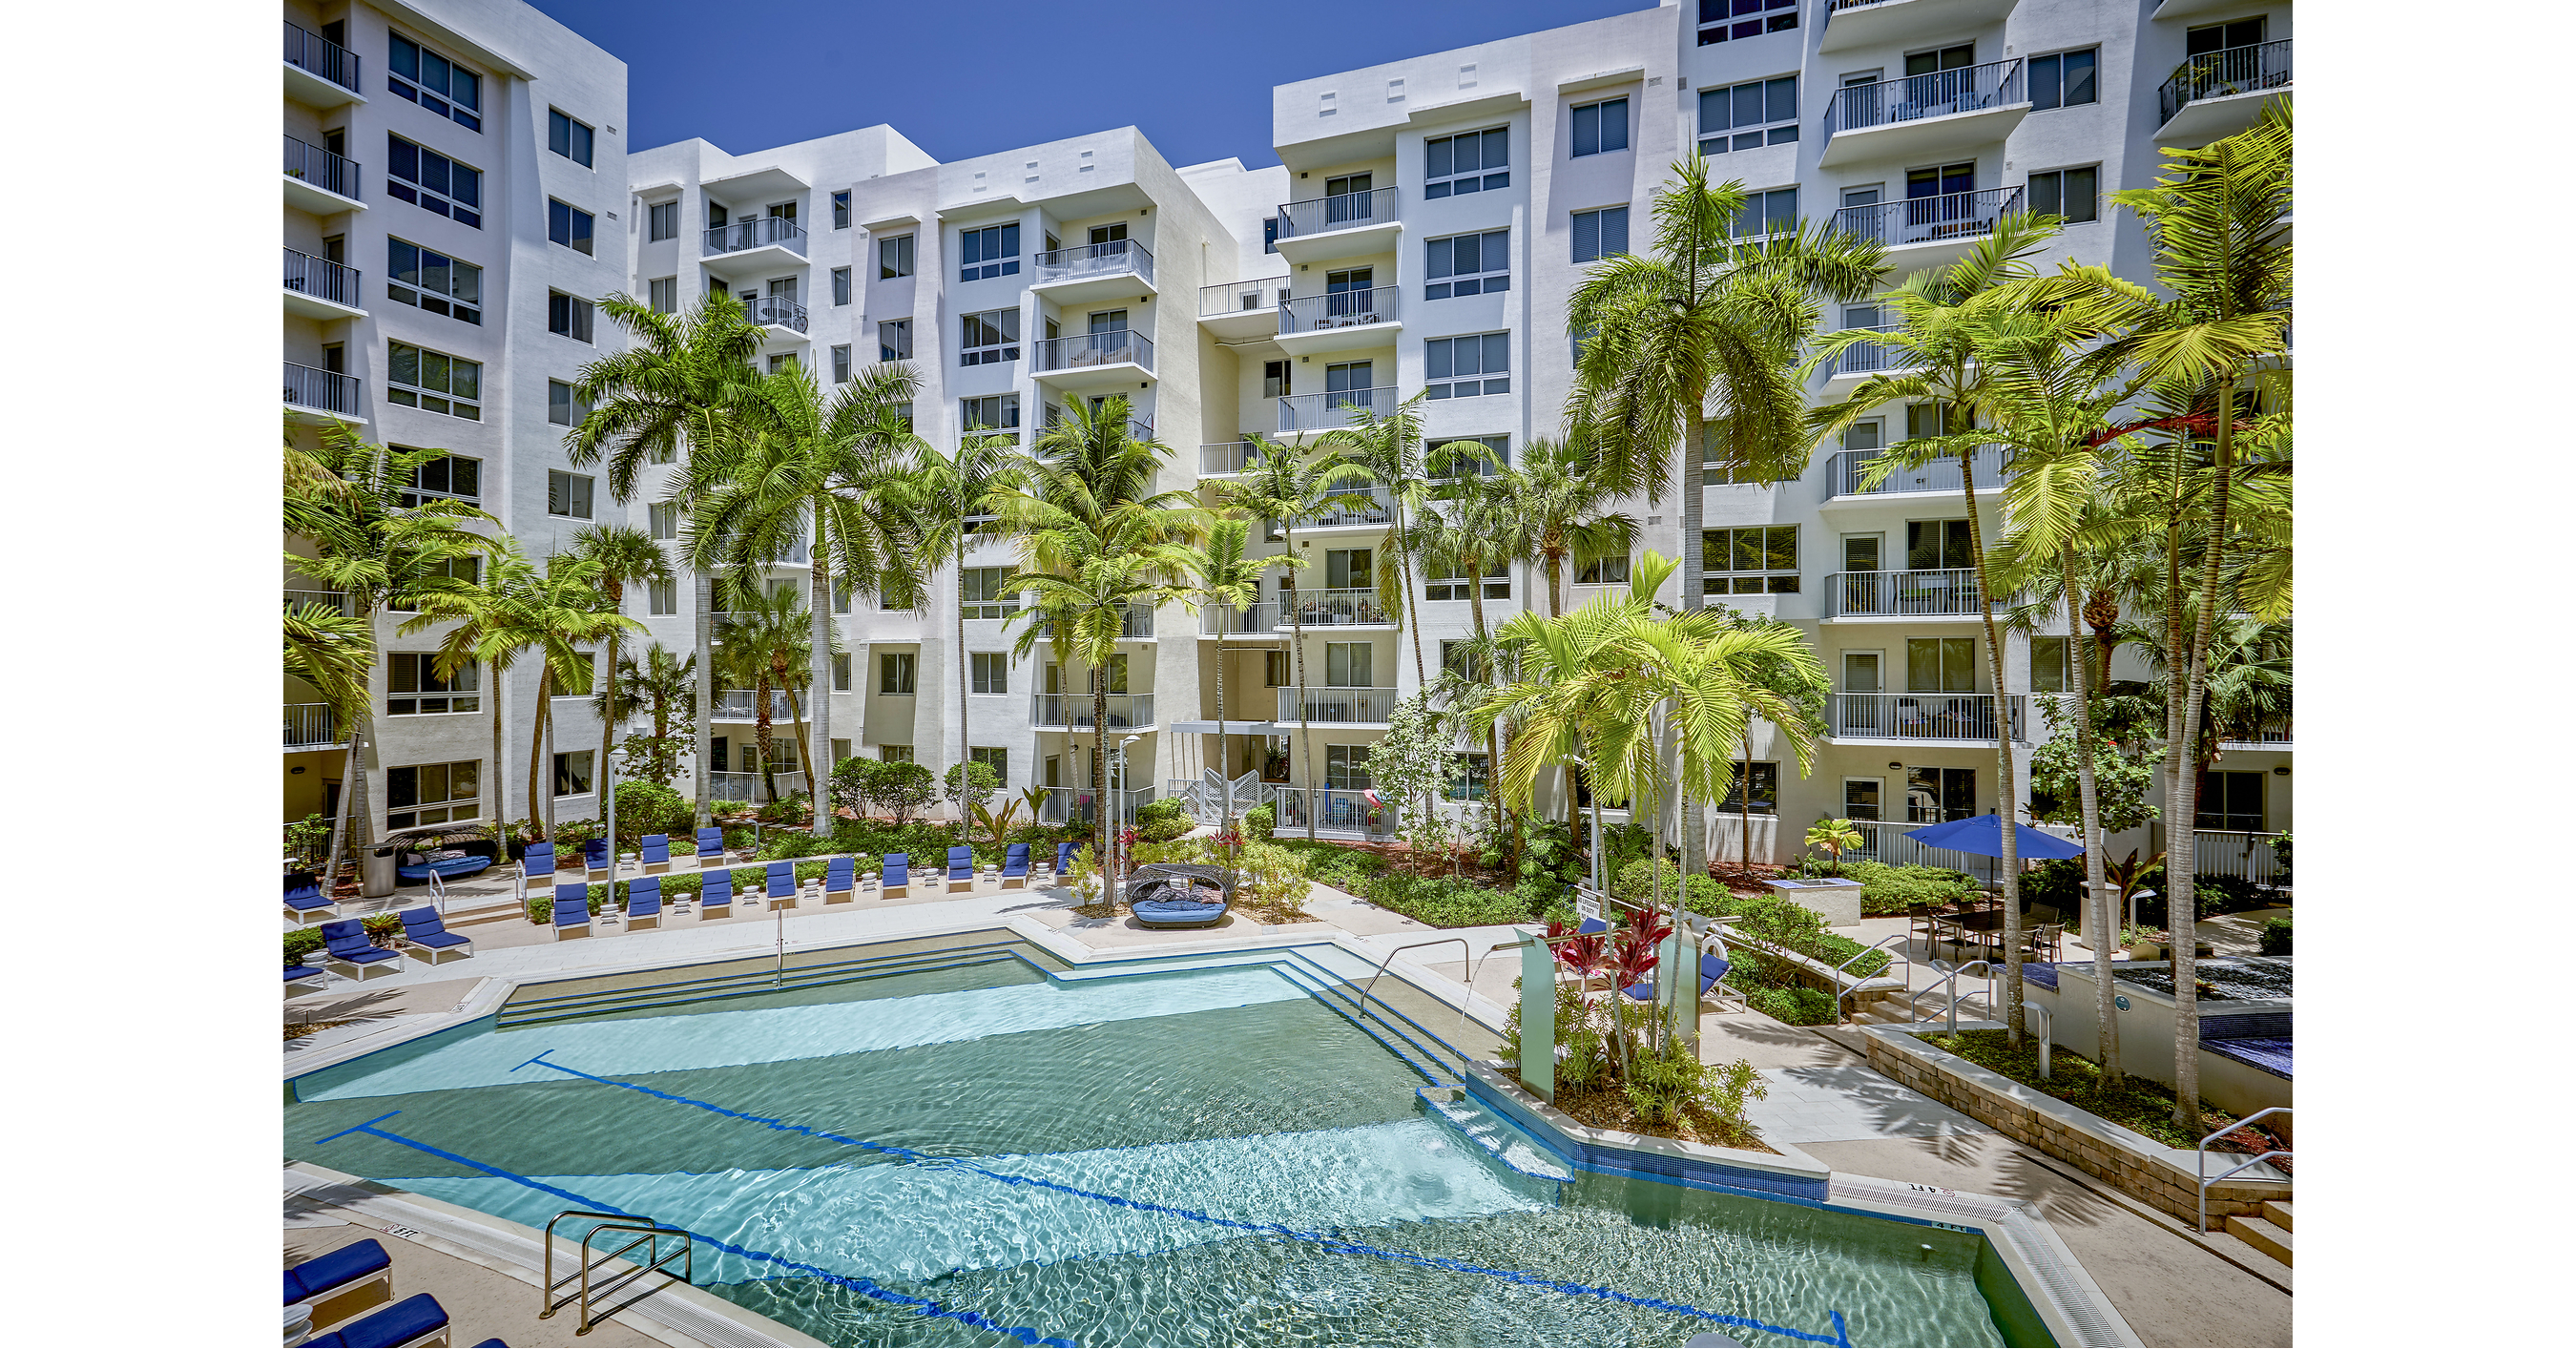
Griffis Residential announced Fund VII’s first close with approximately $207 million in capital commitments, succeeding its $525 million Fund VI. The fund has acquired Griffis North Olive, a 263-unit West Palm Beach community, for approximately $104 million—an estimated 25% below replacement cost. Griffis said it sees discounted Class A multifamily assets as an opportunity amid the current real estate recession.
Analysis
The signal is capital formation, not proof of a multifamily recovery. A first close demonstrates that some investors are willing to commit to the strategy, but it does not establish final fund size, deployment pace, or attractive net returns. The more useful underwriting question is whether acquisition pricing translates into durable cash-on-cash yield after concessions, insurance, property taxes, and renovation costs. A discount to replacement cost is a weak anchor if existing supply is still competing aggressively for residents.
If disciplined buyers can acquire assets below economically viable new-build cost, the second-order benefit may emerge over 6–18 months: fewer development starts, easing future supply pressure, and improved pricing power for stabilized apartment owners. That does not eliminate near-term exposure to elevated deliveries and rent concessions in specific markets. South Florida also warrants scrutiny for insurance and climate-related operating-cost volatility, which can erode value-add returns.
There is no direct public-equity exposure identified here. The announcement is too small and too early to justify a broad apartment trade; treat it as a transaction-market datapoint, not a sector catalyst. The thesis weakens if apartment operators continue reporting deteriorating same-store revenue, persistent concessions, or higher operating costs, or if financing conditions prevent private buyers from closing acquisitions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate trade on the announcement alone. Track apartment REIT earnings and guidance for same-store revenue, concessions, expense growth, and market-level supply before changing sector exposure.
- Watch for additional private-fund closes and completed transactions. Repeated acquisitions at prices below replacement cost would support a medium-term supply-curtailment thesis; announced commitments without deployment would not.
- For any prospective value-add exposure, require asset-level verification of in-place and achievable rents, renovation costs, insurance premiums, taxes, and debt terms. Do not use the stated replacement-cost discount as a standalone valuation signal.
- Falsification watch: worsening apartment revenue trends or operating-cost guidance, especially in South Florida, would challenge the recovery thesis even if transaction pricing appears attractive.
More News
- Wall Street Week | Michigan Manufacturing, AI Debt Investments, Baby Bonds, Canadian Coal Fight
- Tesla drops 'Full Self-Driving' brand name in Europe after regulator pushback
- SpaceX makes big move into wireless. These once 'obsolete' tech stocks could benefit
- MTY Food Group Inc Profit Retreats In Q3
- Why is T-Mobile stock tumbling today?
- Wall Street sees buying opportunity in banks as shares tank ahead of earnings