
The SpaceX threat to telecom is real. How it could play out
Source: CNBC
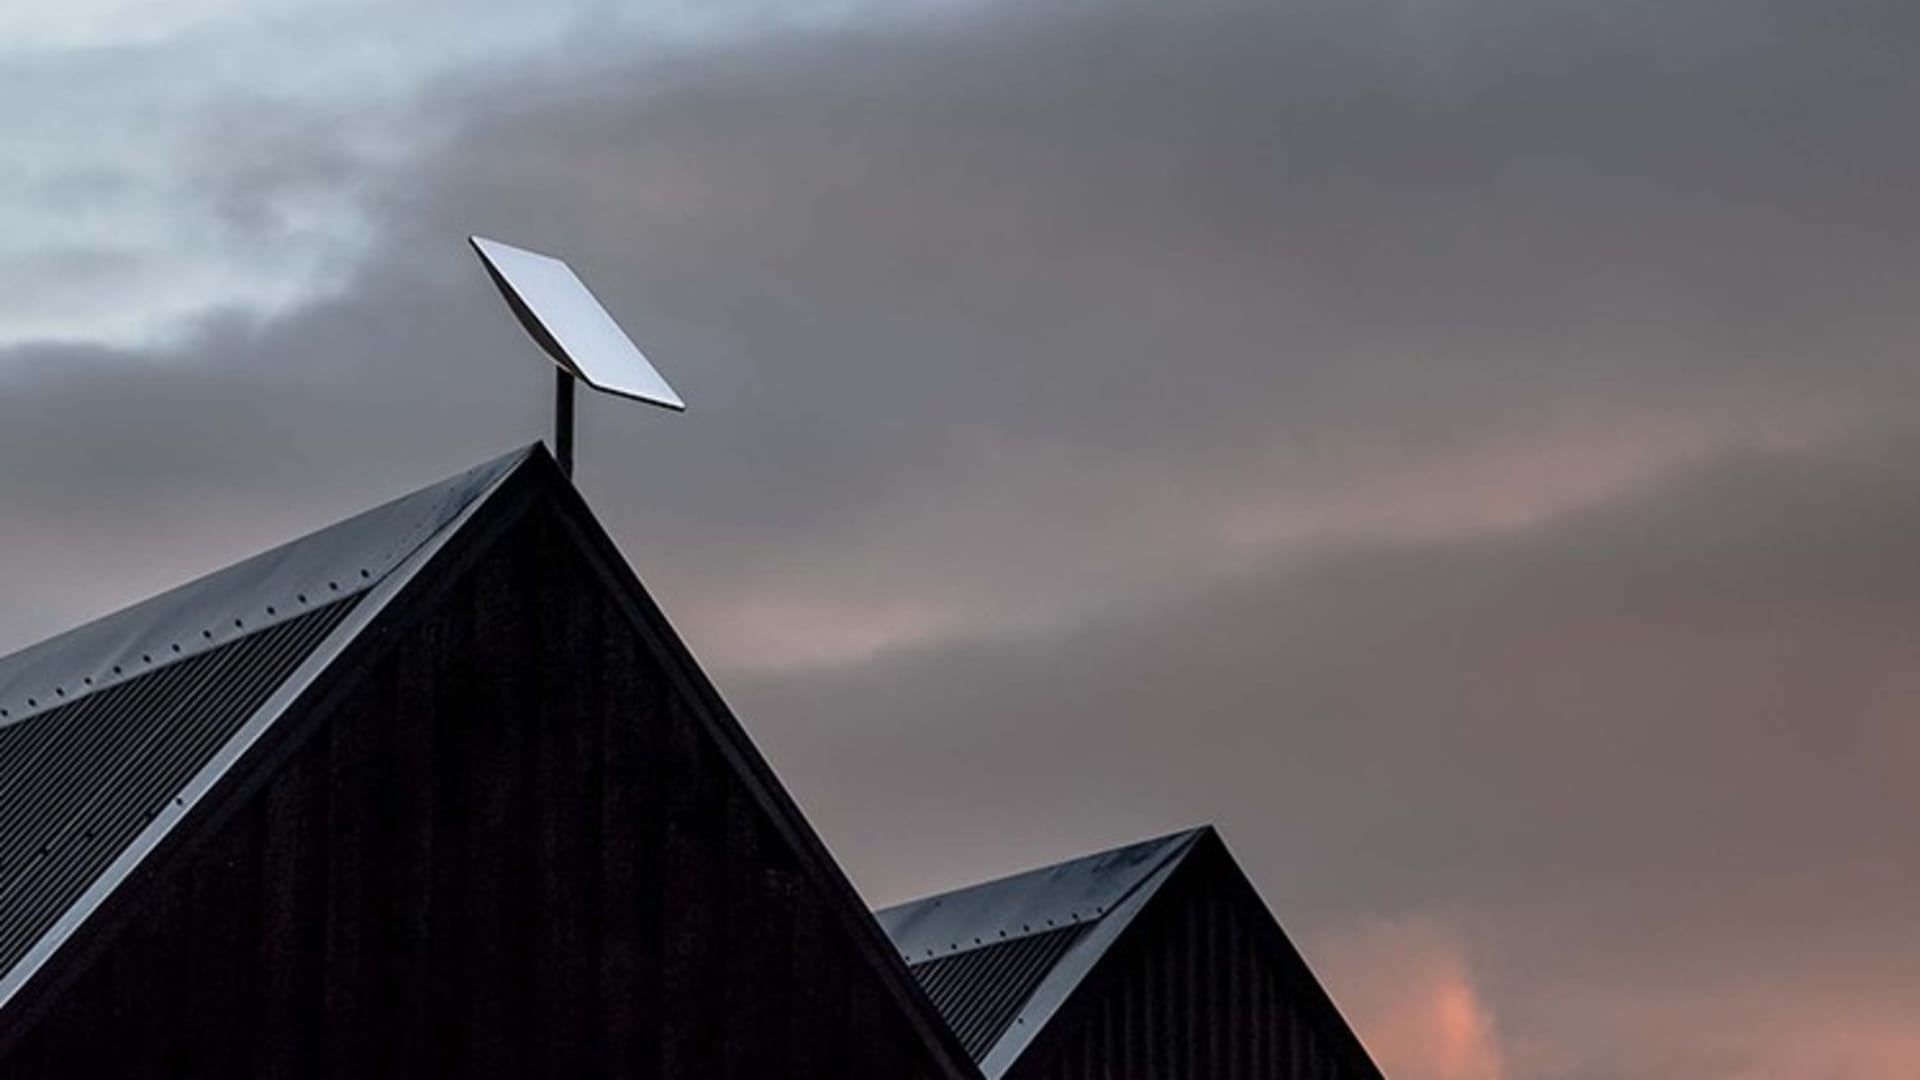
SpaceX's spectrum acquisition and FCC authorization to deploy 15,000 direct-to-device satellites have raised expectations that Starlink could become a fourth U.S. wireless competitor, potentially reaching 13% market share over the next 10 years, according to Pivotal Research. The Big 3 telecoms lost billions in market value after the announcement before recovering somewhat; analysts see a long infrastructure buildout, while near-term competition may come through satellite, WiFi and partnerships. Carriers may respond with bundling, which Bank of America says can reduce churn by up to 50%; some analysts view the sell-off as a buying opportunity, and others question whether SpaceX's spectrum moves are leverage for an MVNO deal.
Analysis
The first-order risk is multiple compression, not an imminent collapse in carrier cash flows: a credible new entrant can raise the expected cost of retention and spectrum even before it wins customers. If incumbents respond with richer bundles, lower churn may come at the cost of discounts and weaker service-level monetization. That makes subscriber retention alone a poor read-through; watch net adds alongside ARPU, promotions, and broadband attachment.
The competitive boundary is not simply satellite versus terrestrial. CMCSA and CHTR could gain negotiating leverage or extend rural reach through a satellite partnership, but also risk weakening the value of their own Wi-Fi/MVNO bundles if SpaceX controls the customer relationship. A partnership announcement would therefore be ambiguous until wholesale economics and customer ownership are clear. AAPL faces a slower second-order risk: less carrier subsidy support could shift device financing and distribution, but a rival handset is not yet evidence of meaningful iPhone displacement.
Over days, expect headline-driven volatility and positioning rather than material earnings revisions. Over 1–3 months, the key catalysts are the FCC process and evidence of spectrum purchases, carrier agreements, or distribution commitments. Over 6–18 months, the thesis only becomes structural if SpaceX demonstrates reliable service and attractive unit economics in populated markets; rural reach alone does not prove a nationwide substitute. The contrarian point: the market may be pricing an eventual fourth network before the difficult urban capacity, customer-acquisition, and handset ecosystem questions are answered.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Ticker Sentiment
Key Decisions for Investors
- Do not chase an outright short in T, VZ, or TMUS on the threat alone. Reassess after evidence of sustained promotional escalation or deterioration in ARPU and churn; improving retention without worsening monetization would falsify the near-term bear case.
- Use any additional telecom-led selloff as a watch point for a relative-value position: long CMCSA/CHTR versus a basket of T/VZ, only if a disclosed SpaceX partnership preserves cable control of the customer and has credible wholesale economics. Without those terms, cable is not a clean hedge or beneficiary.
- Treat FCC action and disclosed spectrum or network commitments as the 1–3 month confirmation catalysts. If approvals or commercial agreements fail to materialize, or deployment remains limited to low-density coverage, reduce the assumed competitive threat rather than extrapolating a national share outcome.
- Keep AAPL exposure tied to verifiable changes in carrier subsidy and device-financing terms, not speculation about a SpaceX handset. Evidence of reduced iPhone promotions or weaker upgrade demand would strengthen the risk; continued carrier support and stable upgrade behavior would argue against it.
- Avoid a direct SPCX trade based solely on strategic ambition: verify deployment timing, spectrum access, partnership economics, and service performance first. The thesis is falsified as a near-term telecom shock if incumbents maintain pricing and retention without material increases in promotional intensity.
More News
- Why this little known Chinese chipmaker has caused a global stock rout
- Apple releases HomeView smart home hub with screen as showcase for Siri AI
- Apple unveils new smart home products, showcasing updated Siri AI
- Iran threatens Gulf data centres: How exposed is the region’s internet?
- Apple's iPhone market share rose despite a downturn in smartphone shipments
- Apple’s smart home event: All 7 devices, prices, and release dates
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Run Cost-Controlled Financial Research in AllMind Agent Studio
- State of Public Markets, June 2026: Higher for Longer Meets the AI Supercycle