
The Kayon Gangga Resort Opens in East Bali, Unveiling a New Luxury Sanctuary Rooted in Culture, Cuisine and Wellness
Source: PR Newswire
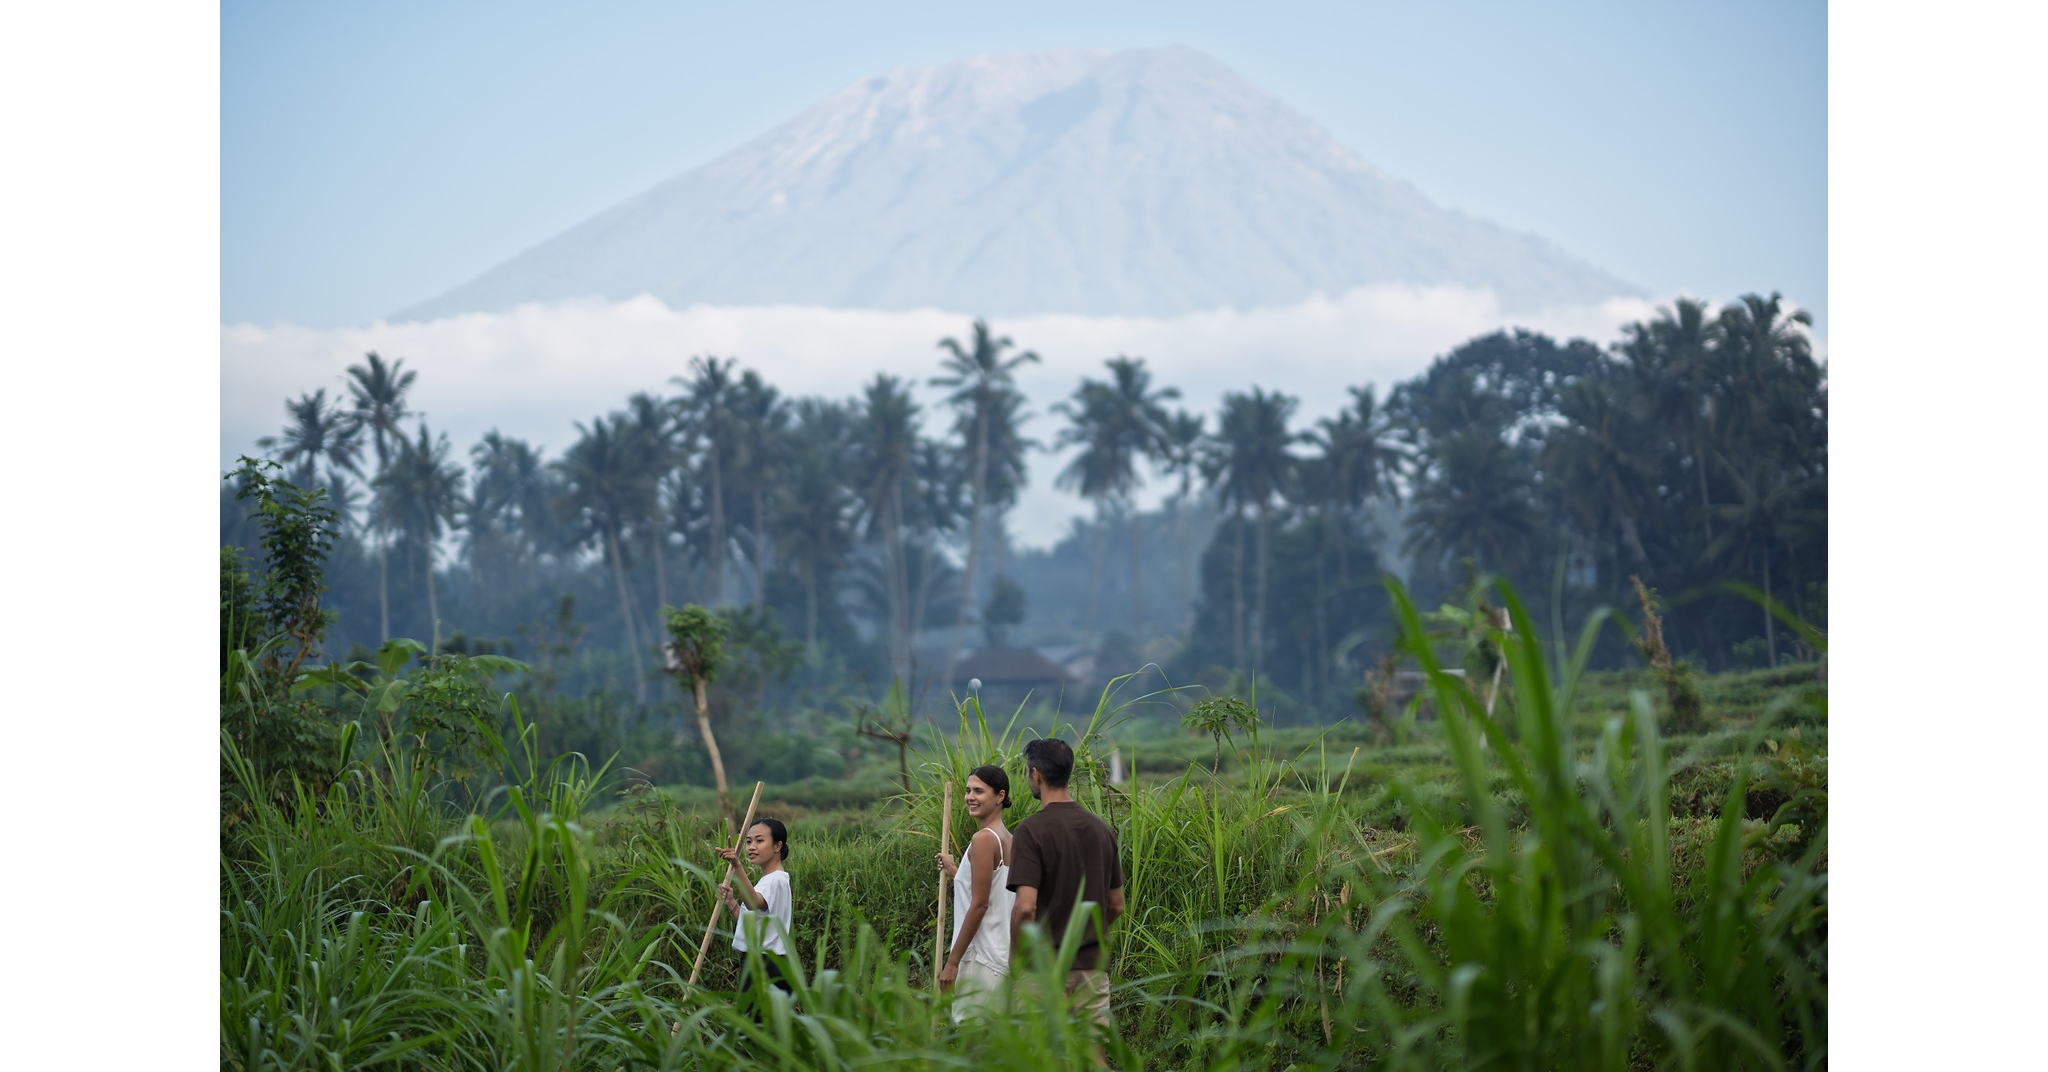
The Kayon Hotels & Resorts opened The Kayon Gangga Resort in Ababi, Karangasem, expanding its Bali boutique-hotel portfolio with a luxury property near Tirta Gangga Water Palace. The resort combines accommodation with three dining concepts, Balinese-inspired wellness services, cultural activities, and adventure offerings. The announcement is a routine hospitality expansion with limited broader market relevance.
Analysis
This is not investable as a standalone event: the operator is privately held, no capacity, ADR, development cost, or booking data is disclosed, and the release provides no basis to underwrite a measurable earnings impact. The relevant listed-market read-through is only marginally positive for Bali’s premium leisure ecosystem, where incremental destination supply can lengthen stays and broaden demand beyond the most concentrated southern-Bali corridors.
The second-order effect is more likely competitive than demand-accretive. Boutique luxury inventory in East Bali may pressure independent local hotels and shift high-spend guests away from Ubud and coastal resorts, while globally branded operators with loyalty distribution—Marriott (MAR), Hilton (HLT), Hyatt (H), and Accor—remain better positioned to monetize any broad improvement in Indonesian inbound travel. New experiential supply also raises the bar for food, wellness, and excursion partners, but the small scale implied by the property makes any supplier impact immaterial.
Over the next 1-3 months, the useful catalyst is not this opening but Bali airport international-arrival growth, hotel occupancy/ADR data, and evidence that East Bali can sustain premium rates outside peak season. Over 6-18 months, increased room supply without corresponding airlift expansion would dilute regional pricing power; Indonesian rupiah weakness may support foreign demand but also raises local operating-cost and imported-capex volatility. A contrarian view is that destination diversification could be structurally positive for Bali rather than cannibalistic, but that requires independently observable growth in length of stay and visitor spend.
No directional trade is warranted. Treat this as a data point for a broader Indonesia tourism recovery monitor rather than a catalyst for listed lodging equities.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No immediate position: do not trade MAR, HLT, H, or ACCOR on this announcement; the disclosed information is insufficient to establish revenue or valuation sensitivity.
- Create a 1-3 month watch alert for Bali international arrivals, Ngurah Rai capacity/route additions, and regional hotel ADR/occupancy. Consider a long H or MAR only if premium international arrivals and Bali ADR both accelerate for two consecutive monthly readings.
- For Indonesia exposure, monitor PT Aviasi Pariwisata Indonesia-linked travel assets and listed regional proxies only after verified airlift expansion; the key falsifier for a tourism-bull thesis is occupancy growth lagging new room supply, signaling rate competition.
- If Bali supply growth becomes broad while arrivals decelerate, favor asset-light global franchisors/management companies such as MAR over locally concentrated hotel owners, whose fixed-cost exposure is more vulnerable to ADR compression.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Google rolls out Gemini 4 Argon, its most advanced AI model
- Goldman pushes Fed rate hike to December after cooler inflation
- NIO reports 37,408 vehicle deliveries in September, up 7.7% YoY
- Meta stock enjoys best month since 2022 on AI momentum
- Huawei unveils Mate 90 phones, leans on homegrown chip design to offset US curbs