
Emdoor Information Strengthens ODM Customization for Rugged Computing Solutions
Source: PR Newswire
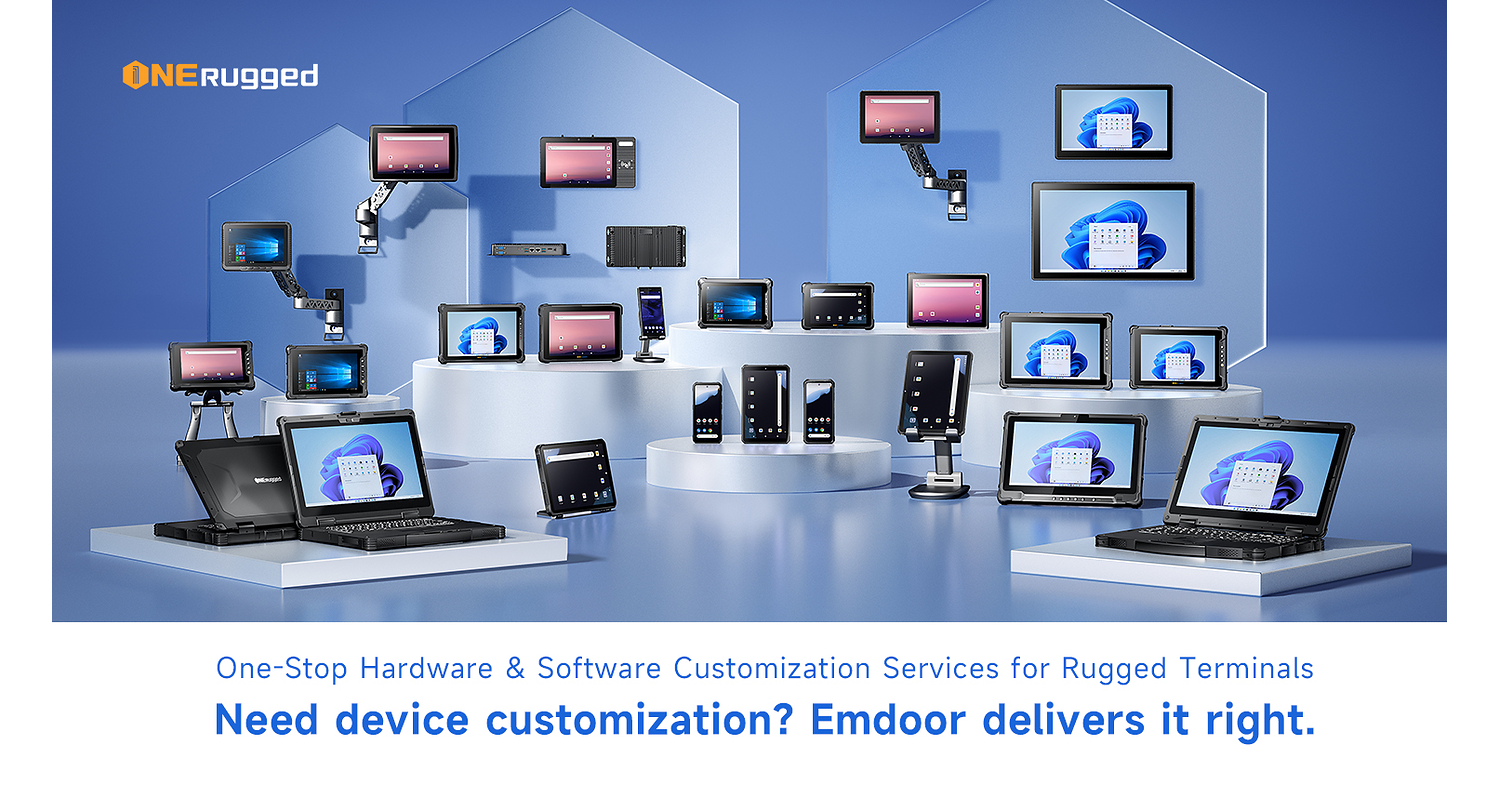
Emdoor Information says it has expanded end-to-end ODM customization for rugged computing devices, supporting standard configurations within 7 days and processing 400+ customized devices per day. Its workflow includes hardware modification, software customization (Windows/Android/Linux), testing/quality inspection, and mass production, with 7–30 day timelines for deeper integrations. The update is incremental operational/production capacity news with limited immediate market impact, but it is directionally positive for its ability to serve industrial and public-sector demand.
Analysis
This reads more like evidence of ODM capability maturation than a single-company growth inflection. The bigger market mechanism is that rugged devices are moving from bespoke hardware to software-defined, modular endpoints, which tends to compress OEM differentiation and shift value toward silicon, connectivity, and device-management layers. That is modestly constructive for QCOM because 5G, GNSS, security, and low-power edge integration are exactly the attach points that survive customization; it is more neutral-to-negative for legacy x86 incumbency if buyers can swap platforms without changing workflows.
The second-order effect is that faster turnaround and higher customization throughput lower procurement friction for enterprises and public-sector fleets, which should expand replacement cycles and pilot conversions over 1-3 quarters. That favors Android/MDM ecosystems and integrated fleet-management software more than bare-metal device makers. GOOGL benefits only indirectly via Android enterprise penetration and cloud-managed endpoints; the economic impact is likely too small for a standalone equity call unless this signals broader enterprise Android share gains.
Contrarian view: the market may overread this as a moat story. In practice, ODM customization can also be a commoditization signal if many vendors can assemble similar rugged products with interchangeable modules. If pricing pressure emerges, the winner is not the assembler but the platform with the strongest bill-of-materials leverage and software lock-in. The key falsifier is mix: if customized orders fail to lift gross margin or if platform share tilts away from QCOM/Android toward lower-cost alternatives, the thesis breaks over the next 2-4 quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Tactically overweight QCOM versus INTC into the next 1-3 earnings cycles: rugged/industrial edge design wins should favor integrated connectivity + ARM/Android architectures over commodity x86 boxes. Risk/reward improves if QCOM commentary on industrial/IoT attach rates accelerates; falsify if INTC shows stable or rising rugged endpoint share.
- No clean standalone trade on GOOGL, but keep it on watch as an Android enterprise proxy: a sustained increase in fleet-managed rugged endpoints would be a slow-burn tailwind, not a near-term catalyst. Reassess only if enterprise/MDM adoption data improves over 6-12 months.
- Avoid chasing the assemblers as a moat trade; if you want to express the commoditization angle, pair long QCOM / short a diversified hardware basket with higher exposure to low-differentiation device assembly. Exit if gross-margin expansion in ODMs proves durable over two quarters.
- Set an alert for any disclosed design-win cadence or attach-rate data from QCOM in industrial handhelds and vehicle diagnostics over the next 1-2 quarters; without that, this is likely a low-signal PR rather than a tradable inflection.
More News
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge