
Grundig Unveils New Product Lineup at IFA 2026, Marking a New Phase in Strategic Partnership
Source: PR Newswire
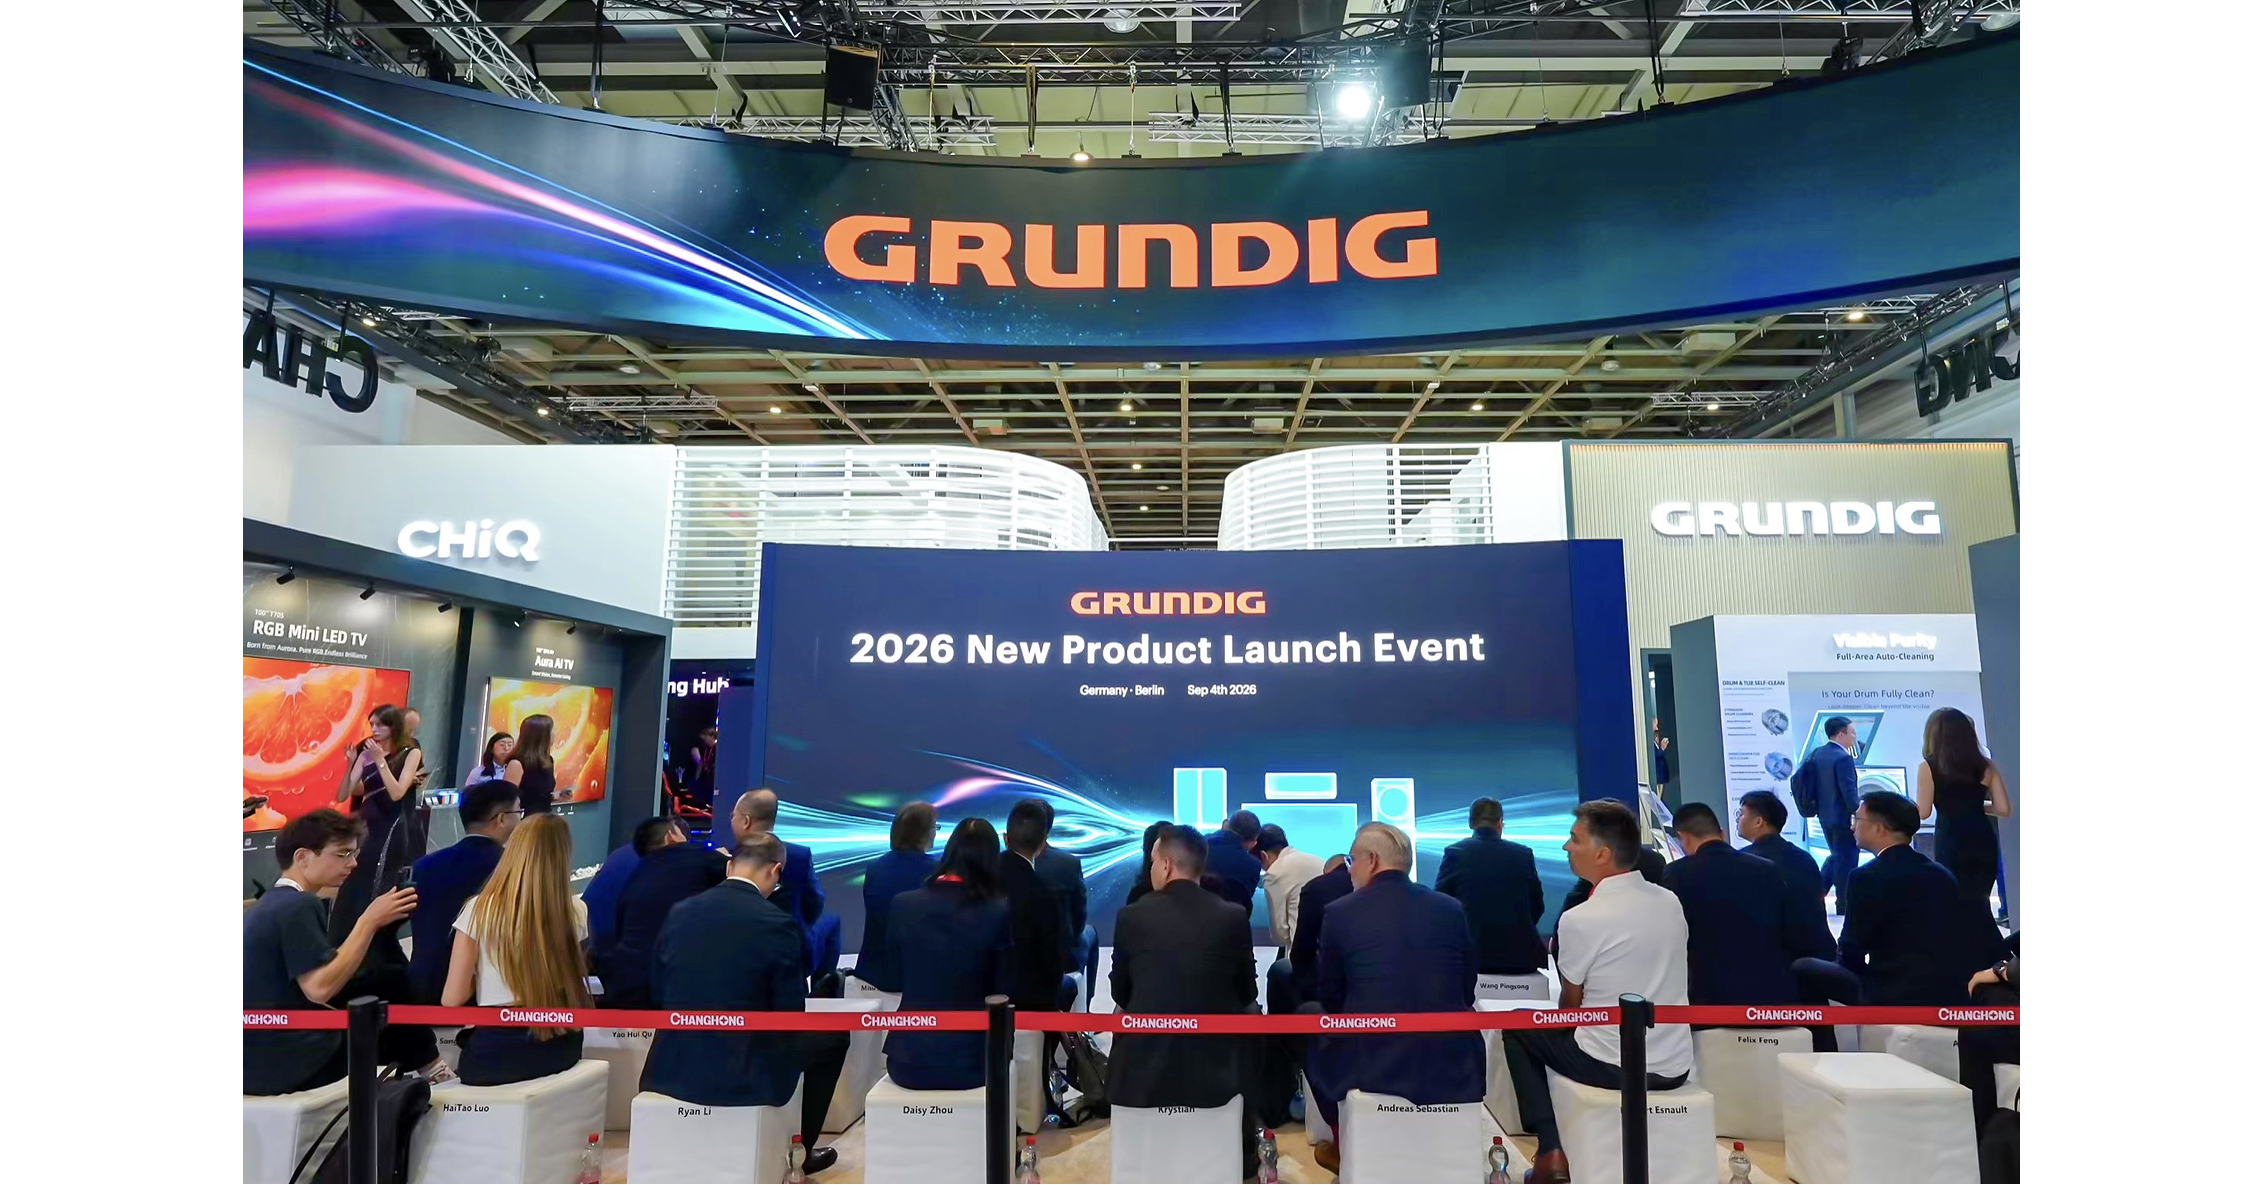
Grundig unveiled a new IFA 2026 home-appliance lineup, highlighting the AURORA 100 flagship TV with 9,720 independently controlled dimming zones and a 39mm slim profile, plus the Space Pro refrigerator series (599mm depth, 600L capacity, -3.5°C Fresh Zone). The release also signals a new phase of its strategic partnership—after Grundig’s brand licensing to Changhong in select categories/markets—aiming to combine Changhong’s R&D/manufacturing/supply chain with Grundig’s European presence to expand distribution and innovation. Overall, the news is a constructive product-and-partnership milestone, but with no explicit financial impact or guidance.
Analysis
This is more a margin-architecture story than a product-launch story. The economically relevant question is whether the partnership turns a heritage brand into an asset-light royalty stream or simply hands over premium positioning to a lower-cost OEM. In the first 1-2 quarters, the market should expect channel fill and promo spend rather than visible EBIT acceleration, so any near-term rally in the equity should be treated as narrative-driven unless management quantifies pricing power.
The second-order winner is the manufacturing/ODM side if it can move up the value chain without needing deep discounting; the loser is the set of incumbents that rely on brand familiarity and retail shelf space to defend margin. European appliance and TV peers with weaker design moats are most exposed if this model proves repeatable, because retailers may use it to source “premium” features at lower cost. The real risk is not supply chain disruption but brand dilution: if sell-through requires promotions, the economic transfer shifts from margin expansion to margin compression.
Catalyst timing matters. Over 1-3 months, watch for retailer adoption, inventory changes, and any disclosed royalty or margin contribution; over 6-18 months, the thesis only works if the partnership expands without eroding ASPs. Contrarian view: the market may be underestimating how hard it is to sustain a European premium halo when product architecture and manufacturing are increasingly externalized; if consumers treat the lineup as another imported appliance bundle, the moat is thinner than the marketing suggests.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Do not chase TBHC on the press event alone; treat it as a watch item until management discloses royalty economics, gross margin uplift, or channel sell-through data.
- Conditional pair trade: long HSHAY / short WHR over 3-6 months if European retail adoption looks real; target 10-15% relative outperformance, invalidated if promotional pricing rises or launch volumes disappoint.
- For a more Europe-specific hedge, consider long HSHAY / short ELUXY on any confirmation that the partnership is taking share in premium appliance categories; stop if Electrolux data show no pricing pressure.
- If you need convex exposure, use a small call spread in the likely beneficiary only after 1-quarter sales data confirm that the brand extension is translating into revenue, not just PR.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- Zoom and big financial firms add ‘Proof of Human’ badges from Sam Altman’s World to stop fraud and deep fakes