
The latest oil-price shock rippling through the economy is a refining crisis — not a crude crisis
Source: MarketWatch
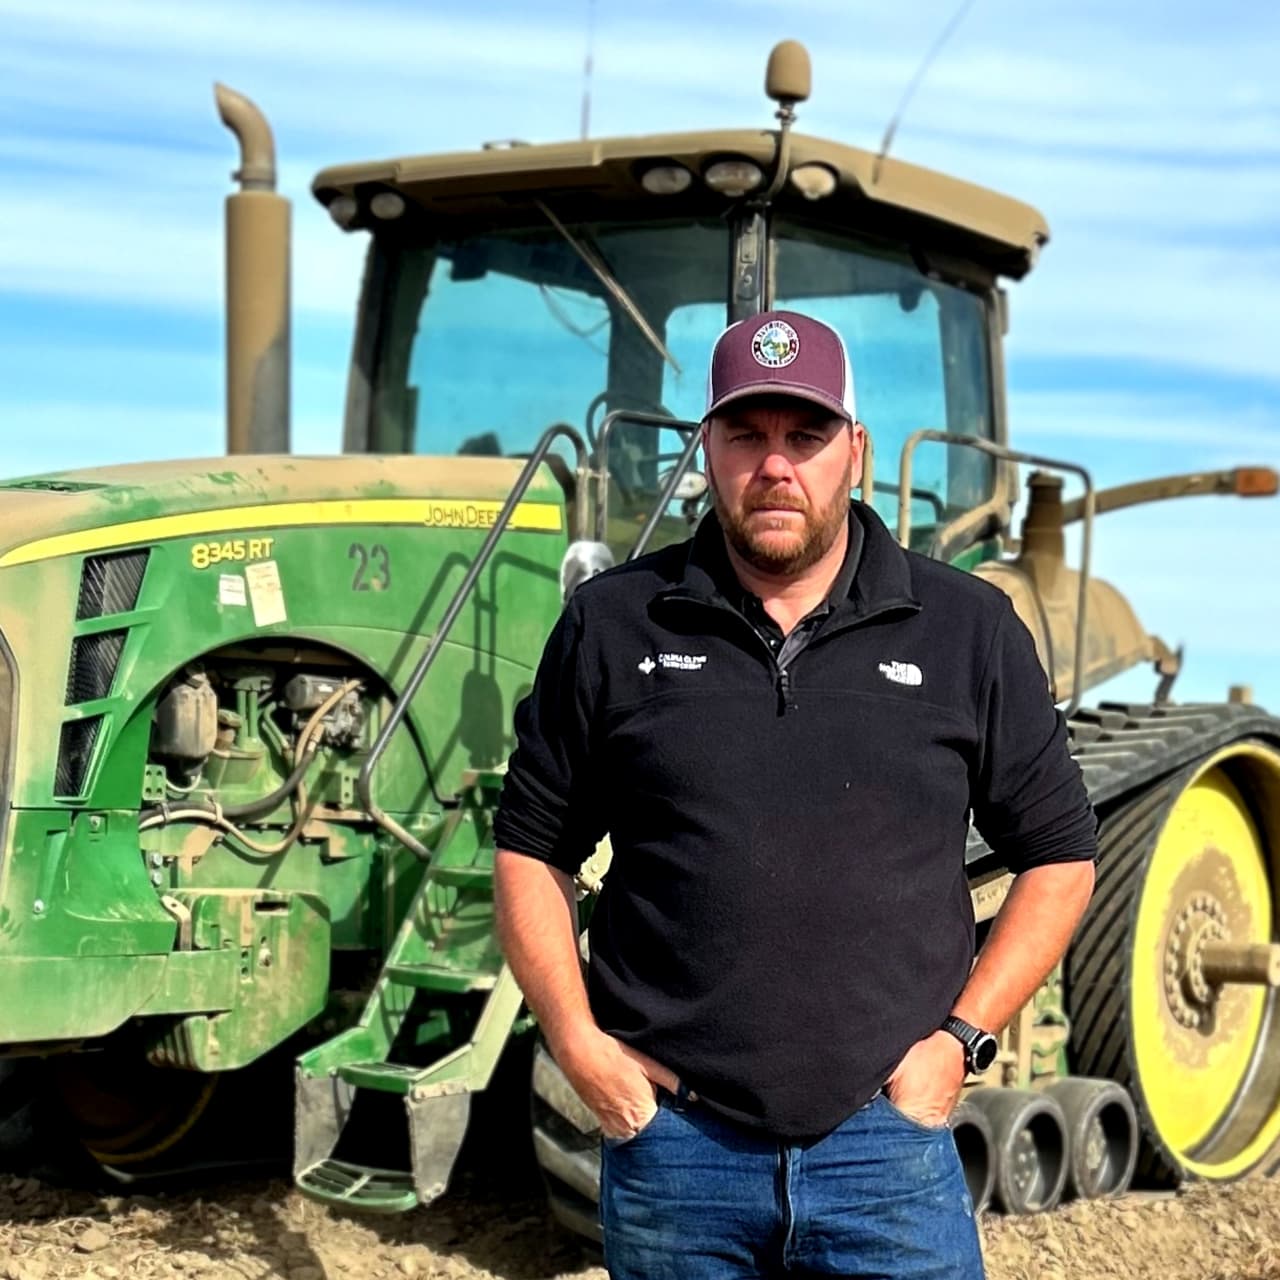
A 3,500-acre Sacramento Valley farm is paying roughly twice as much for diesel during the fall harvest, while also facing higher fuel surcharges for services such as crop dusting. Because crops cannot be left unharvested without damaging future farming operations, the producer must absorb the cost increase, pressuring agricultural margins and potentially contributing to higher food prices.
Analysis
The relevant transmission is not simply higher farm fuel expense; it is a working-capital and harvest-timing shock concentrated in fuel-intensive, perishable crops. California processors and growers cannot defer harvest, so near-term margins absorb the increase unless contracted pricing resets. That raises the probability of tighter procurement and reduced discretionary field activity next planting season, particularly for lower-return annual crops, rather than an immediate broad food-price pass-through.
Over the next 1-3 months, watch California spot trucking/diesel differentials and processing-company commentary for evidence that costs are being passed through. If growers cut acreage in the next cycle, the 6-18 month effect is most acute in tomatoes, rice and tree-crop maintenance: reduced input intensity can impair yields with a lag. Consumer packaged-food companies with material tomato, rice, nut or freight exposure may face a modest gross-margin headwind, but branded players with pricing power should fare better than private-label-heavy suppliers.
The contrarian point is that this is unlikely to be a clean long-energy signal: agricultural diesel demand is relatively inelastic during harvest but too small to move the fuel complex. The more investable implication is regional basis and margin dispersion. A normalization in West Coast diesel premiums, or a rapid decline in crude, would remove the cost shock before it affects acreage decisions; conversely, sustained elevated fuel costs through spring planting would turn a transient margin issue into a supply response.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.35
Key Decisions for Investors
- No standalone directional equity trade on this datapoint; treat it as a watch item until California diesel basis remains elevated through the spring planting window or processors explicitly cut guidance.
- Monitor long CALF / short broad consumer-staples exposure only if cattle-feed and crop-acreage data confirm broader California agricultural stress; current evidence is insufficient for execution.
- For a 1-3 month inflation hedge, maintain a modest long XLE versus short XLP bias only if West Coast diesel cracks widen further; invalidate if California diesel retail/wholesale premiums normalize materially or crude declines below the level that triggered the move.
- Screen packaged-food names with high tomato, rice, nut and freight inputs against their pricing cadence before earnings; favor branded, higher-margin operators over private-label-oriented peers where price pass-through lags costs.
More News
- Dollar at 17-month high as global bond rout hits euro
- Trump says US may ask Europe to release diesel reserves
- Developing countries hit by overlapping crises, UNDP chief warns
- Latin America most exposed to any US ban on diesel exports, Goldman Sachs says
- Latest Oil Market News and Analysis for Oct. 2
- Trump launches midterms campaign blitz amid record low approval ratings
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Research Agent?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction