
On the six-month anniversary of the Iran war, divisions appear on Wall Street over the trajectory for oil prices
Source: MarketWatch
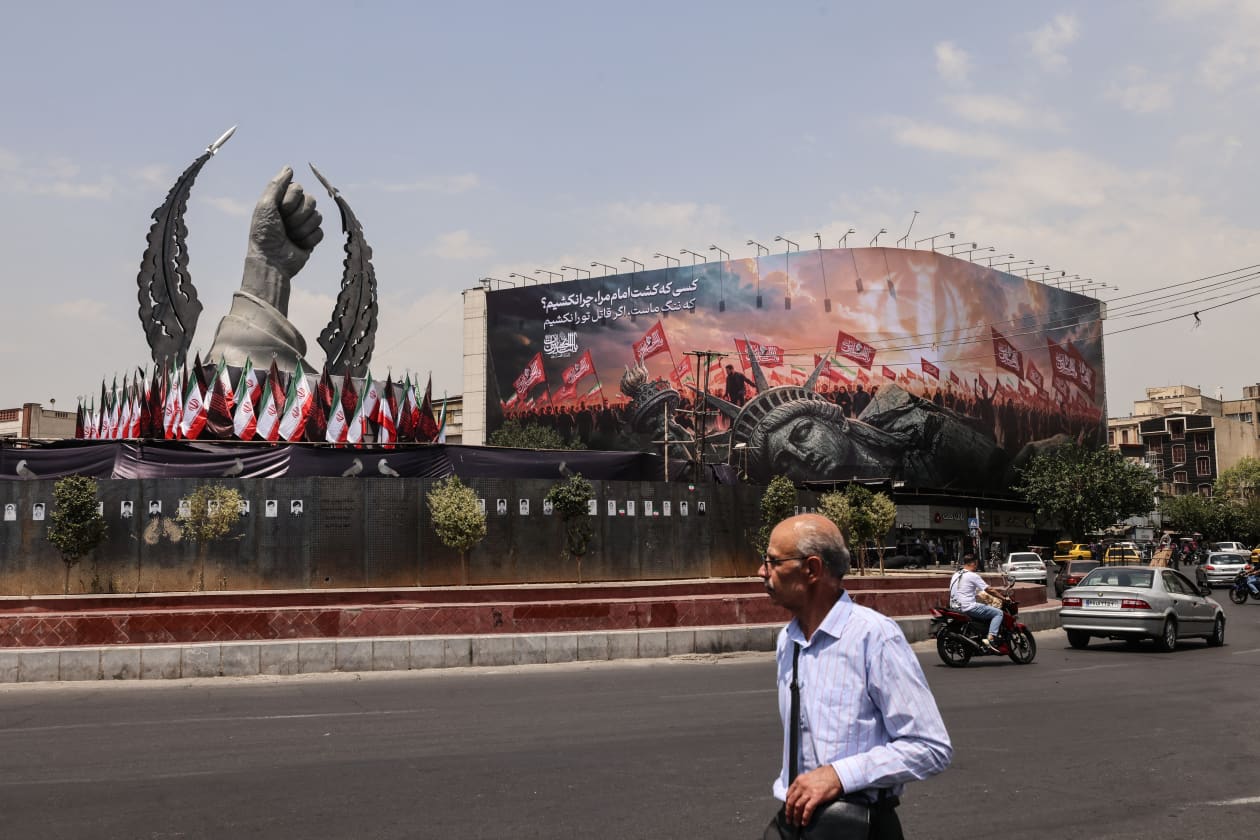
Six months into the Iran war, Wall Street is split on oil’s path: Goldman says the market is “adapting” to the conflict, while RBC strategists (Helima Croft) warn the market may be “a little too sanguine” about an imminent end. The disagreement centers on whether further Iran-related disruptions could still trigger additional oil spikes.
Analysis
The key signal is not the oil call itself; it is the market’s apparent comfort with a geopolitical risk premium that can gap higher faster than fundamentals can reprice. In this setup, the clean winners are upstream energy equities and commodity-vol desks that monetize convexity, while the obvious losers are air, transport, chemicals, and any consumer franchises with low pricing power if crude reprices even modestly. The second-order effect is that headline calm can suppress hedging activity, leaving the market more vulnerable to a sharp squeeze on the first credible escalation.
Time horizon matters. Over the next few days, spot oil may continue to trade as if the conflict is a background factor; over 1-3 months, the catalyst path is shipping disruption, insurance costs, countermeasures, and any inventory draw that validates a tighter physical balance. If those don’t materialize, geopolitical premium bleeds out quickly and outright longs will underperform even if the macro narrative stays loud.
The contrarian view is that consensus is over-indexing on ‘adaptation’ while underpricing gap risk and the value of optionality. That argues for owning convexity rather than chasing direction: if oil is range-bound, the premium is limited; if another incident hits, upside can re-rate abruptly. Goldman itself is more a read-through on market psychology than a direct earnings event, so I would not force a fundamental GS trade unless commodity volatility starts showing up in desk revenue revisions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Ticker Sentiment
Key Decisions for Investors
- Buy 1-3 month upside convexity in energy via XLE or USO call spreads on weakness; prefer defined-risk structures over outright longs because the thesis is a gap-up scenario, not a slow grind higher. Falsify if crude rolls over and implied vol stays muted despite headline risk.
- Pair trade: long XLE / short JETS or IYT for 4-8 weeks to express ‘oil spike hurts demand’ without taking outright crude beta. Best risk/reward if the market is complacent and airfares/freight pricing has little room to absorb higher fuel costs.
- If Brent/USO implied vol is at the low end of its 1-year range, buy vol rather than delta. The edge is in skew compression: any escalation can force dealers to hedge into a thin market.
- Do not short energy purely on the ‘markets are adapting’ narrative until there is a confirmatory de-escalation signal or a visible rebuild in inventories. If the next headlines are benign and prompt spreads flatten, take profits on long convexity quickly.
More News
- Take Five: Bangkok blues
- Stock futures are little changed with big banks set to kick off earnings season: Live updates
- CNBC Daily Open: Will America open another front in the Middle East? Trump is considering
- JPMorgan Chase, Goldman and other big banks report earnings this week. What to expect
- Here are the 6 big things we're watching in the stock market this week
- By The Way: Headlines You May Have Missed
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check